POS AM: Post-effective amendment to a registration statement that is not immediately effective upon filing
Published on September 22, 2026
As filed with the Securities and Exchange Commission on September 21, 2026
No. 333-294316
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
NO. 1
to
FORM S-1
REGISTRATION STATEMENT
UNDER THE SECURITIES ACT OF 1933
(Exact name of registrant as specified in its charter)
| 6770 | 39-3528250 | |||
| (State or other jurisdiction of incorporation or organization) |
(Primary Standard Industrial Classification Code Number) |
(I.R.S. Employer Identification No.) |
500 W. 7th Street, Suite 1500
Fort Worth, Texas 76102
(800) 461-1604
(Address, including zip code, and telephone number, including area code, of registrant’s principal executive offices)
Brett Barnes
Executive Vice President and General Counsel
500 W. 7th Street, Suite 1500
Fort Worth, Texas 76102
(405) 870-3781
(Name, address, including zip code, and telephone number, including area code, of agent for service)
Copies of all communications, including communications sent to agent for service, should be sent to:
George J. Vlahakos
John Stribling
Sidley Austin LLP
1000 Louisiana Street,
Suite 5900
Houston, Texas 77002
Tel: (713) 495-4500
Approximate date of commencement of proposed sale to the public: From time to time after the effective date of this Registration Statement.
If any of the securities being registered on this Form are to be offered on a delayed or continuous basis pursuant to Rule 415 under the Securities Act of 1933, as amended (the “Securities Act”) check the following box: ☒
If this form is filed to register additional securities for an offering pursuant to Rule 462(b) under the Securities Act, check the following box and list the Securities Act registration statement number of the earlier effective registration statement for the same offering. ☐
If this form is a post-effective amendment filed pursuant to Rule 462(c) under the Securities Act, check the following box and list the Securities Act registration statement number of the earlier effective registration statement for the same offering. ☐
If this form is a post-effective amendment filed pursuant to Rule 462(d) under the Securities Act, check the following box and list the Securities Act registration statement number of the earlier effective registration statement for the same offering. ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☐ | Accelerated filer | ☐ | |
| Non-accelerated filer | ☒ | Smaller reporting company | ☒ | |
| Emerging growth company |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial standards provided pursuant to Section 7(a)(2)(B) of the Securities Act.
The registrant hereby amends this Registration Statement on such date or dates as may be necessary to delay its effective date until the registrant shall file a further amendment which specifically states that this Registration Statement shall thereafter become effective in accordance with Section 8(a) of the Securities Act of 1933 or until this Registration Statement shall become effective on such date as the Commission, acting pursuant to said Section 8(a), may determine.
EXPLANATORY NOTE
The information in this preliminary prospectus is not complete and may be changed. The securities offered by this preliminary prospectus may not be issued until the registration statement filed with the Securities and Exchange Commission, of which this preliminary prospectus is a part, is declared effective. This preliminary prospectus does not constitute an offer to sell these securities and it is not soliciting an offer to buy these securities in any jurisdiction where the offer or sale of these securities is not permitted.
PRELIMINARY PROSPECTUS — SUBJECT TO COMPLETION, DATED September 21, 2026
PRESIDIO PRODUCTION COMPANY
11,887,403 SHARES OF CLASS A COMMON STOCK ISSUABLE
UPON THE EXERCISE OF WARRANTS
133,332 WARRANTS
24,222,945 SHARES OF CLASS A COMMON STOCK
This prospectus relates to the issuance by Presidio Production Company (“Presidio,” “we,” “us” or the “Company”) of up to 11,887,403 shares of Class A Common Stock, par value $0.0001 (the “Presidio Class A Common Stock”) that may be issued upon the exercise of the Presidio Warrants (as defined below) and the offer and sale from time to time by the selling securityholders named in this prospectus (the “Selling Securityholders”), or their permitted transferees, of up to 24,222,945 shares of Presidio Class A Common Stock and up to 133,332 Presidio Warrants.
The 11,887,403 shares of Presidio Class A Common Stock that may be issued upon the exercise of the Presidio Warrants that this prospectus relates to include: (i) up to 11,666,571 shares of Presidio Class A Common Stock that may be issued upon the exercise of 11,666,571 warrants to purchase Presidio Class A Common Stock at an exercise price of $11.50 per share (the “Public Warrants”) and (ii) up to 220,832 shares of Presidio Class A Common Stock that may be issued upon the exercise of 220,832 warrants to purchase Presidio Class A Common Stock at an exercise price of $11.50 per share (the “Private Placement Warrants” and together with the Public Warrants, the “Presidio Warrants”).
The shares of Presidio Class A Common Stock and Presidio Warrants offered for resale under this prospectus were issued to the Selling Securityholders (as applicable to each) in accordance with the terms of, and transactions contemplated by, the Business Combination Agreement, dated as of August 5, 2025 (the “Business Combination Agreement”), by and among Presidio MidCo Inc., a Delaware corporation (formerly EQV Ventures Acquisition Corp., a Cayman Islands exempted company) (“EQV”), Presidio (f/k/a Presidio PubCo Inc.), Prometheus PubCo Merger Sub Inc., a Delaware corporation and a direct, wholly owned subsidiary of Presidio (“EQV Merger Sub”), Prometheus Holdings LLC, a Delaware limited liability company and a direct, wholly owned subsidiary of EQV (“Prometheus Holdings”), Prometheus Merger Sub LLC, a Delaware limited liability company and a direct, wholly owned subsidiary of Prometheus Holdings (“Presidio Merger Sub”) and Presidio Investment Holdings LLC, a Delaware limited liability company (“PIH”). The Presidio Class A Common Stock registered hereunder represents the securities issued to the Selling Securityholders pursuant to the terms of the Business Combination Agreement, as applicable to each Selling Securityholder, concurrently with the closing of the transactions contemplated by the Business Combination Agreement (the “Business Combination”).
The Business Combination is described in greater detail in this prospectus. See “Prospectus Summary—The Business Combination.”
The 24,222,945 maximum number of shares of Presidio Class A Common Stock offered for resale under this prospectus consists of: (a) 7,686,960 shares of Presidio Class A Common Stock that were issued to EQV Ventures Sponsor LLC, a Delaware limited liability company, and its affiliates (the “Sponsor”) upon the conversion of 282,314 EQV Class A Shares and 7,404,646 EQV Class B Shares, (b) 160,000 shares of Presidio Class A Common Stock that were issued to the former independent directors of EQV, upon the conversion of 160,000 EQV Class A Shares, (c) 120,000 shares of Presidio Class A Common Stock that were issued to the former independent directors of EQV, upon the conversion of 120,000 EQV Class A Shares, (d) 3,853,562 shares of Presidio Class A Common Stock that were issued in connection with the PIPE Financing (as defined below), (e) 2,717,300 shares of Presidio Class A Common Stock that may be issued upon the conversion of the 27,173 shares of Series B Preferred Stock, (f) 881,250 shares of Presidio Class A Common Stock that may be issued upon the exercise of warrants to purchase Presidio Class A Common Stock at an exercise price of $0.01 per share and (g) 8,803,873 shares of Presidio Class A Common Stock issued, or that may be issued upon the conversion of Prometheus Holdings Common Units (as defined below), to certain of the other Selling Securityholders named herein in connection with the Business Combination as merger consideration.
There are approximately 29,825,480 outstanding shares of Presidio Class A Common Stock as of the date of this prospectus. Given the substantial number of shares of Presidio Class A Common Stock being registered for potential resale by Selling Securityholders pursuant to this prospectus, the sale of shares by the Selling Securityholders, or the perception in the market that the Selling Securityholders intend to sell shares, could increase the volatility of the market price of Presidio Class A Common Stock or result in a significant decline in the public trading price of the Presidio Class A Common Stock. Even if the current trading price of the Presidio Class A Common Stock is close to the price at which the units were initially issued in EQV’s initial public offering, certain Selling Securityholders may have an incentive to sell because they will still profit on sales due to the lower price at which they purchased their shares compared to the public investors. The public securityholders may not experience a similar rate of return on the securities they purchase due to differences in the purchase prices and the current trading price.
Pursuant to this prospectus, the Selling Securityholders are permitted to offer the securities from time to time, if and to the extent as they may determine, through public or private transactions or through other means described in the section of this prospectus entitled “Plan of Distribution” at prevailing market prices, at prices different than prevailing market prices or at privately negotiated prices. The Selling Securityholders may sell shares through agents they select or through underwriters and dealers they select. The Selling Securityholders also may sell their securities directly to investors. If the Selling Securityholders use agents, underwriters or dealers to sell their securities, we will name such agents, underwriters or dealers and describe any applicable commissions or discounts in a supplement to this prospectus if required.
Certain of the securities registered hereby remain subject to contractual transfer restrictions described under “Certain Relationships and Related Person Transactions” and may not be sold until such restrictions lapse.
We have agreed to bear all of the expenses incurred in connection with the registration of these securities. The Selling Securityholders will pay or assume underwriting fees, discounts and commissions or similar charges, if any, incurred in the sale of securities by them.
The Selling Securityholders identified in this prospectus may offer, sell or distribute all or a portion of the Presidio Class A Common Stock included under this prospectus (as applicable to each Selling Securityholder) in the section entitled “Selling Securityholders.” We will not receive any proceeds from the sale of securities by the Selling Securityholders. However, we may receive proceeds from the exercise of the Presidio Warrants and the Series A Preferred Investor Warrants to the extent any such warrants are exercised for cash. The exercise price of the Presidio Warrants is $11.50 per share, and the exercise price of the Series A Preferred Investor Warrants is $0.01 per share. We believe the likelihood that warrant holders will exercise their warrants, and therefore the amount of cash proceeds that we would receive, is dependent upon the trading price of the Presidio Class A Common Stock. If the trading price for the Presidio Class A Common Stock ever falls below $11.50 per share, we believe holders of Presidio Warrants would be unlikely to exercise their warrants.
We may amend or supplement this prospectus from time to time by filing amendments or supplements as required.
The Presidio Class A Common Stock and the Public Warrants are listed on the New York Stock Exchange under the symbols “FTW” and “FTW WS,” respectively. On September 18, 2026, the closing price of the Presidio Class A Common Stock was $10.10 per share, and the closing price of the Public Warrants on September 18, 2026 was $1.03 per warrant.
We are an “emerging growth company” and a “smaller reporting company” as those terms are defined under applicable federal securities laws, and as such, are subject to certain reduced public company reporting requirements.
AN INVESTMENT IN OUR COMMON STOCK INVOLVES SIGNIFICANT RISKS. YOU SHOULD CAREFULLY CONSIDER THE RISK FACTORS BEGINNING ON PAGE 11 OF THIS PROSPECTUS BEFORE YOU MAKE YOUR DECISION TO INVEST IN OUR COMMON STOCK.
Neither the Securities and Exchange Commission nor any other regulatory body has approved or disapproved of these securities or passed upon the accuracy or adequacy of this prospectus. Any representation to the contrary is a criminal offense.
The date of this prospectus is September 21, 2026.
TABLE OF CONTENTS
i
ABOUT THIS PROSPECTUS
This prospectus is part of a registration statement on Form S-1 that we filed with the Securities and Exchange Commission (the “SEC”) using the “shelf” registration process. Under this shelf registration process, the Selling Securityholders may, from time to time, sell the securities offered by them described in this prospectus. We will not receive any proceeds from the sale by such Selling Securityholders of the securities offered by them described in this prospectus. We may also use the shelf registration statement to issue (i) up to 11,887,403 shares of our Class A common stock, $0.0001 par value (the “Presidio Class A Common Stock”) that may be issued upon the exercise of 11,666,571 warrants to purchase Presidio Class A Common Stock at an exercise price of $11.50 per share (the “Public Warrants”) and (ii) up to 220,832 shares of Presidio Class A Common Stock that may be issued upon the exercise of 220,832 warrants to purchase Presidio Class A Common Stock at an exercise price of $11.50 per share (the “Private Placement Warrants” and, together with the Public Warrants, the “Presidio Warrants”). We may receive proceeds from the exercise of the Presidio Warrants to the extent any Presidio Warrants are exercised for cash.
Neither we nor the Selling Securityholders have authorized anyone to provide you with any information or to make any representations other than those contained in this prospectus or any applicable prospectus supplement or any free writing prospectuses prepared by or on behalf of us or to which we have referred you. Neither we nor the Selling Securityholders take responsibility for, and can provide no assurance as to the reliability of, any other information that others may give you. Neither we nor the Selling Securityholders will make an offer to sell these securities in any jurisdiction where the offer or sale is not permitted. You should not assume that the information in this prospectus is accurate as of any date other than the date of this prospectus. Since the date of this prospectus, our business, financial condition, results of operation and prospects may have changed.
We may also provide a prospectus supplement or post-effective amendment to the registration statement to add information to, or update or change information contained in, this prospectus. You should read both this prospectus and any applicable prospectus supplement or post-effective amendment to the registration statement together with the additional information to which we refer you in the sections of this prospectus entitled “Where You Can Find More Information; Incorporation By Reference.”
ii
GLOSSARY OF OIL AND GAS TERMS
Unless otherwise stated in this prospectus or the context otherwise requires, references to:
| ● | “basin” means a geographic area containing specific geologic intervals. |
| ● | “Bbl” means one stock tank barrel, of 42 U.S. gallons liquid volume, used herein in reference to crude oil, condensate or NGL. |
| ● | “Boe” means one barrel of oil equivalent, converting natural gas to oil at the ratio of 6 Mcf of natural gas to one Bbl of oil. |
| ● | “Btu” means the quantity of heat required to raise the temperature of one pound of water by one degree Fahrenheit. |
| ● | “completion” means the process of treating a drilled well followed by the installation of permanent equipment for the production of natural gas or oil, or in the case of a dry hole, the reporting of abandonment to the appropriate agency. |
| ● | “development well” means a well drilled within the proved area of an oil or natural gas reservoir to the depth of a stratigraphic horizon known to be productive. |
| ● | “dry hole” means a well found to be incapable of producing hydrocarbons in sufficient quantities such that proceeds from the sale of such production exceed production expenses and taxes. |
| ● | “exploratory well” means a well drilled to find a new field or to find a new reservoir in a field previously found to be productive of oil or gas in another reservoir. Generally, an exploratory well is any well that is not a development well, an extension well, a service well, or a stratigraphic test well as those items are defined under Regulation S-X. |
| ● | “field” means an area consisting of a single reservoir or multiple reservoirs all grouped on, or related to, the same individual geological structural feature or stratigraphic condition. The field name refers to the surface area, although it may refer to both the surface and the underground productive formations. For a complete definition of field, refer to Regulation S-X, Rule 4-10(a)(15). |
| ● | “formation” means a layer of rock which has distinct characteristics that differs from nearby rock. |
| ● | “fracturing” means the technique of improving a well’s production or injection rates by pumping a mixture of fluids into the formation and rupturing the rock, creating an artificial channel. As part of this technique, sand or other material may also be injected into the formation to keep the channel open, so that fluids or natural gases may more easily flow through the formation. |
| ● | “gross wells” means the total acres or wells, as the case may be, in which a working interest is owned. |
| ● | “held by production” means acreage covered by a mineral lease that perpetuates a company’s right to operate a property as long as the property is capable of producing a minimum paying quantity of oil or gas. |
| ● | “Henry Hub” means the distribution hub on the natural gas pipeline system in Erath, Louisiana, owned by Sabine Pipe Line LLC. |
| ● | “injection wells” means wells in which fluids are injected rather than produced, the primary objective typically being to maintain reservoir pressure. |
| ● | “lease operating expense” or “LOE” means the expenses of lifting oil or natural gas from a producing formation to the surface, constituting part of the current operating expenses of a working interest, and also including labor, superintendence, supplies, repairs, short-lived assets, maintenance, allocated overhead costs, workover, insurance and other expenses incidental to production, but excluding lease acquisition or drilling or completion expenses. |
| ● | “LNG” means liquefied natural gas. |
iii
| ● | “MBbl” means one thousand barrels of crude oil, condensate or NGLs. |
| ● | “MBoe/d” means one thousand Boe per day. |
| ● | “MBoe” means one thousand Boe. |
| ● | “Mcf” means one thousand cubic feet of natural gas. |
| ● | “MMBoe” means one million Boe. |
| ● | “MMBtu” means one million Btu. |
| ● | “MMcf” means one million cubic feet of natural gas. |
| ● | “net acres” means the percentage of total acres an owner has out of a particular number of acres. An owner who has 50% interest in 100 acres owns 50 net acres. |
| ● | “NGL” or “NGLs” means hydrocarbons found in natural gas which may be extracted as liquefied petroleum gas and natural gasoline. |
| ● | “NYMEX” means the New York Mercantile Exchange. |
| ● | “OPEC+” means Organization of the Petroleum Exporting Countries and its allies. |
| ● | “probable reserves” means those additional reserves that are less certain to be recovered than proved reserves but which, together with proved reserves, are as likely as not to be recovered. When deterministic methods are used, it is as likely as not that actual remaining quantities recovered will exceed the sum of estimated proved plus probable reserves. When probabilistic methods are used, there should be at least a 50% probability that the actual quantities recovered will equal or exceed the proved plus probable reserves estimates. Probable reserves may be assigned to areas of a reservoir adjacent to proved reserves where data control or interpretations of available data are less certain, even if the interpreted reservoir continuity of structure or productivity does not meet the reasonable certainty criterion. Probable reserves may be assigned to areas that are structurally higher than the proved area if these areas are in communication with the proved reservoir. Probable reserves estimates also include potential incremental quantities associated with a greater percentage recovery of the hydrocarbons in place than assumed for proved reserves. |
| ● | “productive well” means a well that is found to be capable of producing hydrocarbons in sufficient quantities such that proceeds from the sale of the production exceed production expenses and taxes. |
| ● | “proved developed non-producing” or “PDNP” means reserves that can be expected to be recovered through existing wells with existing equipment and operating methods but are not yet producing. |
| ● | “proved developed producing reserves” or “PDP” means reserves that can be expected to be recovered through existing wells with existing equipment and operating methods, according to the SEC’s or Society of Petroleum Engineers’ definitions of proved reserves. |
| ● | “proved properties” or “proved oil and natural gas properties” means properties with proved reserves. |
| ● | “proved reserves” or “proved oil and gas reserves” means those quantities of oil and natural gas, which, by analysis of geoscience and engineering data, can be estimated with reasonable certainty to be economically producible from a given date forward from known reservoirs under existing economic conditions, operating methods and government regulations prior to the time at which contracts providing the right to operate expire, unless evidence indicates that renewal is reasonably certain. The project to extract the hydrocarbons must have commenced or the operator must be reasonably certain that it will commence the project within a reasonable time. For a complete definition of proved crude oil and natural gas reserves, refer to Regulation S-X, Rule 4-10(a)(22). |
iv
| ● | “proved undeveloped reserves” or “PUDs” means proved reserves that are expected to be recovered from new wells on undrilled acreage or from existing wells where a relatively major expenditure is required for recompletion. Undrilled locations can be classified as having proved undeveloped reserves only if a development plan has been adopted indicating that such locations are scheduled to be drilled within five years unless specific circumstances justify a longer time. |
| ● | “PV-10” means the estimated future gross revenue to be generated from the production of proved reserves, net of estimated production and future development and abandonment costs, using prices and costs in effect at the determination date, before income taxes, and without giving effect to non-property related expenses, discounted to a present value using an annual discount rate of 10%. |
| ● | “recompletion” means the process of re-entering an existing wellbore that is either producing or not producing and completing reservoirs in an attempt to establish or increase existing production. |
| ● | “reserves” means estimated remaining quantities of oil and gas and related substances anticipated to be economically producible, as of a given date, by application of development projects to known accumulations. In addition, there must exist, or there must be a reasonable expectation that there will exist, the legal right to produce or a revenue interest in the production, installed means of delivering oil and gas or related substances to market, and all permits and financing required to implement the project. |
| ● | “reservoir” means a porous and permeable underground formation containing a natural accumulation of producible oil and/or natural gas that is confined by impermeable rock or water barriers and is individual and separate from other reservoirs. |
| ● | “salt water disposal wells” means a disposal site for water produced as a result of the oil and gas extraction process. |
| ● | “SEC pricing” means the oil and gas price parameters established by current SEC guidelines, including the use of an average effective price, calculated as prices equal to the 12-month unweighted arithmetic average of the first day of the month prices for each of the preceding 12 months as adjusted for location and quality differentials, unless prices are defined by contractual arrangements, excluding escalations based on future conditions. |
| ● | “standardized measure” means our standardized measure of discounted future net cash flows, which is prepared using assumptions required by the SEC. Such assumptions include the use of 12-month average prices for oil and gas, based on the first-day-of-the-month price for each month in the period, and year end costs for estimated future development and production expenditures to produce year-end estimated proved reserves. Discounted future net cash flows are calculated using a 10% rate. No provision is included for federal income taxes since our future net cash flows are not subject to taxation. However, our operations are subject to the Texas franchise tax. Estimated well abandonment costs, net of salvage values, are deducted from the standardized measure using year-end costs and discounted at the 10% rate. The standardized measure does not represent management’s estimate of our future cash flows or the value of proved oil and natural gas reserves. Probable and possible reserves, which may become proved in the future, are excluded from the calculations. Furthermore, prices used to determine the standardized measure are influenced by supply and demand as affected by recent economic conditions as well as other factors and may not be the most representative in estimating future revenues or reserve data. |
| ● | “undeveloped acreage” means lease acreage on which wells have not been drilled or completed to a point that would permit the production of commercial quantities of oil and natural gas, regardless of whether such acreage contains proved reserves. |
| ● | “unproved properties” or “unproved oil and natural gas properties” means properties without proved reserves. |
| ● | “wellbore” means the hole drilled by the bit that is equipped for oil and natural gas production on a completed well. Also called well or borehole. |
| ● | “working interest” means the right granted to the lessee of a property to explore for and to produce and own oil and natural gas or other minerals. The working interest owners bear the exploration, development, and operating costs on either a cash, penalty, or carried basis. |
| ● | “workover” means operations on a producing well to restore or increase production. |
| ● | “WTI” means West Texas Intermediate. |
v
SELECTED DEFINITIONS
Unless otherwise stated in this prospectus or the context otherwise requires, references to:
| ● | “ABS II Notes” means the term asset-based securities issued by PIH on July 18, 2023, consisting of $190.0 million aggregate principal amount of 7.806% Class A-1 Notes due December 25, 2038 and $190.0 million aggregate principal amount of 8.418% Class A-2 Notes due December 25, 2038. |
| ● | “ABS III Notes” means the fixed-rate asset-backed securities issued by Presidio Finance, LLC, consisting of $350.0 million aggregate principal amount of 7.806% Class A-1 Notes due 2041 and $175.0 million aggregate principal amount of 6.717% Class A-2 Notes due 2041. |
| ● | “Business Combination Agreement” means that certain Business Combination Agreement, dated August 5, 2025, by and among EQV, Presidio, EQV Merger Sub, Prometheus Holdings, Presidio Merger Sub and PIH, as amended, supplemented or otherwise modified from time to time in accordance with its terms. |
| ● | “Business Combination” means the closing of the transactions contemplated by the Business Combination Agreement. |
| ● | “Bylaws” means the amended and restated bylaws of Presidio. |
| ● | “Certificate of Incorporation” means the amended and restated certificate of incorporation of Presidio. | |
| ● | “Cibolo Loan” means that certain Note Purchase Agreement, dated December 13, 2023, by and among EQVR, EQVR Intermediate, Cibolo EQV LLC, and each other holder from time to time party thereto, and Cibolo Energy Partners, LLC. |
| ● | “Class B Contribution” means the Sponsor’s contribution at Closing of 1,127,963 Class B Shares to EQV in exchange for Presidio’s issuance of 562,746 shares of Presidio Class A Common Stock (or securities convertible into Presidio Class A Common Stock) to the PIH Rollover Holders and Presidio’s issuance of 565,217 shares of Presidio Class A Common Stock to certain PIPE Investors in connection with the Securities Contribution and Transfer Agreements. |
| ● | “Closing” means the closing of the transactions contemplated by the Purchase and Sale Agreements. |
| ● | “Domestication” means the transfer by way of continuation by way of the deregistration of EQV from the Cayman Islands and the continuation and domestication as a corporation registered in the State of Delaware. |
| ● | “DRIP Shares” means the 3,702,323 EQV Class B Shares (which were exchanged for shares of Presidio Class A Common Stock in connection with the Closing) held by the Sponsor that are subject to time vesting during the first three years following the Closing pursuant to a dividend reinvestment program. |
| ● | “Earn-Out Shares” means the 1,851,161 EQV Class B Shares (which were exchanged for shares of Presidio Class A Common Stock in connection with the Closing) held by the Sponsor that are subject to vesting (or forfeiture) on the basis of achieving certain trading price thresholds during the first five years following the Closing. |
| ● | “EQV” means Presidio MidCo Inc., a Delaware corporation (formerly known as EQV Ventures Acquisition Corp., a Cayman Islands exempted company). |
| ● | “EQV Board” means EQV’s board of directors. |
| ● | “EQV Class A Common Stock” means Class A common stock, $0.0001 par value, of EQV. |
| ● | “EQV Class A Shares” means the Class A ordinary shares, $0.0001 par value in the capital of EQV, which automatically converted, on a one-for-one basis, into shares of Presidio Class A Common Stock in connection with the Domestication. |
| ● | “EQV Class B Shares” means the Class B ordinary shares, $0.0001 par value in the capital of EQV, which automatically converted, on a one-for-one basis, into shares of Presidio Class A Common Stock in connection with the Domestication. |
| ● | “EQV Group” refers to EQV Resources Partners LLC, EQV Operating LLC, Peachtree OG LLC and their direct and indirect subsidiaries, including investment vehicles and funds managed and/or operated by affiliates of EQV Resources Partners LLC and EQV Operating LLC and their respective portfolio companies. |
vi
| ● | “EQV Merger Sub” means Prometheus PubCo Merger Sub Inc., a Delaware corporation and, prior to the Closing, a wholly owned subsidiary of Presidio, which merged with and into EQV in connection with the Closing. |
| ● | “EQV public shares” means the 35,000,000 EQV Class A Shares that were issued as part of the Public Units in the SPAC IPO, which were converted to 1,418,460 shares of Presidio Class A Common Stock in connection with the Closing, after giving effect to redemptions. |
| ● | “EQV Public Units” means the units of EQV, each unit representing one EQV Class A Share and one-third of one EQV public warrant to acquire one Class A Share, that were offered and sold by EQV in its initial public offering and that were cancelled in connection with the Closing in exchange for shares of Presidio Class A Common Stock, for the EQV Class A Shares, and Private Placement Warrants, for the EQV private placement warrants. |
| ● | “EQV Surviving Subsidiary” means the wholly owned subsidiary of Presidio that resulted from the merger of EQV Merger Sub with and into EQV, with EQV surviving. |
| ● | “EQV Surviving Subsidiary Common Shares” means the common shares of EQV Surviving Subsidiary. |
| ● | “EQV shareholders” means the former holders of EQV Class A Shares and holders of EQV Class B Shares. |
| ● | “EQV warrants” means the EQV private placement warrants and the EQV public warrants. |
| ● | “EQVR” means EQV Resources LLC, a Delaware limited liability company. |
| ● | “EQVR Acquisition” means the acquisition by Presidio of all of the issued and outstanding equity interests of EQVR via merger following the Closing. |
| ● | “EQVR Intermediate” means EQV Resources Intermediate LLC, a Delaware limited liability company. |
| ● | “EQVR Merger Agreement” means the Agreement and Plan of Merger, dated as of August 5, 2025, by and among EQV, Presidio, EQVR Merger Sub, EQVR, EQVR Intermediate and PIH, solely for the limited purposes set forth therein. |
| ● | “EQVR Merger Sub” means EQVR Merger Sub LLC, a Delaware limited liability company and, prior to the Closing, a direct wholly owned subsidiary of Presidio, which merged with and into EQVR in connection with the Closing. |
| ● | “Incentive Plan” means the Presidio Production Company 2026 Equity Incentive Plan. |
| ● | “LLC Interests” means the limited liability company interests of Prometheus Holdings. |
| ● | “Merger” means the merger of EQV Merger Sub with and into EQV, with EQV surviving and becoming a wholly owned direct subsidiary of Presidio and with EQV shareholders receiving one share of Presidio Class A Common Stock for each share of EQV Class A Common Stock held by such shareholder, pursuant to the Business Combination Agreement. |
| ● | “NYSE” means the New York Stock Exchange. |
| ● | “PIH” means Presidio Investment Holdings LLC, a Delaware limited liability company. |
| ● | “PIH Rollover Holder” means certain investors and certain unitholders of PIH that were party to a Rollover Agreement. |
| ● | “PIPE Financing” means the transactions contemplated by the Subscription Agreements, pursuant to which the PIPE Investors subscribed for and purchased, and EQV and Presidio issued and sold to the PIPE Investors, an aggregate of 8,750,000 shares of Presidio Class A Common Stock following the Domestication for a purchase price of $10.00 per share, on the terms set forth therein, which purchase and sale was consummated immediately prior to the Business Combination. | |
| ● | “Presidio” means Presidio Production Company. |
vii
| ● | “Presidio Board” means the board of directors of Presidio. |
| ● | “Presidio Class A Common Stock” means the Class A common stock, par value $0.0001 per share, of Presidio. |
| ● | “Presidio Class B Common Stock” means the Class B common stock, par value $0.0001 per share, of Presidio. |
| ● | “Presidio Common Stock” means the Presidio Class A Common Stock and the Presidio Class B Common Stock together. |
| ● | “Presidio Merger Sub” means Prometheus Merger Sub LLC, a Delaware limited liability company and a direct, wholly owned subsidiary of Prometheus Holdings. |
| ● | “Presidio stockholder” means a holder of Presidio Class A Common Stock or a holder of Presidio Class B Common Stock. |
| ● | “Presidio Warrants” means the Private Placement Warrants and the Public Warrants. |
| ● | “Private Financing Agreement” means the Subscription Agreements and the Securities Purchase Agreement. |
| ● | “Private Placement Warrants” means the warrants to purchase Presidio Class A Common Stock at an exercise price of $11.50 per share that converted automatically from the EQV private placement warrants following the consummation of the Business Combination. |
| ● | “Private Placement Units” means the units of EQV, each unit representing one Class A Share and one-third of one EQV private placement warrant to acquire one Class A Share, that were offered and sold by EQV to the Sponsor in a private placement at the time of the SPAC IPO and that were cancelled in connection with the Closing in exchange for shares of Presidio Class A Common Stock, for the EQV Class A Shares, and Private Placement Warrants, for the EQV private placement warrants. |
| ● | “Prometheus Holdings” means Prometheus Holdings LLC, a Delaware limited liability company and direct, wholly owned subsidiary of EQV. |
| ● | “Prometheus Holdings Common Units” means the common units of Prometheus Holdings. |
| ● | “Prometheus Holdings Unitholder” means a holder of Prometheus Holdings Common Units. |
| ● | “Prometheus Holdings LLC Agreement” means the Amended and Restated Limited Liability Company Agreement of Prometheus Holdings that was entered into at the Closing. |
| ● | “Public Warrants” means the warrants to purchase Presidio Class A Common Stock at an exercise price of $11.50 per share that converted automatically from the EQV public warrants following the consummation of the Business Combination. |
| ● | “RBL Facility” or “Credit Agreement” means the senior secured revolving credit agreement between Presidio Borrower LLC, a wholly owned subsidiary of the Company, as borrower, Citizens Bank, N.A., as administrative agent, and the lenders from time to time party thereto. |
| ● | “Registration and Stockholders’ Rights Agreement” means that certain agreement by and among EQV, Prometheus Holdings, EQVR Intermediate, the Sponsor, certain members of Presidio’s management and certain PIH investors, entered into upon the Closing, pursuant to which certain registration and governing rights and obligations of the parties are set forth. |
| ● | “Registration Rights Parties” means EQVR Intermediate, the Sponsor and certain holders of PIH equity and certain members of Presidio’s management. |
| ● | “Rollover Agreement” means the Rollover Agreement, dated as of August 5, 2025, by and among EQV, Prometheus Holdings, PIH, certain existing investors and certain unitholders of PIH, pursuant to which the Class A ParentCo Rollover Units (as defined in the Rollover Agreement) of such PIH Rollover Holders, in accordance with the terms of the Business Combination Agreement and the Rollover Agreement, converted into the right to receive a number of Prometheus Holdings Common Units and a number of shares of Presidio Class B Common Stock at par value. |
| ● | “Reserves Engineering Group” means Presidio’s internal staff of petroleum engineers and geoscience professionals. |
| ● | “SEC” means the Securities and Exchange Commission. |
| ● | “Securities Act” means the Securities Act of 1933, as amended. |
| ● | “Securities Contribution and Transfer Agreements” means the Securities Contribution and Transfer Agreements, dated as of August 5, 2025, by and among EQV, Presidio, Sponsor, certain PIH Rollover Holders and certain PIPE Investors party thereto, pursuant to which EQV and Presidio agreed to effectuate the Class B Contribution. |
viii
| ● | “Series A Preferred Certificate of Designation” means the Certificate of Designation of Preferences, Rights and Limitations of Series A Perpetual Preferred Stock. |
| ● | “Series A Preferred Financing” means the transactions contemplated by the Series A Securities Purchase Agreement, pursuant to which, in connection with the Closing, certain Series A Preferred Investors purchased in a private placement from Presidio an aggregate of 125,000 shares of Series A Preferred Stock and 937,500 Series A Preferred Investor Warrants for a cash purchase price of $123,750,000 (net of all applicable original issue discounts). |
| ● | “Series A Preferred Investors” means the investors who participated in the Series A Preferred Financing. |
| ● | “Series A Preferred Investor Warrants” means the warrants to purchase 937,500 shares of Presidio Class A Common Stock for an exercise price of $0.01 per warrant held by certain Series A Preferred Investors. |
| ● | “Series A Preferred Stock” means the Series A Perpetual Preferred Stock of Presidio, par value $0.0001 per share, with a stated value of $1,000 per share. |
| ● | “Series A Preferred Stockholders’ Agreement” means the agreement between certain Series A Preferred Investors and Presidio entered into at the Closing. |
| ● | “Series A Securities Purchase Agreement” means the Series A Preferred Securities Purchase Agreement, dated as of August 5, 2025, by and among EQV, Presidio, PIH and the Series A Preferred Investors in connection with the Series A Preferred Financing, pursuant to which certain Series A Preferred Investors purchased shares of Series A Preferred Stock and the Series A Preferred Investor Warrants from Presidio. |
| ● | “Series B Preferred Financing” means the transactions contemplated by the Series B Securities Purchase Agreement, pursuant to which, in connection with the Closing, the Series B Preferred Investor purchased, in a private placement, from Presidio an aggregate of 27,173 shares of Series B Preferred Stock. |
| ● | “Series B Preferred Investor” means Adage Capital Partners, L.P. |
| ● | “Series B Preferred Certificate of Designation” means the Certificate of Designation of Preferences, Rights and Limitations of Series B Perpetual Participating Convertible Preferred Stock. |
| ● | “Series B Preferred Stock” means the Series B Perpetual Participating Convertible Preferred Stock of Presidio, par value $0.0001 per share. |
| ● | “Series B Securities Purchase Agreement” means the Series B Preferred Securities Purchase Agreement, dated as of February 23, 2026, by and among EQV, Presidio, PIH and Adage Capital Partners, L.P., pursuant to which, immediately prior to or substantially concurrently with the Closing, the Series B Preferred Investor purchased an aggregate of 27,173 shares of Series B Preferred Stock in a private placement from Presidio. |
| ● | “SPAC IPO” means EQV’s initial public offering that was consummated on August 8, 2024. |
| ● | “Sponsor Letter Agreement” means the letter agreement, dated August 5, 2025, by and among EQV, the Sponsor, Prometheus Holdings, PIH, Presidio and certain of EQV’s directors and officers. |
| ● | “Sponsor” means EQV Ventures Sponsor LLC, a Delaware limited liability company. |
| ● | “Subscription Agreements” means the subscription agreements, entered into by EQV, Presidio and PIPE Investors in connection with the PIPE Financing. |
| ● | “Trail Dust Loan” means the advancing term loan facility between Trail Dust LLC, a subsidiary of PIH, and SouthState Bank (formerly Independent Bank). |
| ● | “Transfer Agent” means Continental Stock Transfer & Trust Company, in its capacity as Presidio’s transfer agent (and formerly EQV’s transfer agent, as context requires). |
| ● | “Trust Account” means the trust account established at the consummation of the SPAC IPO that held the proceeds of the initial public offering. |
| ● | “Units” means the Private Placement Units and the Public Units. |
| ● | “Warehouse Loan Agreement” means the Loan and Security Agreement, dated July 1, 2026, by and among Presidio Acquisitions LLC, as borrower, Presidio Intermediate Holding Company II LLC, as guarantor, Goldman Sachs Bank USA, as administrative agent and collateral agent, and the lenders party thereto. |
ix
MARKET AND INDUSTRY DATA
The market data and certain other statistical information included in this prospectus are based on a variety of sources, including independent industry publications, government publications and other published independent sources. Some data is also based on our good faith estimates, which have been derived from management’s knowledge and experience in the industry in which we operate. Although we have not independently verified the accuracy or completeness of the third-party information included in this prospectus, based on management’s knowledge and experience, we believe that these third-party sources are reliable and that the third-party information included in this prospectus or in our estimates is accurate and complete. While we are not aware of any misstatements regarding the market, industry or similar data presented herein, such data involves risks and uncertainties and is subject to change based on various factors, including those discussed under the headings “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors” in this prospectus.
TRADEMARKS
This document contains references to trademarks, trade names and service marks belonging to other entities. Solely for convenience, trademarks, trade names and service marks referred to in this prospectus may appear without the ® or TM symbols, but such references are not intended to indicate, in any way, that the applicable licensor will not assert, to the fullest extent under applicable law, its rights to these trademarks and trade names. We do not intend our use or display of other companies’ trade names, trademarks or service marks to imply a relationship with, or endorsement or sponsorship of us by, any other companies.
x
CAUTIONARY NOTE REGARDING FORWARD-LOOKING STATEMENTS
Certain statements included in this prospectus are not historical facts but are forward-looking statements, including for the purposes of the safe harbor provisions under the United States Private Securities Litigation Reform Act of 1995. These forward-looking statements include statements, estimates, or projections about Presidio’s reserve estimates, financial condition, results of operations and earnings and outlook and prospects. In addition, any statements that refer to characterizations of future events or circumstances, including any underlying assumptions, are forward-looking statements. Forward-looking statements are typically identified by words such as “plan,” “believe,” “expect,” “anticipate,” “intend,” “outlook,” “estimate,” “forecast,” “project,” “continue,” “could,” “may,” “might,” “possible,” “potential,” “predict,” “should,” “would” and other similar words and expressions, but the absence of these words does not mean that a statement is not forward-looking.
The forward-looking statements contained in this prospectus are based on the current expectations of the management of Presidio, are inherently subject to uncertainties and changes in circumstances and their potential effects and speak only as of the date of any such statement. There can be no assurance that future developments will be those that have been anticipated. The forward-looking statements contained in this prospectus involve a number of risks, uncertainties or other assumptions that may cause actual results or performance to be materially different from those expressed or implied by these forward-looking statements. These risks and uncertainties include, but are not limited to, those factors described in “Risk Factors” and the following:
| ● | the effect of the Business Combination, the EQVR Acquisition and the Arkoma Acquisition on the business relationships, operating results and business generally of Presidio; |
| ● | potential litigation that may be instituted against Presidio or its affiliates or their respective directors or officers related to the Business Combination or the EQVR Acquisition; |
| ● | Presidio’s ability to manage future growth effectively; |
| ● | Presidio’s ability to utilize its net operating loss and tax credit carryforwards effectively; |
| ● | the capital-intensive nature of Presidio’s business model, which may require Presidio to raise additional capital in the future; |
| ● | changes in supply and demand levels for oil, natural gas, and natural gas liquids, and the resulting impact on the price for those commodities and the results of operations of Presidio; |
| ● | significant declines in prices for oil, natural gas, or natural gas liquids, which could (among other things) require downward adjustments to proved reserves and significant impairment charges; |
| ● | changes in safety, health, environmental, tax, and other regulations or requirements (including those addressing air emissions, water management, or the impact of global climate change); |
| ● | the possibility of damage to Presidio’s properties as a result of natural disasters; |
xi
| ● | Presidio’s ability to comply with all applicable laws and regulations; |
| ● | the impact of public perception of fossil fuel derived energy on Presidio’s business; |
| ● | any political or other disruptions in oil producing nations; |
| ● | Presidio’s ability to meet stock exchange listing standards; |
| ● | the impact of macroeconomic events, such as inflation, recessions or depressions and, wars or fears of war; |
| ● | Presidio’s ability to pay dividends; |
| ● | Presidio’s ability to replace the reserves through acquisitions; |
| ● | Presidio’s hedging strategy and results; |
| ● | the timing and amount of Presidio’s future production of oil, NGLs and natural gas; and |
| ● | Presidio’s decline rates of its oil and gas properties. |
Reserve engineering is a method of estimating underground accumulations of crude oil, natural gas or NGLs that cannot be measured in an exact way. Crude oil, natural gas and NGL reserve engineering is not an exact science and requires subjective estimates of underground accumulations of crude oil, natural gas and NGLs and assumptions concerning future crude oil, natural gas and NGL prices, production levels, ultimate recoveries and operating and development costs. The accuracy of any reserve estimate depends on the quality of available data, the interpretation of such data and price and cost assumptions made by reserve engineers. In addition, the results of drilling, testing and production activities may justify revisions of previous estimates. As a result, estimated quantities of proved reserves, projections of future production rates and the timing of development expenditures may turn out to be incorrect.
Should one or more of these risks or uncertainties materialize, or should any of the assumptions made by the management of Presidio prove incorrect, actual results may vary in material respects from those projected in the forward-looking statements contained in this prospectus. Accordingly, you should not place undue reliance on these forward-looking statements in making an investment decision regarding our securities.
Except to the extent required by applicable law or regulation, Presidio disclaims any obligation to update the forward-looking statements contained herein to reflect events or circumstances after the date of this prospectus or to reflect the occurrence of unanticipated events.
xii
PROSPECTUS SUMMARY
This summary highlights selected information from this prospectus and does not contain all of the information that is important to you in making an investment decision. You should read this entire prospectus carefully, including the information under the headings “Risk Factors,” “Cautionary Note Regarding Forward-Looking Statements” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and the financial statements and the notes to those financial statements appearing elsewhere in this prospectus.
Unless the context otherwise requires, references to “Presidio”, the “Company”, “we”, “us”, or “our” refer to Presidio Production Company.
This prospectus includes certain terms commonly used in the oil and natural gas industry, which are defined elsewhere in this prospectus in the section titled “Glossary of Oil and Gas Terms.”
Business Overview
Presidio is an independent energy company headquartered in Texas. Operations are primarily focused on oil and gas exploration and production across the Western Anadarko Basin of Texas, Oklahoma, and Kansas. Its strategy is centered on acquiring existing producing assets and applying engineering expertise to enhance performance and extend asset life. Led by Will Ulrich and Chris Hammack, the management team brings extensive operational and industry experience. Drawing on this expertise, Presidio creates sustainable value by investing in long-lived reserves, reducing emissions, improving asset integrity, and generating consistent, hedged-protected cash flow.
Presidio’s business model is built on three core pillars:
| ● | Acquisition — Presidio evaluates and acquires existing long-lived, stable assets that produce predictable and stable cash flows, are value accretive, and are strategically complementary. |
| ● | Optimization — Presidio increases operational efficiency by leveraging technology, synergies and its access to attractive proved developed producing financing to optimize its acquired assets. |
| ● | Production — Presidio increases production to create stable, predictable cash flows to be used for future acquisitions, dividends to our shareholders and debt reduction. |
Presidio will not receive any proceeds from the sale of Presidio Class A Common Stock to be offered by the Selling Securityholders pursuant to this prospectus. However, Presidio may receive proceeds from the exercise of the Presidio Warrants or the Series A Preferred Investor Warrants to the extent any such warrants are exercised for cash.
Overview of the Assets of Presidio
Presidio holds approximately 2,158 net operated and non-operated proved developed producing wells located throughout Texas, Oklahoma, and Kansas, including the wells acquired with the EQVR Acquisition and the Arkoma Acquisition. Presidio’s average net daily production was approximately 22.6 MBoe/d, 19.4 MBoe/d, and 21.1 MBoe/d for the successor period from March 4, 2026 to June 30, 2026, and for the predecessor periods from January 1, 2026 to March 3, 2026 and for the year ended December 31, 2025, respectively. These wells are located in the Anadarko and Arkoma Basins, which have a more predictable production profile compared to less mature basins. Within Presidio’s large and diversified proved developed producing base, no single well accounts for more than 1.06% of Presidio’s proved developed producing PV-10.
Presidio’s Corporate History
Presidio Production Company is a Delaware corporation, incorporated in Delaware on July 30, 2025. Presidio was initially formed in Delaware as Prometheus PubCo Inc., was subsequently renamed to Presidio PubCo Inc. and was subsequently renamed to Presidio Production Company as part of the Business Combination that occurred on March 4, 2026.
Presidio’s principal executive office is located at 500 West 7th Street, Suite 1500, Fort Worth, Texas 76102. Presidio’s corporate website address is https://bypresidio.com/. Presidio’s website and the information contained on, or that can be accessed through, the website is not deemed to be incorporated by reference in, and is not considered part of, this prospectus. Presidio’s telephone number is (800) 461-1604.
1
Presidio Organizational Structure
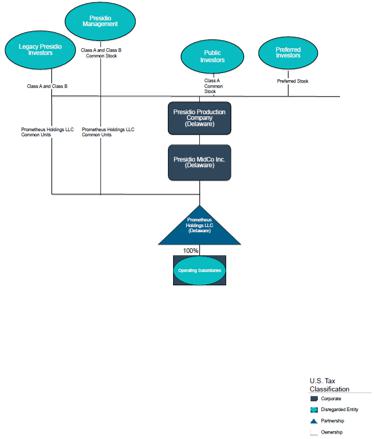
The following simplified diagram illustrates the ownership structure of Presidio as of September 18, 2026:
Up-C Structure and Exchange Rights
Our corporate structure is commonly referred to as an “Up-C” structure in which we are a publicly traded holding company and, through our subsidiaries, hold equity interests in Prometheus Holdings, which, in turn, directly owns 100% of the equity interests in PIH and EQVR. Holders of Prometheus Holdings Common Units (other than us) generally have the right, subject to the terms of the Prometheus Holdings LLC Agreement, to exchange their Prometheus Holdings Common Units together with a corresponding share of Presidio Class B Common Stock for, at our option, (i) one share of Presidio Class A Common Stock for each unit exchanged (subject to customary adjustments) or (ii) a corresponding amount of cash, with the determination to settle in cash or shares made by our independent directors.
Emerging Growth Company
Presidio is an “emerging growth company,” as defined in Section 2(a) of the Securities Act, as modified by the Jumpstart Our Business Startups Act of 2012 (the “JOBS Act”), and it may take advantage of certain exemptions from various reporting requirements that are applicable to other public companies that are not emerging growth companies, including, but not limited to, not being required to comply with the auditor attestation requirements of Section 404 of the Sarbanes-Oxley Act of 2002 (the “Sarbanes-Oxley Act”), reduced disclosure obligations regarding executive compensation in our periodic reports and proxy statements, and exemptions from the requirements of holding a nonbinding advisory vote on executive compensation and stockholder approval of any golden parachute payments not previously approved.
Further, Section 102(b)(1) of the JOBS Act exempts emerging growth companies from being required to comply with new or revised financial accounting standards until private companies (that is, those that have not had a Securities Act registration statement declared effective or do not have a class of securities registered under the Exchange Act) are required to comply with the new or revised financial accounting standards. The JOBS Act provides that a company can elect to opt out of the extended transition period and comply with the requirements that apply to non-emerging growth companies but any such election to opt out is irrevocable. Presidio has elected not to opt out of such extended transition period, which means that when a standard is issued or revised and it has different application dates for public or private companies, Presidio, as an emerging growth company, can adopt the new or revised standard at the time private companies adopt the new or revised standard. This may make comparison of Presidio’s financial statements with certain other public companies difficult or impossible because of the potential differences in accounting standards used.
2
We will remain an emerging growth company until the earlier of: (i) the last day of the fiscal year (a) following August 8, 2029, (b) in which we have total annual gross revenue of at least $1.235 billion, or (c) in which we are deemed to be a large accelerated filer, which means the market value of our common equity that is held by non-affiliates exceeds $700 million as of the last business day of its most recently completed second fiscal quarter; and (ii) the date on which we have issued more than $1 billion in non-convertible debt securities during the prior three-year period.
Smaller Reporting Company
Additionally, Presidio is a “smaller reporting company” as defined in Item 10(f)(1) of Regulation S-K. Smaller reporting companies may take advantage of certain reduced disclosure obligations, including, among other things, providing only two years of audited financial statements. We will remain a smaller reporting company until the last day of the fiscal year in which (i) the market value of our Common Stock held by non-affiliates exceeds $250 million as of the prior June 30, or (ii) our annual revenue exceeded $100 million during such completed fiscal year and the market value of our Common Stock held by non-affiliates exceeds $700 million as of the prior June 30.
Recent Developments
Arkoma Acquisition
On May 7, 2026 (the “Closing Date”), the Company entered into certain purchase and sale agreements (the “Purchase and Sale Agreements”), by and between the Company and each of Canyon Creek Energy – Arkoma, LLC (“Canyon Creek”), Alchemist Energy LeaseCo, LP (“Alchemist”), Pivotal Arkoma Basin II, LLC (“Pivotal”), East Dennis Oil Company, LLC (“East Dennis”), Harvard Petroleum Company, LLC (“Harvard”), FBF Energy, LLC (“FBF”), Harbor Island, LLC (“Harbor,” and collectively, the “Seller Parties”) and the Company. On July 1, 2026, the Company acquired the properties and assets from the Seller Parties (other than Harbor) and on July 21, 2026, the Company acquired the properties and assets from Harbor, in each case as set forth in the Purchase and Sale Agreements.
Pursuant to each Purchase and Sale Agreement, the Company purchased oil and gas leases, oil, gas, and mineral leases and subleases, carried interests, operating rights, record title interests, overriding royalty interests and other interests to the crude oil, gas, casinghead gas, condensate, natural gas liquids, and other gaseous or liquid hydrocarbons (including ethane, propane, iso-butane, nor-butane, gasoline, and scrubber liquids) of any type and chemical composition in, on, under, and that may be produced from or are otherwise attributable to certain properties in Oklahoma.
In connection with the closing of the Purchase and Sale Agreements, the Company (i) paid to the Seller Parties aggregate cash consideration of approximately $53.1 million and (ii) issued to the Seller Parties an aggregate of 1,962,240 shares (the “Stock Consideration”) of Presidio Class A Common Stock.
ABS Warehouse
On July 1, 2026, (a) Presidio Acquisitions LLC, as borrower (the “Borrower”), and Presidio Intermediate Holding Company II LLC, as a guarantor (“PIHC II”), each a wholly owned indirect subsidiary of the Company, entered into a Loan and Security Agreement (the “Warehouse Loan Agreement”) with Goldman Sachs Bank USA (“GS”), as administrative agent and collateral agent, Goldman Sachs Bank USA and Citizens Bank, N.A., as joint lead arrangers, the lenders party thereto from time to time and the other loan parties party thereto and (b) in connection with the Warehouse Loan Agreement, the Company entered into a Non-Recourse Carve-Out Guarantee (the “Limited Guarantee”) in favor of GS, as collateral agent for the benefit of the secured parties.
The Warehouse Loan Agreement provides for a senior secured warehouse credit facility with aggregate commitments of up to $1.0 billion, consisting of (i) an initial $55.0 million Closing Date loan commitment and (ii) $945.0 million of delayed draw loan commitments, which may be funded during a two-year delayed draw loan availability period to finance the acquisition of additional qualifying oil and gas assets. The drawing of delayed draw loans is subject to lender approval and satisfaction of specified conditions, including (i) the consent of each of the lenders if the aggregate principal amount of loans outstanding under the Warehouse Loan Agreement would exceed $500.0 million and (ii) the consent of GS if the aggregate principal amount of loans owed to GS and its affiliates would exceed $300.0 million. Loans made on the Closing Date that are repaid may be reborrowed only as delayed draw loans, subject to the terms of the Warehouse Loan Agreement. On the Closing Date of the Warehouse Loan Agreement, the Borrower drew the full $55.0 million Closing Date loan commitment in loans.
3
The loans made on the Closing Date mature on the third anniversary of the Closing Date, and each delayed draw loan matures on the third anniversary of its funding date; provided that all delayed draw loans mature no later than the fifth anniversary of the Closing Date.
Borrowings under the Warehouse Loan Agreement may bear interest, at the Borrower’s election, at either (i) a base rate or (ii) Term SOFR plus an applicable margin. The applicable margin initially is 3.00% for Term SOFR loans and 2.00% for base rate loans and increases to (i) 4.00% for Term SOFR loans and 3.00% for base rate loans during months 13 through 24 following the funding date of such loan to the extent such loan is still outstanding and (ii) 5.00% for Term SOFR loans and 4.00% for base rate loans for any period thereafter to the extent such loan is outstanding. The Borrower may voluntarily prepay borrowings without premium or penalty, subject to customary breakage costs for certain SOFR loans. The Warehouse Loan Agreement documents also provide for certain upfront, administrative and duration fees payable by the Borrower.
The obligations under the Warehouse Loan Agreement are (i) guaranteed by PIHC II and certain present and future subsidiaries of the Borrower and (ii) secured by first-priority security interests in substantially all assets of the Borrower, PIHC II and certain present and future subsidiaries of the Borrower that become loan parties under the Warehouse Loan Agreement from time to time (including substantially all oil and gas properties and related assets of such parties) subject to customary excluded property and permitted lien exceptions.
Pursuant to the Limited Guarantee, the Company guarantees certain specified losses arising from customary non-recourse carve-out events, including, among other things, fraud, theft, willful misconduct, misapplication of collateral proceeds and certain unauthorized distributions. In addition, the Limited Guarantee provides for springing full recourse liability upon the occurrence of certain customary events, including specified voluntary bankruptcy or insolvency actions, substantive consolidation of the Borrower with another entity in certain circumstances, certain bad-faith challenges to the loan documents or collateral, certain prohibited changes of control and other customary recourse carve-out events, in each case as more fully described in the Limited Guarantee.
The Warehouse Loan Agreement contains customary affirmative and negative covenants for facilities of this type, including restrictions on the ability of the loan parties to incur additional indebtedness, create liens, make investments, dispose of assets, engage in mergers or other fundamental transactions, make restricted payments, enter into transactions with affiliates, amend material contracts and organizational documents, and enter into certain hedging arrangements, in each case subject to customary exceptions and baskets. The Warehouse Loan Agreement also requires the Borrower to maintain specified commodity and interest rate hedging arrangements and a debt service reserve account. In addition, the Warehouse Loan Agreement contains customary reporting obligations and reserve reporting requirements with respect to the Borrower’s oil and gas assets.
The Warehouse Loan Agreement includes financial maintenance covenants with respect to the Closing Date loans, including (i) a minimum debt service coverage ratio of not less than 1.10 to 1.00 and (ii) a maximum LTV Ratio (as defined in the Warehouse Loan Agreement) of not greater than 70% (which decreases to 65% after the fifth full fiscal quarter following the Closing Date). In the case of any funding of delayed draw loans, the Borrower and the applicable Lenders will establish separate thresholds for such financial covenants at the time such Delayed Draw Loans are funded.
The Warehouse Loan Agreement contains customary events of default, including payment defaults, breaches of covenants, inaccuracies of representations and warranties, cross-defaults to specified indebtedness, bankruptcy and insolvency events, invalidity of loan documents or collateral security, certain ERISA events, certain events relating to the management and operating agreements, change of control and specified judgments (each subject to thresholds and/or grace periods described in the Warehouse Loan Agreement). Upon the occurrence and continuation of an event of default, the administrative agent may, and at the direction of the requisite lenders shall, terminate the lenders’ commitments and declare all outstanding obligations immediately due and payable, and exercise remedies against the collateral.
ABS III Notes
On June 9, 2026, Presidio Finance LLC (the “ABS Issuer”), a limited-purpose, bankruptcy-remote, wholly-owned indirect subsidiary of the Company, issued in a private offering (the “ABS III Offering”) $350 million in aggregate principal amount of fixed-rate asset-backed securities, consisting of $175 million aggregate principal amount of 5.902% Class A-1 Notes due 2041 and $175 million in principal amount of 6.717% Class A-2 Notes due 2041 (collectively, the “ABS III Notes”) pursuant to Section 4(a)(2) under the Securities Act.
The ABS III Notes were issued under a Second Amended and Restated Indenture (the “2nd A&R Indenture”) and related Series 2026-1 Supplement (the “Supplement” and together with the 2nd A&R Indenture, the “Indenture”) each dated June 9, 2026, by and among the Issuer, Presidio Finance Nominee Corp. (“Finance NomCo”), and UMB Bank, N.A., as Indenture Trustee (the “Trustee”) and are guaranteed by Finance NomCo and Presidio Finance Holding Company LLC (collectively, the “Guarantors”), which are also limited-purpose, bankruptcy-remote, wholly-owned indirect subsidiaries of the Company.
The net proceeds from the Offering were used (i) to redeem in full the outstanding ABS II Notes, (ii) to pay any related premiums, fees and expenses, including accrued and unpaid interest on the ABS II Notes and the initial deposit of the liquidity reserve amount for the ABS III Notes, and (iii) for general corporate purposes.
The Class A-1 Notes have a final scheduled payment date in August 2033 and the Class A-2 Notes have a final scheduled payment date in February 2035 (each such date, with respect to the applicable Series 2026-1 Class A-1 or Class A-2 Notes, a “Final Scheduled Payment Date”).
4
The ABS III Notes are primarily secured by specific upstream producing assets in Texas and Oklahoma that previously served as collateral for the Existing Notes.
The ABS III Notes, via the Indenture and related documentation, are governed by a series of covenants and restrictions typical for such transactions, including (i) the requirement for the Issuer to maintain a specified reserve account to ensure the payment of interest, (ii) provisions for optional and mandatory prepayments and specified make-whole payments under certain conditions, (iii) covenants related to recordkeeping, access to information and similar matters, and (iv) compliance with all applicable laws and regulations.
The ABS III Notes are also subject to customary accelerated amortization events as outlined in the Indenture, which events include failure to maintain specified debt service coverage and loan to value ratios, failure to meet certain production metrics, certain management services agreement termination events, non-compliance with hedging requirements, the failure to repay or refinance the ABS III Notes by the applicable Final Scheduled Payment Date and other events of default. The ABS III Notes are also subject to a customary increase in coupon if not repaid or refinanced by the applicable Final Scheduled Payment Date.
Additionally, the ABS III Notes are subject to customary events of default, which include non-payment of required interest, principal, or other amounts due, failure to comply with covenants within specified time frames, certain bankruptcy events, breaches of specified representations and warranties, failure of security interests to be effective, and a change of control event that is not a permitted change of control.
The Business Combination
On March 4, 2026, Presidio consummated the previously announced Business Combination pursuant to the terms of the Business Combination Agreement, dated as of August 5, 2025, by and among Presidio, EQV, EQV Merger Sub, Prometheus Holdings, Presidio Merger Sub and PIH, as amended, supplemented or otherwise modified in accordance with its terms (the “Business Combination Agreement”). The Business Combination Agreement and related transactions were approved at an extraordinary general meeting of EQV’s shareholders held on February 27, 2026 (the “Extraordinary General Meeting”).
Pursuant to the Business Combination Agreement, on the Closing Date, EQV changed its jurisdiction of incorporation by deregistering as a Cayman Islands exempted company and domesticating as a corporation incorporated under the laws of the State of Delaware (the “Domestication”), upon which (i) each then issued and outstanding Class A ordinary share of EQV, par value $0.0001 per share (the “Class A Shares”), held by the public (the “Public Class A Shares”) was automatically converted, on a one-for-one basis, into a share of Class A common stock, par value $0.0001 per share, of EQV (the “Presidio Midco Class A Common Stock”), (ii) each then issued and outstanding Class B ordinary share of EQV, par value $0.0001 per share (the “Class B Shares”) was automatically converted, on a one-for-one basis, into a share of Class B common stock, par value $0.0001 per share, of EQV (the “Presidio Midco Class B Common Stock” and, together with the Presidio Midco Class A Common Stock, the “Presidio Midco Common Stock”), (iii) each then issued and outstanding warrant to purchase one Class A Share at a price of $11.50 per share (the “EQV Warrants”) held by the public (the “EQV Public Warrants”) was automatically converted, on a one-for-one basis, into a whole warrant exercisable for one share of Presidio Midco Class A Common Stock at a price of $11.50 per share (the “Presidio Midco Warrants”), (iv) each then issued and outstanding EQV unit held by the public or by EQV Ventures Sponsor LLC (the “Sponsor”) and BTIG, LLC was cancelled and each holder became entitled to receive one share of Presidio Midco Class A Common Stock and one-third of one Presidio Midco Warrant, and (v) EQV changed its name to “Presidio MidCo Inc.”
Following the Domestication, EQV Merger Sub merged with and into EQV (the “Merger”), with EQV surviving the Merger as a wholly owned subsidiary of the Company (the “EQV Surviving Subsidiary”), pursuant to which (i) each then issued and outstanding share of Presidio Midco Common Stock was automatically converted, on a one-for-one basis, into shares of Class A common stock, par value $0.0001 per share, of the Company (the “Presidio Class A Common Stock”), (ii) each then issued and outstanding Presidio Midco Warrant was automatically converted, on a one-for-one basis, into a whole warrant exercisable for one share of Presidio Class A Common Stock at a price of $11.50 per share and (iii) the Company changed its name to “Presidio Production Company” and received a managing member interest in Prometheus Holdings. Following the Merger, Presidio Merger Sub merged with and into PIH, with PIH as the surviving company, all on the terms and subject to the conditions set forth in the Business Combination Agreement and in accordance with applicable law.
5
On the Closing Date, (i) the Company contributed to EQV Surviving Subsidiary all of its assets and liabilities (excluding its interest in EQV Surviving Subsidiary), (ii) in exchange therefor, EQV Surviving Subsidiary issued to the Company (a) 27,652,068 common shares of EQV Surviving Subsidiary (“EQV Surviving Subsidiary Common Shares”), equal to the number of total shares of Presidio Class A Common Stock issued and outstanding immediately after the Closing, (b) 125,000 Class A preferred shares of EQV Surviving Subsidiary (the “EQV Surviving Subsidiary Preferred Shares”), equal to the number of shares of the Company’s Series A Perpetual Preferred Stock, par value $0.0001 per share, with a stated value of $1,000 per share (the “Series A Preferred Stock”), outstanding and (c) 11,887,469 warrants to purchase EQV Surviving Subsidiary Common Shares, equal to the number of Presidio Warrants outstanding immediately after the Closing, (iii) EQV Surviving Subsidiary then contributed to Prometheus Holdings all of its assets and liabilities (excluding its interests in Prometheus Holdings and the shares redeemed), including cash held by EQV Surviving Subsidiary, and (iv) in exchange therefor, Prometheus Holdings issued to EQV Surviving Subsidiary (a) 27,652,068 common units of Prometheus Holdings (“Prometheus Holdings Common Units”), (b) 125,000 Class A preferred units of Prometheus Holdings and (c) 11,887,469 warrants to purchase Prometheus Holdings Common Units, in each case equal to the corresponding number of Presidio securities outstanding immediately after the Closing.
Also on the Closing Date, the Company acquired all of the issued and outstanding equity interests of EQV Resources LLC, a Delaware limited liability company (“EQVR”), via merger (the “EQVR Merger”) pursuant to the Agreement and Plan of Merger, dated as of August 5, 2025, by and among EQV, the Company, EQVR Merger Sub LLC, a Delaware limited liability company and a direct wholly owned subsidiary of the Company (“EQVR Merger Sub”), EQVR, EQV Resources Intermediate LLC, a Delaware limited liability company (“EQVR Intermediate”) and PIH (the “EQVR Merger Agreement”).
Holders of Prometheus Holdings Common Units (other than the Company) have the right (an “exchange right”), subject to certain limitations, to exchange interests of the Company (each consisting of one Prometheus Holdings Common Unit and one share of Presidio Class B Common Stock, par value $0.0001 per share (the “Presidio Class B Common Stock”)) for, at the Company’s option, (i) shares of Presidio Class A Common Stock on a one-for-one basis, subject to customary adjustments, or (ii) a corresponding amount of cash, as determined by the Company’s independent directors. Such exchange rights are generally exercisable on a quarterly basis, subject to certain de minimis allowances, with additional exchanges permitted in connection with certain specified events. Exchanges involving more than a specified number of Prometheus Holdings Common Units (subject to the Company’s discretion to permit exchanges of a lower number of Company Interests) may occur at any time with advanced notice. The exchange rights are subject to certain limitations and restrictions intended to reduce the administrative burden of exchanges upon the Company and ensure that Prometheus Holdings will continue to be treated as a partnership for U.S. federal income tax purposes.
Concurrently with the execution of the Business Combination Agreement, on August 5, 2025, EQV and the Company entered into subscription agreements (each, a “Subscription Agreement”) with certain investors (the “PIPE Investors”) pursuant to which the PIPE Investors subscribed for and purchased an aggregate of 8,750,000 shares of Presidio Class A Common Stock for a purchase price of $10.00 per share (the “PIPE Financing”). At the Closing, the Company issued an aggregate of 8,750,000 shares of Presidio Class A Common Stock to the PIPE Investors.
Concurrently with the execution of the Business Combination Agreement, on August 5, 2025, EQV, the Company and PIH entered into a Series A Preferred Securities Purchase Agreement (the “Series A Securities Purchase Agreement”) with certain investors (the “Series A Preferred Investors”), pursuant to which the Series A Preferred Investors purchased in a private placement from the Company an aggregate of 125,000 shares of Series A Preferred Stock and warrants to purchase 937,500 shares of Presidio Class A Common Stock with an exercise price of $0.01 per warrant (the “Series A Preferred Investor Warrants”) for a cash purchase price of $123,750,000 (net of all applicable original issue discounts) (the “Series A Preferred Financing”). The Series A Preferred Stock has the rights, preferences, and privileges set forth in the Company’s Certificate of Designation of Preferences, Rights and Limitations of Series A Perpetual Preferred Stock (the “Series A Preferred Certificate of Designation”), and certain holders of shares of Series A Preferred Stock have certain rights pursuant to the Series A Preferred Stockholders’ Agreement. The Series A Preferred Investor Warrants have an exercise price of $0.01, subject to adjustment as provided therein, and may be exercised for cash or on a cashless basis. The Series A Preferred Investor Warrants will become exercisable in two tranches, with 50% exercisable six months following the Closing and 50% exercisable 12 months following the Closing, and have a term of exercise equal to five years from the applicable exercise date. The Company is registering the Presidio Class A Common Stock underlying the Series A Preferred Investor Warrants in the registration statement of which this prospectus forms a part.
6
In addition, subject to certain conditions, so long as any shares of Series A Preferred Stock remain outstanding, the Series A Preferred Certificate of Designation will provide holders of a majority of the then issued and outstanding shares of Series A Preferred Stock the right to elect one Series A Director (as defined therein) and, in certain circumstances, two additional Preferred Stock Directors (as defined therein).
In connection with the Business Combination, contemporaneously with the execution and delivery of the Business Combination Agreement, EQV, Prometheus Holdings, PIH, certain existing investors and certain unitholders of PIH (the “PIH Rollover Holders”) entered into rollover agreements, dated as of August 5, 2025 (each, a “Rollover Agreement”, and collectively, the “Rollover Agreements”), pursuant to which the Class A ParentCo Rollover Units (as defined in the Rollover Agreement) of such PIH Rollover Holders converted into the right to receive Prometheus Holdings Common Units and shares of Presidio Class B Common Stock at par value (the “Rollovers”). In addition, contemporaneously with the execution and delivery of the Business Combination Agreement, EQV, the Company, the Sponsor, certain PIH Rollover Holders and certain PIPE Investors entered into Securities Contribution and Transfer Agreements (the “Securities Contribution and Transfer Agreements”), pursuant to which (i) Sponsor agreed to contribute 562,746 Class B Shares to EQV as a contribution to capital at Closing and, in exchange, Presidio agreed to issue 562,746 shares of Presidio Class A Common Stock (or securities convertible into Presidio Class A Common Stock) to the PIH Rollover Holders (the “PIH Rollover Share Contributions”) and (ii) Sponsor agreed to contribute 565,217 Class B Shares to EQV as a contribution to capital at Closing and, in exchange, Presidio agreed to issue 565,217 shares of Presidio Class A Common Stock to such PIPE Investors (the “PIPE Share Contributions”).
The Public Class A Shares, EQV Public Warrants and EQV Public Units were listed on the NYSE under the symbols “FTW,” “FTW WS” and “FTW U,” respectively, and were voluntarily delisted from the NYSE on March 5, 2026, in connection with the Closing. As of the Closing Date, the Company is organized in an “Up-C” structure, such that the Company and its subsidiaries hold and operate substantially all of the assets and business of PIH, and the Company is a publicly listed holding company that holds equity interests in PIH.
Prior to the Extraordinary General Meeting, holders of 33,581,540 Public Class A Shares properly exercised their right to have their Class A Shares redeemed for a pro rata portion of the aggregate amount on deposit in the trust account holding the proceeds from EQV’s initial public offering, less permitted withdrawals and income taxes payable. As a result, such Class A Shares were redeemed for a cash price of approximately $10.63 per share for aggregate payments of approximately $357.1 million (the “public share redemptions”), resulting in approximately $15.1 million of cash remaining in the trust account.
As of the Closing Date, following the public share redemptions and the consummation of the Business Combination, the EQVR Acquisition, the PIPE Financing, the Series A Preferred Financing and the Series B Preferred Financing, there were (i) 27,652,068 shares of Presidio Class A Common Stock issued and outstanding, (ii) 125,000 shares of Series A Preferred Stock issued and outstanding, (iii) 11,666,637 Public Warrants issued and outstanding (exercisable for 11,666,637 shares of Presidio Class A Common Stock), (iv) 220,832 Private Placement Warrants issued and outstanding (exercisable for 220,832 shares of Presidio Class A Common Stock), (v) warrants to purchase 937,500 shares of Presidio Class A Common Stock with an exercise price of $0.01 per warrant issued and outstanding and (vi) 27,173 shares of the Series B Perpetual Participating Convertible Preferred Stock of Presidio, par value $0.0001 per share (the “Series B Preferred Stock”), issued and outstanding. Following the Closing on March 5, 2026, shares of Presidio Class A Common Stock and the Public Warrants began trading on the NYSE under the symbols “FTW” and “FTW WS,” respectively. As of the Closing, existing PIH members and their direct and indirect members beneficially owned approximately 23.7% of the Company’s outstanding shares of common stock and the former EQV public stockholders, EQVR Intermediate, the Sponsor and the former independent directors of EQV owned approximately 43.3% of the outstanding shares of Presidio common stock.
7
All of the shares of Presidio Class A Common Stock that may be offered by the Selling Securityholders collectively represent a substantial portion of the total outstanding shares of the Presidio Class A Common Stock, and these holders will have the ability to sell or distribute all of their shares pursuant to the registration statement of which this prospectus forms a part so long as it is available for use. Because a substantial number of shares are being registered for resale under this prospectus, the sale of these shares, or the perception that such sales may occur, could result in increased volatility or a decline in the public trading price of Presidio Class A Common Stock and could potentially impair our ability to raise capital on terms that are acceptable to us or at all.
On the Closing Date of the Business Combination, Presidio entered into the Assignment, Assumption and Amendment Agreement (the “Warrant Agreement Amendment and Assignment”), by and among Presidio, EQV and Continental Stock Transfer & Trust Company (“Continental”). The Warrant Agreement Amendment and Assignment assigned the existing Warrant Agreement, dated August 6, 2024, by and between EQV and Continental (the “Existing Warrant Agreement”) to the Company, and the Company agreed to perform all applicable obligations under such agreement.
Risk Factor Summary
Before purchasing shares of Presidio, you should carefully review and consider the risk factors discussed or referenced below and set forth under the section entitled “Risk Factors” elsewhere in this prospectus. The occurrence of one or more of the events or circumstances discussed or referenced below or in that section, alone or in combination with other events or circumstances, may have a material adverse effect on the business, cash flows, financial condition and results of operations of Presidio.
In particular, such risks include, but are not limited to, the following:
| ● | Oil, natural gas and NGL prices are volatile. Even though a significant portion of our production is hedged, extended declines in such prices have adversely affected, and could in the future adversely affect, our business, financial position, results of operations and cash flow. |
| ● | Our derivatives activities, including the failure of counterparties to meet their obligations, could adversely affect our cash flow, results of operations and financial condition. |
| ● | Our ability to make and sustain regular cash dividends on the Presidio Class A Common Stock may be limited. |
| ● | Unless we replace our produced reserves with acquired or developed new reserves, our reserves and production will decline, which would adversely affect our future cash flows, results of operations and dividends. |
| ● | We could experience periods of higher costs if commodity prices rise. These increases could reduce our profitability, cash flow and ability to complete development activities as planned. |
| ● | Our development projects and acquisitions require substantial capital expenditures. We may be unable to obtain any required capital or financing on satisfactory terms, which could lead to a decline in our production and reserves. |
| ● | Increased costs of capital could adversely affect our business. |
| ● | Our ability to obtain financing on terms acceptable to us may be limited in the future by, among other things, increases in interest rates. |
| ● | We conduct business in a highly competitive industry, making it more difficult for us to acquire properties, market natural gas, secure trained personnel and raise additional capital. |
8
| ● | Our leverage and debt service obligations, including restrictions in the related agreements, may adversely affect our financial condition, results of operations and business prospects. |
| ● | The securitizations of our limited purpose, bankruptcy remote, wholly owned subsidiaries may expose us to financing and other risks, and there can be no assurance that we will be able to access the securitization market in the future, which may require us to seek more costly financing. |
| ● | Extreme weather conditions could adversely affect our ability to conduct operations in some of the areas where our properties are located. |
| ● | An increase in the differential between the benchmark prices of oil and natural gas and the wellhead price we expect to receive for our future production could significantly reduce our cash flow and adversely affect our financial condition. |
| ● | Our estimated reserves are based on many assumptions that may prove to be inaccurate. Any material inaccuracies in these reserve estimates or underlying assumptions will materially affect the quantities and present value of our reserves. |
| ● | Our principal asset is our interest in Prometheus Holdings and, as a result, we depend on distributions from Prometheus Holdings to pay our taxes and operating expenses. Prometheus Holdings’ ability to make such distributions may be subject to various limitations and restrictions. |
| ● | The Series A Preferred Stock has rights, preferences and privileges that are senior to the Presidio Class A Common Stock and the Series B Preferred Stock. |
| ● | The exercise of outstanding warrants will increase the number of shares eligible for future resale and may adversely affect the market price of the Presidio Class A Common Stock. |
| ● | Future sales, or the perception of future sales, by Presidio or its stockholders in the public market could cause the market price for Presidio Class A Common Stock to decline. |
| ● | Presidio incurs, and will continue to incur, significant costs and devotes substantial management time as a result of operating as a public company, particularly after it is no longer an “emerging growth company.” |
| ● | We may redeem the Public Warrants at a time that is disadvantageous to the holder, which could reduce the value of such investment. |
9
THE OFFERING
| Issuer | Presidio Production Company | |
| Issuance of Presidio Class A Common Stock | ||
| Shares of Presidio Class A Common Stock that may be issued upon the exercise of all Presidio Warrants | 11,887,403 shares of Presidio Class A Common Stock | |
| Resale of Presidio Securities | ||
| Shares of Presidio Class A Common Stock offered by the Selling Securityholders | Up to 24,222,945 shares of Presidio Class A Common Stock owned by the Selling Securityholders. | |
| Shares of Presidio Class A Common Stock issued and outstanding prior to the resale of Presidio Class A Common Stock by the Selling Securityholders | 29,825,480 shares of Presidio Class A Common Stock. | |
Presidio Warrants offered by the Selling Securityholders | Up to 133,332 Presidio Warrants | |
| Use of Proceeds | We could potentially receive up to an aggregate of approximately $136.7 million from the exercise for cash of all Presidio Warrants and Series A Preferred Investor Warrants. The exercise price of the Public Warrants and the Private Placement Warrants is $11.50 per share, and the exercise price of the Series A Preferred Investor Warrants is $0.01 per share. We believe the likelihood that warrant holders will exercise their Presidio Warrants, and therefore the amount of cash proceeds that we would receive, is dependent upon the trading price of the Presidio Class A Common Stock. If the trading price for the Presidio Class A Common Stock is less than $11.50 per share, we believe holders of Presidio Warrants will be unlikely to exercise their warrants. See the section entitled “Use of Proceeds.”
We will not receive any of the proceeds from the sale of the shares of Presidio common stock or Presidio Warrants by the Selling Securityholders. | |
| Listing and Trading Symbol | The Presidio Class A Common Stock is currently listed on the New York Stock Exchange under the symbol “FTW.” The Public Warrants are currently listed on the New York Stock Exchange under the symbol “FTW WS.” | |
| Risk Factors | Any investment in the securities offered hereby is speculative and involves a high degree of risk. You should carefully consider the information set forth under “Risk Factors” and elsewhere in this prospectus. |
10
RISK FACTORS
Investing in our shares of common stock involves a high degree of risk. You should carefully consider the risks described below with all of the other information included in this prospectus before deciding to invest in our shares of common stock. Additionally, new risks may emerge at any time and we cannot predict those risks or estimate the extent to which they may affect financial performance.
If any of the following risks actually occur, our business, financial condition or results of operations could be materially adversely affected. In that case, we might not be able to pay dividends on our shares of common stock, the trading price of our shares of common stock could decline and our shareholders could lose all or part of their investment.
Risks Related to Presidio’s Business
Unless the context otherwise requires, any reference in the below sections of this prospectus to the “Company,” “we,” “us,” “our,” and “Presidio” refers to Presidio Production Company.
Oil, natural gas and NGL prices are volatile. Even though a significant portion of our production is hedged, extended declines in such prices have adversely affected, and could in the future adversely affect, our business, financial position, results of operations and cash flow.
Our revenues, operating results, cash flow and liquidity depend primarily upon the prices we receive for the natural gas, oil and NGL we sell. We require substantial expenditures to replace our natural gas, oil and NGL reserves, sustain production and fund our business plans, including our development efforts. Historically, the markets for natural gas, oil and NGL have been volatile, and they are likely to continue to be volatile. Wide fluctuations in natural gas, oil and NGL prices may result from relatively minor changes in the supply of or demand for natural gas, oil and NGL, market uncertainty and other factors that are beyond our control, including:
| ● | worldwide and regional economic conditions impacting the supply and demand for oil, natural gas and NGLs; |
| ● | political and economic conditions and events in foreign oil and natural gas producing countries, including embargoes, the military conflict involving the United States, Israel and Iran and other continued hostilities in the Middle East and other sustained military campaigns, the war in Ukraine and associated economic sanctions on Russia, conditions in South America, Central America, China and Russia, and acts of terrorism or sabotage; |
| ● | actions of the Organization of the Petroleum Exporting Countries and its allies (“OPEC+”), including the ability and willingness of the members of OPEC+ and other exporting nations to agree to and maintain oil price and production controls; |
| ● | changes in seasonal temperatures, including the number of heating degree days during winter months and cooling degree days during summer months; |
| ● | the level of oil, natural gas and NGL exploration, development and production; |
| ● | the level of oil, natural gas and NGL inventories; |
| ● | the level of U.S. Liquefied Natural Gas (“LNG”) exports; |
| ● | the impact on worldwide economic activity of an epidemic, outbreak or other public health events, |
| ● | prevailing prices on local price indexes in the areas in which we operate; |
| ● | the proximity, capacity, cost and availability of gathering and processing facilities; |
| ● | localized and global supply and demand fundamentals and transportation availability; |
| ● | the cost of exploring for, developing, producing and transporting reserves; |
| ● | the spot price of LNG on world markets; |
11
| ● | changes in ocean freight capacity, which could adversely impact LNG shipping capacity or lead to material interruptions in service or stoppages in LNG transportation; |
| ● | political and economic conditions in or affecting major LNG consumption regions or countries, particularly Asia and Europe; |
| ● | weather conditions and natural disasters, including those influenced by climate change; |
| ● | technological advances affecting energy consumption; |
| ● | the impact of energy conservation efforts; |
| ● | the price and availability of alternative fuels; |
| ● | activities that restrict the exploration, development and production of oil and natural gas to minimize greenhouse gas (“GHG”) emissions; |
| ● | speculative trading in oil and natural gas derivative contracts; |
| ● | increased end-user conservation; |
| ● | U.S. trade policies and their effect on U.S. oil and natural gas exports; |
| ● | expectations about future commodity prices; and |
| ● | U.S. federal, state and local and non-U.S. governmental regulation and taxes, including legislation or regulations addressing GHG emissions or requiring the reporting of GHG emissions or climate-related information. |
These factors and the volatility of the energy markets make it extremely difficult to predict future oil and natural gas price movements accurately. Lower commodity prices may reduce our operating margins, cash flow and borrowing ability. If we are unable to obtain needed capital or financing on satisfactory terms, our ability to make acquisitions could be adversely affected. Also, using lower prices in estimating proved and probable reserves may result in a reduction in proved and probable reserve volumes due to economic limits. In addition, sustained periods with oil and natural gas prices at levels lower than current WTI and Henry Hub strip prices may adversely affect our cash flow and our ability to raise capital. As a result, a substantial or extended decline in commodity prices may materially and adversely affect our future business, financial condition, results of operations, cash flow, liquidity and ability to meet our financial commitments or cause us to delay any planned capital expenditures.
Our derivatives activities, including the failure of counterparties to meet their obligations, could adversely affect our cash flow, results of operations and financial condition.
To achieve more predictable cash flows and reduce our exposure to adverse fluctuations in the prices of oil and natural gas, and (a) as required by our ABS III Notes and (b) as may be required by any secured reserve-based lending revolving credit facility that we may from time to time be a party to, we enter into derivative contracts in relation to a significant portion of our projected oil and natural gas production, primarily consisting of swaps. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations of the Predecessor — Quantitative and Qualitative Disclosures About Market Risk — Commodity Price Risk.” Accordingly, our earnings may fluctuate significantly as a result of changes in the fair value of our derivative instruments.
Derivative instruments also expose us to the risk of financial loss in some circumstances, including when:
| ● | production is less than the volumes covered by the derivative instruments and applicable commodity prices rise; |
| ● | the counterparty to a derivative instrument defaults on its contractual obligations; or |
| ● | references a commodity price source in respect of which prices increase more (or decrease less) than the corresponding. |
12
The use of derivatives may, in some cases, require the posting of cash collateral with counterparties. If we enter into derivatives that require us to post cash collateral and commodity prices change in a manner adverse to our position under those derivatives, our cash otherwise available for use in our operations would be reduced, which could limit our ability to make future capital expenditures, make payments on our indebtedness and pay dividends to our shareholders, and which could also limit the size of our borrowing base, under any secured reserve-based lending revolving credit facility that we may from time to time be a party to. Future collateral requirements will depend on arrangements with our counterparties and oil and natural gas prices.
During periods of declining commodity prices, our derivative contract receivable positions would generally increase, which increases our counterparty credit exposure. If the creditworthiness of our counterparties deteriorates and results in their nonperformance, we could incur a significant loss with respect to our derivative contracts.
Our price hedging strategy and future hedging transactions will be determined at our discretion, subject to the terms of certain agreements governing our indebtedness. The prices at which we hedge our production in the future will be dependent upon commodity prices at the time we enter into the hedges. Our hedges will limit our ability to realize the full benefits from commodity price increases relative to the prices at which we establish our hedges. On the other hand, any portion of our natural gas, NGL and oil production that is not hedged would expose that production to commodity price fluctuations.
Our ability to make and sustain regular cash dividends on the Presidio Class A Common Stock may be limited.
We currently expect to pay a dividend from available funds and future earnings on the Presidio Class A Common Stock, at the discretion of the Presidio Board and subject to compliance with contractual restrictions and covenants in the agreements governing our current and future indebtedness. Based on current estimates of future production from our existing reserves at current prices, we estimate that we will be unable to sustain paying dividends at our anticipated initial level for periods beyond 2027. In order to sustain our anticipated initial dividend level, if any, for periods beyond 2027, we expect we would be required to acquire additional producing reserves at favorable prices. See “— Unless we replace our produced reserves with acquired or developed new reserves, our reserves and production will decline, which would adversely affect our future cash flows, results of operations and dividends.”
Unless we replace our produced reserves with acquired or developed new reserves, our reserves and production will decline, which would adversely affect our future cash flows, results of operations and dividends.
Producing oil and natural gas reservoirs generally are characterized by declining production rates that vary depending upon reservoir characteristics and other factors. Unless we continually acquire properties containing proved reserves or conduct successful ongoing development activities, our proved reserves will decline as those reserves are produced. Our future reserves and production, and therefore our future cash flow and results of operations, are highly dependent on our success in economically finding or acquiring additional recoverable reserves and efficiently developing our current reserves. We may not be able to find, acquire or develop sufficient additional reserves to replace our current and future production. If we are unable to replace our current and future production, the value of our reserves will decrease, and our business, financial condition and results of operations would be materially and adversely affected.
We could experience periods of higher costs if commodity prices rise. These increases could reduce our profitability, cash flow and ability to complete development activities as planned.
Historically, our capital and operating costs have risen during periods of increasing oil, natural gas and NGL prices and drilling activity in our areas of operation and other major shale basins throughout the U.S. These cost increases result from a variety of factors beyond our control, such as increases in the cost of sand and other proppant used in hydraulic fracturing operations; steel and other raw materials that we and our vendors rely upon; increased demand for labor, services and materials as drilling activity increases; and increased taxes. Such costs may rise faster than increases in our revenue if commodity prices rise, thereby negatively impacting our profitability, cash flow and ability to complete development activities as scheduled and on budget. This impact is magnified to the extent that our ability to participate in the commodity price increases is limited by our hedging activities. Furthermore, high oil prices have historically led to more development activity in oil-focused shale basins and resulted in service cost inflation across all U.S. shale basins, including our areas of operation. Higher levels of development activity in oil-focused shale basins have also historically resulted in higher levels of associated gas production that places downward pressure on natural gas prices. To the extent natural gas prices decline due to a period of increased associated gas production and we experience service cost inflation during such period, our cash flow and profitability may be materially adversely impacted.
13
Our development projects and acquisitions require substantial capital expenditures. We may be unable to obtain any required capital or financing on satisfactory terms, which could lead to a decline in our production and reserves.
The oil and gas industry is capital-intensive. A number of factors could cause our cash flow to be less than we expect. Moreover, our capital budgets are based on a number of assumptions, including expected elections by working interest partners, midstream service costs, and oil and natural gas prices, and are therefore subject to change. If our cash flows are less than we expect, we decide to pursue acquisitions, or we change our capital budgets, we may be required to borrow more under the RBL Facility than we expect or issue debt or equity securities to consummate such acquisitions. The incurrence of additional indebtedness, either through borrowings under the RBL Facility, the issuance of additional debt securities or otherwise, would require that a portion of our cash flow from operations be used for the payment of interest and principal on our indebtedness, thereby reducing our ability to use cash flow from operations to fund capital expenditures, our development plan, acquisitions and dividends to shareholders. The issuance of additional equity securities may be dilutive to our shareholders. The actual amount and timing of our future capital expenditures may differ materially from our estimates as a result of, among other things: oil and natural gas prices; the availability and cost of drilling rigs and labor and other services and equipment; the availability, cost and adequacy of midstream gathering, processing, compression and transportation infrastructure; and regulatory, technological and competitive developments.
Our cash flow from operations and access to capital are subject to a number of variables, including:
| ● | the prices at which our production is sold; |
| ● | the amount of our proved reserves; |
| ● | the amount of hydrocarbons we are able to produce from existing wells; |
| ● | our ability to acquire, locate and produce new reserves; |
| ● | the amount of our operating expenses; |
| ● | cash settlements from our derivative activities; |
| ● | our ability to borrow under the RBL Facility; and |
| ● | our ability to access the debt and equity capital markets or sell non-core assets. |
If our revenues or the borrowing base under the RBL Facility decrease as a result of lower commodity prices, operational difficulties, declines in reserves or for any other reason, we may have limited ability to obtain the capital necessary to make acquisitions or sustain our operations at current levels. If additional capital is needed, we may not be able to obtain debt or equity financing on terms acceptable to us, if at all. If cash flow generated by our operations or available borrowings under the RBL Facility are insufficient to meet our capital requirements, the failure to obtain additional financing could result in a curtailment of the development of our properties, which in turn could lead to a decline in our reserves and production and could materially and adversely affect our business, financial condition and results of operations.
Increased costs of capital could adversely affect our business.
Our business could be harmed by factors such as the availability, terms and cost of capital, increases in interest rates or a reduction in our credit rating. Changes in any one or more of these factors could cause our cost of doing business to increase, limit our access to capital, limit our ability to pursue acquisition opportunities, reduce our cash flows available and place us at a competitive disadvantage. Continuing disruptions and volatility in the global financial markets may lead to an increase in interest rates or a contraction in credit availability impacting our ability to finance our activities. A significant reduction in the availability of credit could materially and adversely affect our ability to achieve our business strategy and cash flows.
14
Our ability to obtain financing on terms acceptable to us may be limited in the future by, among other things, increases in interest rates.
We require continued access to capital and our business and operating results can be harmed by factors such as the availability, terms of and cost of capital, increases in interest rates or a reduction in credit rating. We may use the RBL Facility to finance a portion of our future growth, and these factors could cause our cost of doing business to increase, limit our ability to pursue acquisition opportunities, reduce cash flow used for drilling and place us at a competitive disadvantage. Volatility in the global financial markets, significant losses in financial institutions’ U.S. energy loan portfolios, or environmental and social concerns may lead to a contraction in credit availability impacting our ability to finance our operations or our ability to refinance the RBL Facility or other outstanding indebtedness. An increase in interest rates could increase our interest expense and materially and adversely affect our financial condition. A significant reduction in cash flow from operations or the availability of credit could materially and adversely affect our ability to acquire new assets, our cash flow and operating results.
We conduct business in a highly competitive industry, making it more difficult for us to acquire properties, market natural gas, secure trained personnel and raise additional capital.
Our ability to acquire additional oil and gas properties and to find and, if applicable, develop reserves in the future will depend on our ability to evaluate and select suitable properties and to consummate transactions in a highly competitive environment for acquiring properties, marketing natural gas and securing trained personnel. Also, there is substantial competition for capital available for investment in the oil and gas industry. Many of our competitors possess and employ greater financial, technical and personnel resources than we do. Those companies may be able to pay more for oil and natural gas properties and to evaluate, bid for and purchase a greater number of properties than our financial or personnel resources permit. Those larger companies may also have a greater ability to continue development activities during periods of low oil prices and to absorb the burden of present and future federal, state, local and other laws and regulations. In addition, other companies may be able to offer better compensation packages to attract and retain qualified personnel than we are able to offer. We may not be able to compete successfully in the future in acquiring natural gas properties, developing reserves, marketing our production, attracting and retaining quality personnel and raising additional capital, any of which could have a material adverse effect on our business.
Our leverage and debt service obligations, including restrictions in the related agreements, may adversely affect our financial condition, results of operations and business prospects.
In the future, we and our subsidiaries may incur substantial additional indebtedness (including secured indebtedness and any borrowings under the RBL Facility). The RBL Facility contains restrictions on the incurrence of additional indebtedness, and these restrictions are subject to waiver and a number of significant qualifications and exceptions, and indebtedness incurred in compliance with these restrictions could be substantial. Additionally, the RBL Facility permits or will permit us to incur certain amounts of additional indebtedness.
Our level of indebtedness, if any, could affect our operations in several ways, including the following:
| ● | requiring us to dedicate a substantial portion of our cash flow from operations to service our debt, thereby reducing the cash available to finance our operating and investing activities; |
| ● | limiting management’s discretion in operating our business and our flexibility in planning for, or reacting to, changes in our business and the industry in which we operate; |
| ● | increasing our vulnerability to downturns and adverse developments in our business and industry; |
| ● | limiting our ability to make certain payments, including paying dividends in respect of our equity; |
| ● | limiting our ability to raise capital on favorable terms; |
| ● | limiting our ability to raise available financing, make investments, lease equipment, sell assets and engage in business combinations; |
| ● | making us vulnerable to increases in interest rates; |
| ● | putting us at a competitive disadvantage relative to our competitors; and |
| ● | limiting our flexibility in planning for and reacting to changes in our business, including possible acquisition opportunities, due to covenants contained in the RBL Facility, including financial covenants. |
15
Restrictions in our existing and future debt agreements could limit our growth and our ability to engage in certain activities.
The agreements governing (or that will govern) or entered into (or that will be entered into) in connection with the RBL Facility, any future secured reserve-based lending revolving credit facility that we may enter into, the ABS III Notes and/or the Warehouse Loan Agreement contain or will contain a number of significant covenants, including restrictive covenants that will, subject to certain qualifications and exceptions, limit our ability (and the ability of certain of our subsidiaries and/or affiliates) to, among other things:
| ● | make certain payments, including paying dividends in respect of our equity; |
| ● | incur additional indebtedness; |
| ● | make loans to others; |
| ● | make certain acquisitions and investments; |
| ● | merge or consolidate with another entity; |
| ● | hedge future production or interest rates; |
| ● | undertake certain transactions with our affiliates; |
| ● | incur liens; |
| ● | sell assets; and |
| ● | engage in certain other transactions. |
In addition, the RBL Facility, the advancing term loan facility between Trail Dust LLC, a subsidiary of PIH, and SouthState Bank (the “Trail Dust Loan”), any future secured reserve-based lending revolving credit facility that we may enter into, the ABS III Notes, and the Warehouse Loan Agreement require or will require us to maintain compliance with certain rolling financial covenants.
The restrictions in the agreements governing (or that will govern) or entered into (or that will be entered into) in connection with the RBL Facility, any future secured reserve-based lending revolving credit facility that we may enter into, the ABS III Notes, and the Warehouse Loan Agreement also impact our ability to obtain capital to withstand a downturn in our business or the economy in general. We may also be prevented from taking advantage of business opportunities that arise because of the limitations that the restrictive covenants under our debt arrangements may impose on us.
A breach of any covenant in the RBL Facility, the Trail Dust Loan, any future secured reserve-based lending revolving credit facility that we may enter into, the ABS III Notes, and the Warehouse Loan Agreement will result in a default under the applicable agreement and an event of default if there is no grace period or if such default is not cured during any applicable grace period. An event of default, if not waived, could result in acceleration of the indebtedness outstanding under the applicable agreement and, by extension, potentially other debt agreements to which we are a party. Any such accelerated indebtedness would become immediately due and payable, and the secured parties under any such debt arrangement would have the ability to foreclose on any collateral securing such debt. If that occurs, we may not be able to make all of the required payments or borrow sufficient funds to refinance such indebtedness. Even if new financing were available at that time, it may not be on terms that are acceptable to us.
Any significant reduction in the borrowing base under the RBL Facility or any future secured reserve-based lending revolving credit facility may negatively impact our ability to fund our operations and/or limit our growth and our ability to engage in certain activities.
The amount we may borrow under the RBL Facility is capped at the lower of the total of our bank commitments and a “borrowing base” determined from time to time by the lenders based on our oil and gas reserves, market conditions and other factors. The borrowing base is subject to, among other things, a scheduled annual and other elective and non-elective borrowing base redeterminations. Any significant reduction in our borrowing base as a result of borrowing base redeterminations or otherwise may negatively impact our liquidity and our ability to fund our operations. Further, if the outstanding borrowings under the RBL Facility were to exceed the lower of our bank commitments level and the borrowing base as a result of any such redetermination or other reasons, we would be required to repay the excess within a brief period. We may not have sufficient funds to make such repayments. If we do not have sufficient funds and we are otherwise unable to negotiate renewals of our borrowings or arrange new financing, we may have to sell significant assets. Any such sale could have a material adverse effect on our business and financial results.
16
The failure of our hedge counterparties to meet their obligations may adversely affect our financial results.
Our hedging transactions expose us to the risk that a counterparty fails to perform under a derivative contract. Any default by a counterparty to these derivative contracts when they become due could have a material adverse effect on our financial condition and results of operations.
Our ability to collect payments from the sale of oil and natural gas to our customers depends on the payment ability of our customer base, which includes several significant customers. If any one or more of our significant customers fail to pay us for any reason, we could experience a material loss. In addition, if any of our significant customers cease to purchase our oil and natural gas or reduce the volume of the oil and natural gas that they purchase from us, the loss or reduction could have a detrimental effect on our revenues and may cause a temporary interruption in sales of, or a lower price for, our oil and natural gas.
We also face credit risk through joint interest receivables. Joint interest receivables arise from billing entities who own partial working interests in the wells we operate. Though we often have the ability to withhold future revenue disbursements to recover non-payment of joint interest billings, the inability or failure of working interest holders to meet their obligations to us or their insolvency or liquidation may adversely affect our financial results.
The securitizations of our limited purpose, bankruptcy remote, wholly owned subsidiaries may expose us to financing and other risks, and there can be no assurance that we will be able to access the securitization market in the future, which may require us to seek more costly financing.
We have securitized, and we expect that we will in the future securitize, certain wellbores and their related leasehold rights and hydrocarbon production to generate cash. In such transactions, we convey such wellbores to a special purpose vehicle that, in turn, issues certain securities. The securities issued by the special purpose vehicle are collateralized by such wellbores. In exchange for the transfer of such wellbores to the special purpose vehicle, we receive the cash proceeds from the sale of the securities.
There can be no assurance that we will be able to complete additional securitizations in the future, particularly if the securitization markets become constrained. In addition, the value of any securities that we may retain in our securitizations, including securities retained to comply with applicable risk retention rules, might be reduced or, in some cases, eliminated as a result of an adverse change in economic conditions, the financial markets or credit performance. If it is not possible or economical for us to securitize our receivables in the future, we would need to seek alternative financing to support our operations and to meet our existing debt obligations, which may be less efficient and more expensive than raising capital via securitizations and may have a material adverse effect on our results of operations, financial condition, and liquidity.
Extreme weather conditions could adversely affect our ability to conduct operations in some of the areas where our properties are located.
The majority of the scientific community has concluded that climate change may result in more frequent and/or more extreme weather events, changes in temperature and precipitation patterns, changes to ground and surface water availability, and other related phenomena, which could affect some, or all, of our operations. If any such effects were to occur, they could adversely affect or delay demand for oil or natural gas products or cause us to incur significant costs in preparing for or responding to the effects of climatic events themselves, which may not be fully insured. For example, our development, optimization and exploitation activities and equipment could be adversely affected by extreme weather conditions, such as hurricanes, thunderstorms, tornadoes and snow or ice storms, or other climate-related events such as wildfires and floods, in each case which may cause a loss of operational efficiency or production from temporary cessation of activity or lost or damaged facilities and equipment. Further, these types of interruptions could result in a decrease in the volumes supplied to our gathering systems, and delays and shutdowns caused by severe weather may have a material negative impact on the continuous operations of our gathering and processing facilities, including interruptions in service. These types of interruptions could negatively impact our ability to meet our contractual obligations to our third-party customers and thereby give rise to certain termination rights or other liabilities under our contracts. Such extreme weather conditions and events could also impact other areas of our operations, including the costs of insurance, access to our drilling and production facilities for routine operations, maintenance and repairs and the availability of, and our access to, necessary resources, such as water, and third-party services, such as gathering, processing, compression and transportation services. These constraints and the resulting shortages or high costs could delay or temporarily halt our operations and materially increase our operation and capital costs, which could have a material adverse effect on our business, financial condition and results of operations. Given that our operations are concentrated exclusively in the Anadarko Basin, a number of our properties could experience any of the same weather conditions at the same time, resulting in a relatively greater impact on our results of operations than they might have on other companies that have a more geographically diversified portfolio of properties. Our ability to mitigate the adverse physical impacts of climate change depends in part upon our disaster preparedness and response and business continuity planning.
17
Our estimated reserves are based on many assumptions that may prove to be inaccurate. Any material inaccuracies in these reserve estimates or underlying assumptions will materially affect the quantities and present value of our reserves.
It is not possible to measure underground accumulation of crude oil, natural gas or NGLs in an exact way. Crude oil, natural gas and NGL reserve engineering is not an exact science and requires subjective estimates of underground accumulations of crude oil, natural gas and NGLs and assumptions concerning future crude oil, natural gas and NGL prices, production levels, ultimate recoveries and operating and development costs. As a result, estimated quantities of proved reserves, projections of future production rates and the timing of development expenditures may turn out to be incorrect. Estimates of our proved reserves and related valuations as of December 31, 2025 were prepared by CG&A. CG&A conducted a detailed review of all of our properties for the period covered by its reserve report using information provided by us. Over time, we may make material changes to reserve estimates taking into account the results of actual testing, production and changes in prices. In addition, certain assumptions regarding future crude oil, natural gas and NGL prices, production levels and operating and development costs may prove incorrect. A portion of our reserve estimates are made without the benefit of a lengthy production history, which are less reliable than estimates based on a lengthy production history. Any significant variance from these assumptions to actual figures could greatly affect our estimates of reserves and future cash generated from operations. Numerous changes over time to the assumptions on which our reserve estimates are based, as described above, often result in the actual quantities of crude oil, natural gas and NGLs that are ultimately recovered being different from our reserve estimates.
Our acquisition and divestiture strategy will subject us to certain risks associated with the inherent uncertainty in evaluating properties for which we have limited information.
We may be unable to make accretive acquisitions or may make opportunistic dispositions. Any such acquisitions, if not integrated or conducted successfully, or such dispositions, if not conducted successfully, may disrupt our business and hinder our growth potential. Our ability to grow and to pay, maintain or increase dividends to our shareholders depends in part on our ability to make acquisitions that result in positive cash flow and/or an increase in cash flow. There is intense competition for acquisition opportunities in our industry and we may not be able to identify attractive acquisition opportunities. In the future we may make acquisitions of assets or businesses that complement or expand our current business. However, there is no guarantee we will be able to identify attractive acquisition opportunities. In the event we are able to identify attractive acquisition opportunities, we may not be able to complete the acquisition or do so on commercially acceptable terms. Competition for acquisitions may also increase the cost of, or cause us to refrain from, completing acquisitions. In addition, from time to time, we may consider opportunistic dispositions, including dispositions of non-operating properties, having the potential to further limit future production.
Certain of our wells are currently shut-in, and in the future, we may continue to shut-in some or all of our producing wells depending on market conditions, storage or transportation constraints and contractual obligations. Any prolonged shut-in of our wells could result in the expiration, in whole or in part, of any related leases, which could adversely affect our reserves, business, financial condition and results of operations.
Some of our wells are currently shut-in, and thus are not currently producing, and the associated leases have limitations on the length of time they will remain valid. These wells are shut-in from time to time for maintenance, workovers, upgrades and other matters outside of our control, including repairs, adverse weather (including hurricanes, flooding and tropical storms), inability to dispose of produced water or other regulatory and market conditions. If our leases expire and we are unable to renew the leases, or our wells are otherwise shut-in due to factors outside of our control, it could adversely affect our reserves, business, financial condition and results of operations.
18
We may face unanticipated increased or incremental costs in connection with decommissioning obligations such as plugging.
In the future, we may become responsible for costs associated with abandoning and reclaiming wells. We will incur such decommissioning costs at the end of the operating life of some of our properties. The ultimate decommissioning costs are uncertain and cost estimates can vary in response to many factors including changes to relevant legal requirements, the emergence of new restoration techniques, the shortage of plugging vendors, difficult terrain or weather conditions or experience at other production sites. The expected timing and amount of expenditure can also change, for example, in response to changes in reserves, wells losing commercial viability sooner than forecasted or changes in laws and regulations or their interpretation. As a result, there could be significant adjustments to the provisions established which would affect future financial results. The use of other funds to satisfy such decommissioning costs may impair our ability to focus capital investment in other areas of our business, which could materially and adversely affect our business, results of operations, financial condition, cash flows or prospects.
New technologies may cause our current operating methods to become obsolete, and we may not be able to keep pace with technological developments in the oil and gas industry.
The oil and natural gas industry is subject to rapid and significant advancements in technology, including the introduction of new products and services using new technologies. As competitors use or develop new technologies, we may be placed at a competitive disadvantage, and competitive pressures may force us to implement new technologies at a substantial cost. In addition, competitors may have greater financial, technical and personnel resources that allow them to enjoy technological advantages, and that may in the future, allow them to implement new technologies before we can. We cannot be certain that we will be able to implement technologies on a timely basis or at a cost that is acceptable to us. If we are unable to maintain technological advancements consistent with industry standards, our business, results of operations and financial condition may be materially adversely affected.
Conservation measures, technological advances and/or a negative shift in market perception towards the oil and gas industry could reduce the demand for oil, NGLs and natural gas.
Fuel and energy conservation measures, alternative fuel requirements, increasing consumer demand for alternatives to oil and natural gas, technological advances in fuel economy and energy generation devices, and the increased competitiveness of alternative energy sources could reduce demand for oil and natural gas. Additionally, the increased competitiveness of alternative energy sources (such as electric vehicles, wind, solar, geothermal, tidal, fuel cells and biofuels) could reduce demand for oil and natural gas and, therefore, our revenues.
Additionally, certain segments of the investor community have recently expressed negative sentiment towards investing in the oil and natural gas industry. Some investors, including certain pension funds, university endowments and family foundations, have stated policies to reduce or eliminate their investments in the oil and natural gas sector based on social and environmental considerations. Furthermore, certain other stakeholders have pressured commercial and investment banks to stop funding oil and gas exploration and production and related infrastructure projects. With the continued volatility in oil and natural gas prices, and the possibility that interest rates will rise in the future, increasing the cost of borrowing, certain investors have emphasized capital efficiency and free cash flow from earnings as key drivers for energy companies, especially shale producers. This may also result in a reduction of available capital funding for potential development projects, further impacting our future financial results.
19
The impact of the changing demand for oil and natural gas services and products, together with a change in investor sentiment, may have a material adverse effect on our business, financial condition, results of operations and cash flows.
Currently, our producing properties are concentrated in the Anadarko and Arkoma Basins, making us vulnerable to risks associated with operating in a limited number of geographic areas.
As a result of our geographic concentration, adverse industry developments in our operating area could have a greater impact on our financial condition and results of operations than if we were more geographically diverse. We may also be disproportionately exposed to the impact of regional supply and demand factors, governmental regulations or midstream capacity constraints. Delays or interruptions caused by such adverse developments could have a material adverse effect on our financial condition and results of operations.
Similarly, the concentration of our assets within a small number of producing formations exposes us to risks, such as changes in field wide rules, which could adversely affect development activities or production relating to those formations. In addition, in areas where exploration and production activities are increasing, as may be the case in our operating areas, we are subject to increasing competition for workover rigs, tubulars and other well equipment, services, supplies as well as increased labor costs and a decrease in qualified personnel, which may lead to periodic shortages or delays. The curtailments arising from these and similar circumstances may last from a few days to several months or even longer, and, in many cases, we may be provided only limited, if any, notice as to when these circumstances will arise and their duration.
Oil and natural gas producers’ operations are substantially dependent on the availability of water and the disposal of waste, including water and drilling fluids. Restrictions on the ability to obtain water or dispose of waste may impact our operations.
Water is an essential component of oil and natural gas production during the drilling and production process. Our inability to locate sufficient amounts of water, or dispose of or recycle produced water could adversely impact our operations. Moreover, the imposition of new environmental initiatives and regulations could include restrictions on our ability to dispose of waste, including, but not limited to, produced water, drilling fluids and other wastes associated with the exploration, development or production of oil and natural gas. The Clean Water Act (the “CWA”) and similar state regulations impose restrictions and strict controls regarding the discharge of produced waters and other natural gas and oil waste into federal and state waters. Permits must be obtained to discharge pollutants into such waters and to conduct construction activities in such waters, which include certain wetlands. The CWA and similar state laws provide for civil, criminal and administrative penalties for any unauthorized discharges of pollutants and unauthorized discharges of reportable quantities of oil and other hazardous substances. State and federal discharge regulations prohibit the discharge of produced water and sand, drilling fluids, drill cuttings and certain other substances related to the natural gas and oil industry into coastal waters. Compliance with current and future environmental regulations, permit requirements and judicial and agency opinions or orders governing the withdrawal, storage and use of surface water or groundwater necessary for the disposal and recycling of produced water, drilling fluids and other wastes may increase our operating costs and cause delays, interruptions or termination of our operations, the extent of which cannot be predicted. In addition, in some instances, the operation of underground injection wells for the disposal of waste has been alleged to cause earthquakes. In some jurisdictions, such issues have led to orders prohibiting continued injection or the suspension of drilling in certain wells identified as possible sources of seismic activity or resulted in stricter regulatory requirements relating to the location and operation of underground injection wells. Any orders or regulations addressing concerns about seismic activity from well injection in jurisdictions where we operate could affect our operations.
20
We have historically relied on third-party “farm-ins” and similar arrangements for the development of our undeveloped reserves. The development of our undeveloped reserves may take longer and may require higher levels of capital expenditures than we or such third-parties currently anticipate. Therefore, our undeveloped reserves may not be ultimately developed or produced.
As of December 31, 2025, none of our total estimated proved reserves were classified as PUDs using SEC pricing. Development of any undeveloped reserves the Company may acquire in the future may take longer and require high levels of capital expenditures. Our ability to fund these expenditures will be subject to a number of risks. Delays in the development of future PUDs, increases in costs to drill and develop such reserves or decreases in commodity prices will reduce the PV-10 value of our estimated PUDs and future net cash flows estimated for such reserves and may result in some projects becoming uneconomic. In addition, delays in the development of reserves could cause us to have to reclassify some of our PUDs as unproved reserves. Furthermore, there is no certainty that we will be able to convert future undeveloped reserves to developed reserves or that our PUDs will be economically viable or technically feasible to produce.
Further, SEC rules require that, subject to limited exceptions, PUDs may only be booked if they relate to wells scheduled to be drilled within five years after the date of booking. This requirement has limited and may continue to limit our ability to book additional PUDs. As a result, we may be required to reclassify certain of our PUDs if we do not drill those wells within the required five-year timeframe.
The present value of future net cash flows from our proved reserves is not necessarily the same as the current market value of our estimated proved reserves.
Furthermore, the present value of future net cash flows from our proved reserves, or standardized measure, is not necessarily the same as the current market value of our estimated reserves. In accordance with rules established by the SEC and the Financial Accounting Standards Board (the “FASB”), we base the estimated discounted future net cash flows from our proved reserves on the twelve-month average oil and natural gas index prices, calculated as the unweighted arithmetic average for the first-day-of-the-month price for each month, and costs in effect on the date of the estimate, holding the prices and costs constant throughout the life of the properties. Actual future prices and costs may differ materially from those used in the present value estimate, and future net present value estimates using then current prices and costs may be significantly less than the current estimate. In addition, the 10% discount factor we use when calculating discounted future net cash flows may not be the most appropriate discount factor based on interest rates in effect from time to time and risks associated with us or the oil and natural gas industry in general.
We may incur losses as a result of title or environmental defects in the properties in which we invest.
The existence of a material title or environmental deficiency can render a lease worthless and adversely affect our results of operations and financial condition. While we typically obtain title opinions, the failure of a title may not be discovered until after a lease is invested in, in which case we may lose the lease.
Our undeveloped leasehold acreage is subject to leases that will expire unless production is maintained or subsequent operations are commenced on units containing the acreage or the leases are extended.
The terms of our oil and gas leases often stipulate that the lease will terminate if not held by production, rentals, or otherwise some form of an extension payment to extend the term of the lease. For our non-producing oil and gas leases, if production in paying quantities is not established on units containing leases during an applicable year, then those leases will expire. While some expiring leases may contain predetermined extension payments, other expiring leases will require us to negotiate new leases at the time of lease expiration. Further, existing leases which are currently held by production may unexpectedly encounter operational, political, regulatory, or litigation challenges which could result in their termination. It is possible that market conditions at the time of negotiation could require us to agree to new leases on less favorable terms to us than the terms of the expired leases or cause us to lose the leases entirely. If our leases expire, we will lose our right to develop the related properties.
We may not be able to successfully integrate future acquisitions or realize all of the anticipated benefits from our future acquisitions, and our future results will suffer if we do not effectively manage our expanded operations.
The success of completed acquisitions will depend on our ability to effectively integrate the acquired businesses into our existing operations. The process of integrating acquired businesses may involve unforeseen difficulties and may require a disproportionate amount of our managerial and financial resources. In addition, possible future acquisitions may be larger and for purchase prices significantly higher than those paid for earlier acquisitions. No assurance can be given that we will be able to identify additional suitable acquisition opportunities, negotiate acceptable terms, obtain financing for acquisitions on acceptable terms or successfully acquire identified targets. Our failure to achieve consolidation savings, to integrate the acquired businesses and assets into our existing operations successfully or to minimize any unforeseen operational difficulties could have a material adverse effect on our financial condition and results of operations.
21
In addition, the RBL Facility, any future secured reserve-based lending revolving credit facility that we may enter into, the ABS III Notes, and/or the Warehouse Loan Agreement imposes or will impose certain limitations on our ability to enter into mergers or combination transactions and to incur certain indebtedness and to make certain investments, which could directly or indirectly limit our ability to acquire assets and businesses.
Our business depends on third-party transportation and processing facilities and other assets that are owned by third-parties.
The marketability of our oil and natural gas depends in part on the availability, proximity and capacity of pipeline systems, processing facilities, oil trucking fleets and other transportation assets owned by third parties. The lack of available capacity on these systems and facilities, whether as a result of proration, growth in demand outpacing growth in capacity, physical damage, adverse weather events or natural disasters, equipment malfunctions or failures, scheduled or unscheduled maintenance, legal or other reasons, could result in a substantial increase in costs, declines in realized commodity prices, the shut-in of producing wells, or the delay or discontinuance of development plans for the properties. In many cases, operators are provided only with limited, if any, notice as to when these circumstances will arise and their expected duration. In addition, our wells may be located in areas that are serviced to a limited extent, if at all, by gathering and transportation pipelines, which may or may not have sufficient capacity to transport production from all of the wells in the area. As a result, we may rely on third-party oil trucking to transport a significant portion of our production to third-party transportation pipelines and other market access points.
In addition, the third parties on whom operators rely for transportation services are subject to complex federal, state, tribal, and local laws that could adversely affect the cost, manner, or feasibility of conducting business on the properties. Further, concerns about the safety and security of oil and gas transportation by pipeline may result in public opposition to pipeline development and increased regulation of pipelines by the Pipeline and Hazardous Materials Safety Administration, and therefore less capacity to transport our products by pipeline. Any significant curtailment in gathering system or transportation, processing, or refining-facility capacity could reduce our operating partners’ ability to market oil production and have an adverse effect on us. Operators’ access to transportation options and the prices they receive can also be affected by federal and state regulation — including regulation of oil production, transportation, and pipeline safety — as well as by general economic conditions and changes in supply and demand.
The loss of a key member of our management team, upon whose knowledge, relationships with industry participants, leadership and technical expertise the business relies, could diminish our ability to conduct operations and comply with certain covenants in our debt instruments and harm our ability to execute our business plan.
We depend on the services of our senior management and technical personnel. We do not maintain, nor do we plan to obtain, any insurance against the loss of any of these individuals. The loss of the services of our senior management or technical personnel could have a material adverse effect on our business, financial condition and results of operations.
Additionally, the series supplements governing our ABS III Notes require, as a condition for any acquisitions of additional assets, certain members of our senior management to remain substantially involved in our management or governance.
While we have not historically engaged in significant drilling activities, the unavailability or high cost of drilling rigs, frac crews, equipment, supplies, personnel and oilfield services could adversely affect our or third-party operators’ ability to execute our development plans within current budgets or on a timely basis.
The demand for drilling rigs, frac crews, pipe and other equipment and supplies, including sand and other proppant used in hydraulic fracturing operations and acid used for acid stimulation, as well as for qualified and experienced field personnel, geologists, geophysicists, engineers and other professionals in the oil and natural gas industry, can fluctuate significantly, often in correlation with commodity prices or drilling activity in our areas of operation and in other shale basins in the United States, causing periodic shortages of supplies and needed personnel and rapid increases in costs. Increased drilling activity could materially increase the demand for and prices of these goods and services, and we could encounter rising costs and delays in or an inability to secure the personnel, equipment, power, services, resources and facilities access necessary for us to conduct our drilling and development activities, which could result in production volumes being below our forecasted volumes. In addition, any such negative effect on production volumes, or significant increases in costs could have a material adverse effect on our cash flow and profitability.
22
We have not historically engaged in significant drilling activities. Drilling for and producing oil, natural gas and NGLs are high risk activities with many uncertainties that could adversely affect our business, financial condition or results of operations if we decide to engage in drilling operations in the future.
Our future financial condition and results of operations may depend on the success of our development, production and acquisition activities, which are subject to numerous risks beyond our control. For example, we cannot assure you that wells we drill will be productive or that we will recover all or any portion of our investment in such wells. Drilling for oil, natural gas and NGLs often involves unprofitable efforts from wells that do not produce sufficient oil, natural gas and NGLs to return a profit at then-realized prices after deducting drilling, operating and other costs. In addition, our cost of drilling, completing and operating wells is often uncertain.
Our decisions to develop or purchase prospects or properties will depend, in part, on the evaluation of data obtained through geophysical and geological analyses, production data and engineering studies, which are often inconclusive or subject to varying interpretations. For a discussion of the uncertainty involved in these processes, see “— Our estimated reserves are based on many assumptions that may prove to be inaccurate. Any material inaccuracies in these reserve estimates or underlying assumptions will materially affect the quantities and present value of our reserves.”
Further, many factors may increase the cost of, curtail, delay or cancel any of our future drilling projects, including:
| ● | declines in oil, natural gas and NGL prices; |
| ● | increases in the cost of, and shortages or delays in the availability of, proppant, acid, equipment, services and qualified personnel or in obtaining water for hydraulic fracturing activities; |
| ● | equipment failures, accidents or other unexpected operational events; |
| ● | capacity or pressure limitations on gathering systems, processing and treating facilities or other related midstream infrastructure; |
| ● | any future lack of available capacity on interconnecting transmission pipelines; |
| ● | delays imposed by, or resulting from, compliance with regulatory requirements, including limitations on freshwater sourcing, wastewater disposal, emissions of GHGs and hydraulic fracturing; |
| ● | pressure or irregularities in geological formations; |
| ● | limited availability of financing on acceptable terms; |
| ● | non-compliance with or liability arising under environmental laws and regulations; |
| ● | environmental hazards, such as natural gas leaks, oil spills, pipeline and tank ruptures and unauthorized discharges of brine, well stimulation and completion fluids, toxic gases or other pollutants into the air, surface and subsurface environment; |
| ● | compliance with contractual requirements; |
| ● | competition for surface locations from other operators that may own rights to drill at certain depths across portions of our leasehold; |
| ● | lack of available gathering facilities or delays in construction of gathering facilities; |
| ● | adverse weather conditions, such as hurricanes, lightning storms, flooding, tornadoes, snow or ice storms and changes in weather patterns; |
| ● | the availability and timely issuance of required governmental permits and licenses; |
| ● | title issues or legal disputes regarding leasehold rights; and |
| ● | other market limitations in our industry. |
23
Legislation or regulatory initiatives intended to address the disposal of saltwater gathered from our drilling activities could limit our ability to produce oil and natural gas economically and have a material adverse effect on our business.
We dispose of large volumes of saltwater gathered from our drilling and production operations by injecting the water into wells pursuant to permits issued to us by governmental authorities overseeing such disposal activities. While these permits are issued pursuant to existing laws and regulations, these legal requirements are subject to change, which could result in the imposition of more stringent operating constraints or new monitoring and reporting requirements, owing to, among other things, concerns of the public or governmental authorities regarding such gathering or disposal activities. The adoption and implementation of any new laws or regulations that restrict our ability to dispose of saltwater gathered from our drilling and production activities by limiting volumes, disposal rates, disposal well locations or otherwise, or requiring us to shut down disposal wells, could have a material adverse effect on our business, financial condition and results of operations.
Oil and gas exploration and production companies are frequently subject to litigation claims from landowners, royalty owners and other interested parties, particularly during periods of declining commodity prices.
Title to oil and gas properties is often unclear and subject to claims by third parties. Additionally, oil and gas companies are frequently subject to claims with respect to underpayment of royalties, environmental hazards and contested ownership of properties, especially during periods of declining commodity prices and therefore revenue and royalty payments. The oil and gas exploration and production business is especially susceptible to increased cost of capital, hedging losses and declining revenues which can result in defaults on third party obligations. These risks and others can result in the incurrence of significant attorney’s fees and other expenses incurred in the prosecution or defense of litigation.
An increase in the differential between the benchmark prices of oil and natural gas and the wellhead price we expect to receive for our future production could significantly reduce our cash flow and adversely affect our financial condition.
The prices that we will receive for our oil and natural gas production sometimes may reflect a discount to the relevant benchmark prices, such as the New York Mercantile Exchange (“NYMEX”), that are used for calculating hedge positions. The difference between the benchmark price and the prices we receive is called a basis differential. Increases in the basis differential between the benchmark prices for oil and natural gas and the wellhead price we receive will adversely affect our business, financial condition and results of operations.
Events outside of our control, including widespread public health crises, epidemics and outbreaks of infectious diseases, or the threat thereof, and any related threats of recession and other economic repercussions could have a material adverse effect on our business, liquidity, financial condition, results of operations, cash flows and ability to pay dividends to our shareholders.
Widespread public health crises, epidemics, and outbreaks of infectious diseases, which can give rise to a threat of recession and related economic repercussions can create significant volatility, uncertainty and turmoil in the global economy and oil and gas industry. These variables are beyond our control and may have the effect of disrupting the normal operations of many businesses, including the temporary closure or scale-back of business operations and/or the imposition of either quarantine or remote work or meeting requirements for employees, either by government order or on a voluntary basis. Widespread public health crises, epidemics and outbreaks of infectious diseases spreading throughout the U.S. and globally could result in significant disruptions to our operations. The global economy, our markets and our business have been, and may continue to be, materially and adversely affected by widespread public health crises, epidemics and outbreaks of infectious diseases, which could significantly disrupt our business and operational plans and adversely affect our liquidity, financial condition, results of operations, cash flows and ability to pay dividends on our common stock.
24
We are not insured against all of the operating risks to which our business is exposed.
We maintain insurance against some, but not all, operating risks and losses. Losses and liabilities arising from uninsured and underinsured events could materially and adversely affect our business, financial condition or results of operations.
Our operations are subject to all of the risks associated with producing oil, natural gas and NGLs and operating gathering and processing facilities including the possibility of:
| ● | environmental hazards, such as releases of pollutants into the environment, including groundwater, surface water, soil and air contamination; |
| ● | abnormally pressured formations; |
| ● | mechanical difficulties, such as stuck oilfield drilling and service tools and casing collapse; |
| ● | ruptures, fires and explosions; |
| ● | damage to pipelines, processing plants, compression assets, water infrastructure, and related equipment and surrounding properties caused by tornadoes, floods, freezes, fires and other natural disasters; |
| ● | inadvertent damage from construction, vehicles, farm and utility equipment; |
| ● | personal injuries and death; |
| ● | natural disasters; and |
| ● | terrorist attacks targeting oil and natural gas related facilities and infrastructure. |
Any of these events could adversely affect our ability to conduct operations or result in substantial loss to us as a result of claims by government agencies or third parties for:
| ● | injury or loss of life; |
| ● | damage to and destruction of property, natural resources and equipment; |
| ● | pollution and other environmental damage; |
| ● | regulatory investigations and penalties; and |
| ● | repair and remediation costs. |
These events may also result in curtailment or suspension of our gathering and processing facilities. A natural disaster or any event such as those described above affecting the areas in which we and our third-party operators operate could have a material adverse effect on our operations. Accidents or other operating risks could further result in loss of service available to us and our third-party operators. Such circumstances, including those arising from maintenance and repair activities, could result in service interruptions on portions or all of our gathering facilities.
We may elect not to obtain insurance for certain of these risks if we believe that the cost of available insurance is excessive relative to the risks presented. In addition, in some instances, certain insurance could become unavailable or available only for reduced amounts of coverage, including for pollution and other environmental risks. The occurrence of an event that is not fully covered by insurance could have a material adverse effect on our business, financial condition and results of operations.
A variety of stringent federal, tribal, state, and local laws and regulations, and judicial and agency opinions and orders govern the environmental aspects of the oil and gas business, and noncompliance with these laws and regulations could subject us to material administrative, civil or criminal penalties, injunctive relief or other liabilities.
A variety of stringent federal, tribal, state, and local laws and regulations, and judicial and agency opinions and orders govern the environmental aspects of the oil and gas business. Any noncompliance with these laws, regulations, opinion and orders could subject us to material administrative, civil or criminal penalties, injunctive relief, or other liabilities.
25
Additionally, compliance with these laws, regulations, opinions and orders may, from time to time, result in increased costs of operations, delay in operations, or decreased production, and may affect acquisition costs. Examples of laws and regulations that govern the environmental aspects of the oil and gas business include the following:
| ● | the Clean Air Act (“CAA”), which restricts the emission of air pollutants from many sources, imposes various pre-construction, operating, permitting monitoring, control, record-keeping, and reporting requirements and has historically been relied upon by the U.S. Environmental Protection Agency (“EPA”) as an authority for adopting climate change regulatory initiatives, including relating to GHG emissions; |
| ● | the CWA, which regulates discharges of pollutants and dredge and fill material to state and federal waters and establishes the extent to which waterways are subject to federal jurisdiction as protected waters of the United States; |
| ● | the Oil Pollution Act (“OPA”), which requires oil spill prevention, control, and countermeasure planning and imposes liabilities for removal costs and damages arising from an oil spill into waters of the United States; |
| ● | the Safe Drinking Water Act (“SDWA”), which protects the quality of the nation’s public drinking water sources through adoption of drinking water standards and control over the subsurface injection of fluids into below-ground formations; |
| ● | the Comprehensive Environmental Response, Compensation, and Liability Act (“CERCLA”), which imposes liability without regard to fault on certain categories of potentially responsible parties including generators, transporters and arrangers of hazardous substances at sites where hazardous substance releases have occurred or are threatening to occur, as well as on present and certain past owners and operators of sites where hazardous substance releases have occurred or are threatening to occur; |
| ● | the Resource Conservation and Recovery Act (“RCRA”), which imposes requirements for the generation, treatment, storage, transport, disposal and cleanup of non-hazardous and hazardous wastes; |
| ● | the Endangered Species Act (“ESA”), which restricts activities that may affect federally identified endangered and threatened species or their habitats through the implementation of operating limitations or restrictions or a temporary, seasonal or permanent ban on operations in affected areas. Similar protections are afforded to migratory birds under the Migratory Bird Treaty Act (“MBTA”) and bald and golden eagles under the Bald and Golden Eagle Protection Act (“BGEPA”); |
| ● | the National Environmental Policy Act (“NEPA”), which establishes a national environmental policy and goals for the protection, maintenance and enhancement of the environment, and mandates that major projects requiring federal permits or involving federal funding that have the potential to significantly impact the environment require review under NEPA; |
| ● | the Emergency Planning and Community Right-to-Know Act (“EPCRA”), which requires certain facilities to report toxic chemical uses, inventories, and releases and to disseminate such information to local emergency planning committees and response departments; and |
| ● | the Occupational Safety and Health Act (“OSHA”) and comparable state statutes, which impose regulations related to the protection of worker health and safety, including requiring employers to implement a hazard communication program and disseminate hazard information to employees. |
These U.S. laws and their implementing regulations, as well as state counterparts, generally restrict or otherwise regulate the management of hazardous substances and wastes, the level of pollutants emitted to ambient air, discharges to surface water, and disposals or other releases to surface and below-ground soils and groundwater, including through permitting requirements, monitoring and reporting requirements, limitations or prohibitions of operations on certain protected areas, requirements to install certain emissions monitoring or control equipment, spill planning and preparedness requirements, and the application of specific worker health and safety criteria (see “Business of Presidio Production Company — Legislative and Regulatory Environment — Climate Change” for further discussion). Failure to comply with applicable environmental laws and regulations by us or third-party operators or contractors could trigger a variety of administrative, civil and criminal enforcement measures, including the assessment of monetary penalties, the imposition of remedial requirements or other corrective measures, and the issuance of orders enjoining existing or future operations. In addition, we or our operating partners may be strictly liable under state or federal laws for environmental damages caused by the previous owners or operators of properties they purchase, without regard to fault. Environmental laws and regulations change frequently and tend to become more stringent over time, and the implementation of new, or the modification of existing, laws or regulations could adversely affect our business.
26
Specific climate legislation and regulation regarding emissions of carbon dioxide, methane and other greenhouse gases have been, and in the future, may further develop or be enacted, which could adversely affect the oil and gas industry and demand for the oil, NGLs and gas produced from the properties.
The energy industry is affected from time to time in varying degrees by political developments and a wide range of federal, tribal, state and local statutes, rules, orders and regulations that may, in turn, affect the operations and costs of the companies engaged in the energy industry. In response to findings that emissions of carbon dioxide, methane, and other GHGs present an endangerment to public health and the environment (“GHG Endangerment Finding”), the EPA has adopted regulations under existing provisions of the CAA that, among other things, require preconstruction and operating permits for GHG emissions from certain large stationary sources that already emit conventional pollutants above a certain threshold. On February 12, 2026, the EPA finalized its recission of the GHG Endangerment Finding, creating uncertainty as to EPA’s future regulation of GHG emissions.
In December 2023, the EPA finalized more stringent methane rules for new, modified, and reconstructed facilities, known as OOOOb, as well as standards for existing sources for the first time ever, known as OOOOc. Under the final rules, states had two years to prepare and submit their plans to impose methane emission controls on existing sources. The presumptive standards established under the final rule are generally the same for both new and existing sources and include enhanced leak detection survey requirements using optical gas imaging and other advanced monitoring to encourage the deployment of innovative technologies to detect and reduce methane emissions, reduction of emissions by 95% through capture and control systems, zero-emission requirements for certain devices, and the establishment of a “super emitter” response program that would allow third parties to make reports to EPA of large methane emission events, triggering certain investigation and repair requirements. Fines and penalties for violations of these rules can be substantial. The rules have been subject to legal challenge, and in February 2025, the D.C. Circuit granted the EPA’s motion to hold the cases in abeyance while the agency reviews the final rules. In March 2025, the EPA announced reconsideration of the rules and, in Novemeber 2025, the EPA issued a final rule to extend several compliance deadlines in OOOOb and OOOOc while the reconsideration is pending. In addition, in November 2024, the EPA finalized regulations to implement the Inflation Reduction Act’s Waste Emissions Charge (WEC), a per-ton fee on methane emissions above a specified threshold which became effective in January 2025. In February 2025, Congress utilized the Congressional Review Act to rescind the EPA’s rule implementing the WEC. The One Big Beautiful Bill Act, enacted July 4, 2025, postponed EPA’s imposition of the WEC to calendar year 2034. While the Trump Administration may take additional action to repeal or modify the methane rules, we cannot predict the substance or timing of such changes, if any. However, the requirements of the EPA’s final methane rules have the potential to increase the operating costs of our operators and thus may adversely affect our financial results and cash flows. Moreover, failure to comply with these CAA requirements can result in the imposition of substantial fines and penalties as well as costly injunctive relief. These rules could further increase the cost of development and operation of the properties.
In the absence of comprehensive federal climate legislation, a number of state and regional efforts have emerged that are aimed at tracking or reducing GHG emissions by means of cap-and-trade programs. These programs typically require major sources of GHG emissions to acquire and surrender emission allowances in return for emitting those GHGs.
Although it is not possible at this time to predict how legislation or new regulations that may be adopted to address GHG emissions would impact us, any future laws and regulations imposing reporting obligations on, or limiting emissions of GHGs from, operators’ equipment and operations could require them to incur costs to reduce emissions of GHGs associated with their operations. In addition, substantial limitations on GHG emissions could adversely affect demand for the oil and gas produced from the properties.
27
Federal, state and local legislative or regulatory initiatives relating to hydraulic fracturing as well as governmental reviews of such activities, could restrict our operations, which could limit our ability to produce oil, NGLs and natural gas economically and have a material adverse effect on our business.
Hydraulic fracturing is a common practice used to stimulate production of oil and/or natural gas from dense subsurface rock formations and is important to our business. The hydraulic fracturing process involves the injection of water, proppants and chemicals under pressure into targeted subsurface formations to fracture the surrounding rock and stimulate production. We and our third-party operators use hydraulic fracturing as part of our operations. Recently, there has been increased public concern regarding an alleged potential for hydraulic fracturing to adversely affect drinking water supplies or trigger seismic activity. Proposals have been made from time to time to enact separate federal, state and local legislation that would increase the regulatory burden imposed on hydraulic fracturing.
Presently, hydraulic fracturing is regulated primarily at the state level, typically by state oil and natural gas commissions and similar agencies. Local governments may seek to adopt ordinances within their jurisdictions regulating the time, place and manner of drilling activities in general or hydraulic fracturing activities in particular or prohibiting the performance of well drilling in general or hydraulic fracturing in particular. If new or more stringent federal, state or local legal restrictions relating to the hydraulic fracturing process are adopted in areas where we operate, we could incur potentially significant added costs to comply with such requirements, experience delays or curtailment in the pursuit of development activities, and perhaps even be precluded from drilling wells.
In addition, the EPA has asserted federal regulatory authority pursuant to the SDWA over certain hydraulic fracturing activities involving the use of diesel fuels and published permitting guidance in February 2014 addressing the performance of such activities. The EPA also finalized rules under the CWA in June 2016 that prohibit the discharge of wastewater from hydraulic fracturing and certain other natural gas operations to publicly owned wastewater treatment plants. Additionally, in December 2016, the EPA released its final report on the potential impacts of hydraulic fracturing on drinking water resources. The final report concluded that certain activities associated with hydraulic fracturing may impact drinking water resources under some circumstances. However, in January 2025, President Trump issued executive orders directing the heads of all federal agencies to identify and begin the processes to suspend, revise, or rescind all agency actions that are unduly burdensome on the identification, development, or use of domestic energy resources. As a result, any future revisions to the SDWA and CWA are uncertain at this time.
In March 2016, the U.S. Occupational Safety and Health Administration issued a final rule to impose stricter standards for worker exposure to silica, which went into effect in June 2018 and applies to use of sand as a proppant for hydraulic fracturing. On April 10, 2024, U.S. Department of the Interior’s Bureau of Land Management (“BLM”) issued a final rule to reduce the waste of natural gas from venting, flaring, and leaks during oil and gas production activities on Federal and Indian leases. On December 15, 2025, the BLM published an extension of certain regulatory deadlines, pending reconsideration of the 2024 final rule. New laws or regulations that impose new obligations on, or significantly restrict hydraulic fracturing, could make it more difficult or costly for us to perform hydraulic fracturing activities and thereby affect our determination of whether a well is commercially viable and increase our cost of doing business. Such increased costs and any delays or curtailments in our production activities could have a material adverse effect on our business, prospects, financial condition, results of operations and liquidity.
We depend on computer and telecommunications systems, and failures in those systems or cybersecurity threats, attacks and other disruptions could significantly disrupt our business operations.
We are heavily dependent on our information systems and computer-based programs, including our well operations information, geologic data, electronic data processing and accounting data. If any of such programs or systems were to fail or create erroneous information in our hardware or software network infrastructure or we were subject to cyberspace breaches or attacks, possible consequences include our loss of communication links, inability to find, produce, process and sell oil and natural gas and inability to automatically process commercial transactions or engage in similar automated or computerized business activities. Any such consequence could have a material adverse effect on our business.
28
As an oil and natural gas producer, we face various security threats, including cyber-security threats to gain unauthorized access to sensitive information or to render data or systems unusable, threats to the safety of our employees, threats to the security of our facilities and infrastructure or third-party facilities and infrastructure, such as processing plants and pipelines, and threats from terrorist acts. Cyber-security attacks in particular are evolving and include, but are not limited to, malicious software, attempts to gain unauthorized access to data, and other electronic security breaches that could lead to disruptions in critical systems, unauthorized release of confidential or otherwise protected information and corruption of data. Although we utilize various procedures and controls to monitor and protect against these threats and to mitigate our exposure to such threats, there can be no assurance that these procedures and controls will be sufficient in preventing security threats from materializing. If any of these events were to materialize, they could lead to losses of sensitive information, critical infrastructure, personnel or capabilities essential to our operations and could have a material adverse effect on our reputation, financial position, results of operations, or cash flows.
We may be involved in legal and regulatory proceedings that could result in substantial liabilities.
Like many oil and gas companies, we are, or may be, from time to time involved in various legal and other proceedings, such as title, royalty or contractual disputes, regulatory compliance matters, alleged violations of federal or state securities laws and personal injury, environmental damage or property damage matters, in the ordinary course of our business. Additionally, members of our management and our directors may, from time to time, be involved in various legal and other proceedings against the Company naming those officers or directors as co-defendants. Such legal and regulatory proceedings are inherently uncertain, and their results cannot be predicted. Regardless of the outcome, such proceedings could have an adverse impact on us because of legal costs, diversion of management and other personnel and other factors. In addition, it is possible that a resolution of one or more such proceedings could result in liability, penalties or sanctions, as well as judgments, consent decrees or orders requiring a change in our business practices, which could materially and adversely affect our business, operating results and financial condition and affect the value of our shares of common stock. Accruals for such liability, penalties or sanctions may be insufficient, and judgments and estimates to determine accruals or range of losses related to legal and other proceedings could change from one period to the next, and such changes could be material. The defense of any legal proceedings against us or our officers or directors, could take resources away from our operations and divert management attention. As of the date of this prospectus, the Company is not aware of any material legal proceedings contemplated to be brought against the Company or its management.
We are subject to a number of privacy and data protection laws, rules and directives (collectively, “data protection laws”) relating to the processing of personal data.
The regulatory environment surrounding data protection laws is uncertain. Varying jurisdictional requirements could increase the costs and complexity of compliance with such laws, and violations of applicable data protection laws can result in significant penalties. A determination that there have been violations of applicable data protection laws could expose us to significant damage awards, fines and other penalties that could materially harm our business and reputation.
Any failure, or perceived failure, by us to comply with applicable data protection laws could result in proceedings or actions against us by governmental entities or others, subject us to significant fines, penalties, judgments and negative publicity, require us to change our business practices, increase the costs and complexity of compliance and adversely affect our business. As noted above, we are also subject to the possibility of security and privacy breaches, which themselves may result in a violation of these laws. Additionally, the acquisition of a company that is not in compliance with applicable data protection laws may result in a violation of these laws.
We are subject to compliance with environmental and occupational safety and health laws and regulations that may expose us to significant costs and liabilities. Our ability to retain and/or obtain necessary licenses and permits to operate the business may negatively impact our financial results.
Our operations are subject to stringent federal, regional, state and local laws and regulations governing worker health and safety aspects of our operations, the discharge of materials into the environment and otherwise relating to environmental protection. Such environmental laws and regulations impose numerous obligations that are applicable to our operations, including the acquisition of permits to conduct regulated activities, the incurrence of capital expenditures to comply with applicable legal requirements, the application of specific health and safety criteria addressing worker protections and the imposition of restrictions on the generation, handling, treatment, storage, disposal and transportation of materials and wastes.
29
Scrutiny of Environmental, Social and Governance (“ESG”) matters by investors in public companies could have an adverse effect on our business, financial condition and results of operations and damage our reputation.
Companies across all industries are facing scrutiny from a variety of stakeholders, including investor advocacy groups, proxy advisory firms, certain institutional investors and lenders, investment funds and other influential investors and rating agencies, related to their ESG and sustainability practices. If we do not adapt to or comply with investor or other stakeholder expectations and standards on ESG matters as they continue to evolve, or if we are perceived to have not responded appropriately or quickly enough to concern for ESG and sustainability issues, regardless of whether there is a regulatory or legal requirement to do so, we may suffer from reputational damage and our business, financial condition and/or stock price could be materially and adversely affected. In addition, organizations that provide information to investors on corporate governance and related matters have developed ratings processes for evaluating companies on their approach to ESG matters. Such ratings are used by some investors to inform their investment and voting decisions. Unfavorable ESG ratings could lead to increased negative investor sentiment toward us and our industry and to the diversion of investment to other industries, which could have a negative impact on our stock price and our access to and costs of capital.
Risks Related to Presidio’s Organizational Structure
Our principal asset is our interest in Prometheus Holdings and, as a result, we depend on distributions from Prometheus Holdings to pay our taxes and operating expenses. Prometheus Holdings’ ability to make such distributions may be subject to various limitations and restrictions.
We are a holding company and have no material assets other than our ownership of LLC Interests in Prometheus Holdings. As such, we have no independent means of generating revenue or cash flow, and our ability to pay our taxes and operating expenses or declare and pay dividends in the future, if any, is dependent upon the financial results and cash flows of Prometheus Holdings and its subsidiaries and distributions we receive from Prometheus Holdings. There can be no assurance that Prometheus Holdings and its subsidiaries will generate sufficient cash flow to distribute funds to us or that applicable state law and contractual restrictions, including negative covenants in our debt instruments, will permit such distributions. Although Prometheus Holdings is not currently subject to any debt instruments or other agreements that would restrict its ability to make distributions to us, the terms of our outstanding indebtedness restrict the ability of our subsidiaries to pay dividends to Prometheus Holdings.
Prometheus Holdings will continue to be treated as a partnership for U.S. federal income tax purposes and, as such, generally will not be subject to any entity-level U.S. federal income tax. Instead, any taxable income of Prometheus Holdings will be allocated to holders of LLC Interests, including us. Accordingly, we will incur income taxes on our allocable share of any net taxable income of Prometheus Holdings. Under the terms of the Prometheus Holdings LLC Agreement, Prometheus Holdings will be obligated, subject to various limitations and restrictions, including with respect to our debt agreements, to make tax distributions to holders of LLC Interests, including us. In addition to tax expenses, we will also incur expenses related to our operations, which we expect could be significant. We intend, as its managing member, to cause Prometheus Holdings to make cash distributions to the holders of LLC Interests (including us) in an amount sufficient to (i) fund all or part of their tax obligations in respect of taxable income allocated to them and (ii) cover our operating expenses. However, Prometheus Holdings’ ability to make such distributions may be subject to various limitations and restrictions, such as restrictions on distributions that would either violate any contract or agreement to which Prometheus Holdings is then a party, including debt agreements, or any applicable law, or that would have the effect of rendering Prometheus Holdings insolvent. If we do not have sufficient funds to pay tax or other liabilities, or to fund our operations, we may have to borrow funds, which could materially and adversely affect our liquidity and financial condition, and subject us to various restrictions imposed by any lenders of such funds. See “Certain Relationships and Related Person Transactions — Prometheus Holdings LLC Agreement.” In addition, if Prometheus Holdings does not have sufficient funds to make distributions, our ability to declare and pay cash dividends will also be restricted or impaired. See “— Risks Related to Ownership of Presidio Securities.”
30
Under the Prometheus Holdings LLC Agreement, we intend to cause Prometheus Holdings, from time to time, to make distributions in cash to its members (including us) in amounts sufficient to cover the taxes imposed on their allocable share of taxable income of Prometheus Holdings. As a result of (i) potential differences in the amount of net taxable income allocable to us and to Prometheus Holdings’ other members, (ii) the lower tax rate applicable to corporations as opposed to individuals, and (iii) certain tax benefits that we anticipate from future purchases or redemptions of LLC Interests from the Continuing Equity Owners, these tax distributions may be in amounts that exceed our tax liabilities. Our board of directors will determine the appropriate uses for any excess cash so accumulated, which may include, among other uses, the payment of other expenses. We have no obligation to distribute such cash (or other available cash) to our stockholders. To the extent we do not distribute such excess cash as dividends on the Presidio Class A Common Stock, we may take other actions with respect to such excess cash, for example, holding such excess cash, contributing such cash to Prometheus Holdings in exchange for additional LLC Interests or lending it (or a portion thereof) to Prometheus Holdings, some of which may result in shares of the Presidio Class A Common Stock increasing in value relative to the value of LLC Interests. The holders of LLC Interests may benefit from any value attributable to such cash balances if they acquire shares of Class A common stock in exchange for their LLC Interests, notwithstanding that such holders may have participated previously as holders of LLC Interests in distributions that resulted in such excess cash balances.
Our organizational structure confers certain benefits upon the PIH equity holders that does not benefit holders of the Presidio Class A Common Stock to the same extent that it benefits the PIH equity holders.
Our organizational structure confers certain benefits upon the PIH equity holders that do not benefit the holders of the Presidio Class A Common Stock to the same extent that it benefits the PIH equity holders.
Additionally, we are a holding company and have no material assets other than our ownership of LLC Interests. As a consequence, our ability to declare and pay dividends to the holders of the Presidio Class A Common Stock is subject to the ability of Prometheus Holdings to provide distributions to us. If Prometheus Holdings makes such distributions, the PIH equity holders that hold LLC Interests will be entitled to receive equivalent distributions from Prometheus Holdings on a pro rata basis. However, because we must pay taxes, amounts ultimately distributed as dividends to holders of the Presidio Class A Common Stock are expected to be less on a per share basis than the amounts distributed by Prometheus Holdings to such PIH equity holders on a per unit basis. This and other aspects of our organizational structure may adversely impact the future trading market for the Presidio Class A Common Stock.
If Prometheus Holdings were to become a publicly traded partnership taxable as a corporation for U.S. federal income tax purposes, we and Prometheus Holdings might be subject to potentially significant tax inefficiencies.
We intend to operate such that Prometheus Holdings does not become a publicly traded partnership taxable as a corporation for U.S. federal income tax purposes. A “publicly traded partnership” is a partnership the interests of which are traded on an established securities market or are readily tradable on a secondary market or the substantial equivalent thereof. Under certain circumstances, redemptions of LLC Interests pursuant to the redemption right, or other transfers of LLC Interests, could cause Prometheus Holdings to be treated as a publicly traded partnership. Applicable U.S. Treasury regulations provide for certain safe harbors from treatment as a publicly traded partnership, and we intend to operate such that redemptions or other transfers of LLC Interests qualify for one or more such safe harbors. If Prometheus Holdings were to become a publicly traded partnership taxable as a corporation for U.S. federal income tax purposes, significant tax inefficiencies might result for us and for Prometheus Holdings, including as a result of the inability to file a consolidated U.S. federal income tax return with Prometheus Holdings.
If we were deemed to be an investment company under the Investment Company Act of 1940, as amended, or the 1940 Act, including as a result of our ownership of Prometheus Holdings, applicable restrictions could make it impractical for us to continue our business as contemplated and could have a material adverse effect on our business.
Under Sections 3(a)(1)(A) and (C) of the 1940 Act, a company generally will be deemed to be an “investment company” for purposes of the 1940 Act if (i) it is, or holds itself out as being, engaged primarily, or proposes to engage primarily, in the business of investing, reinvesting or trading in securities, or (ii) it engages, or proposes to engage, in the business of investing, reinvesting, owning, holding or trading in securities and it owns or proposes to acquire investment securities having a value exceeding 40% of the value of its total assets (exclusive of U.S. government securities and cash items) on an unconsolidated basis. We do not believe that we are an “investment company,” as such term is defined in either of those sections of the 1940 Act.
31
We and Prometheus Holdings intend to conduct our operations so that we are not deemed an investment company. As the sole managing member of Prometheus Holdings, we control and operate Prometheus Holdings. On that basis, we believe that our interest in Prometheus Holdings is not an “investment security” as that term is used in the 1940 Act. However, if we were to cease participation in the management of Prometheus Holdings, or if Prometheus Holdings itself becomes an investment company, our interest in Prometheus Holdings could be deemed an “investment security” for purposes of the 1940 Act.
If it were established that we were an unregistered investment company, there would be a risk that we would be subject to monetary penalties and injunctive relief in an action brought by the SEC, that we would be unable to enforce contracts with third parties and that third parties could seek to obtain rescission of transactions undertaken during the period it was established that we were an unregistered investment company. If we were required to register as an investment company, restrictions imposed by the 1940 Act, including limitations on our capital structure and our ability to transact with affiliates, could make it impractical for us to continue our business as contemplated and could have a material adverse effect on our business.
Risks Related to Ownership of Presidio Securities
The sale of shares by the Selling Securityholders, or the perception in the market that the Selling Securityholders intend to sell shares, could increase the volatility of the market price of Presidio Class A Common Stock or result in a significant decline in the public trading price of the Presidio Class A Common Stock.
Given the substantial number of shares of Presidio Class A Common Stock being registered for potential resale by Selling Securityholders pursuant to this prospectus, the sale of shares by the Selling Securityholders, or the perception in the market that the Selling Securityholders intend to sell shares, could increase the volatility of the market price of Presidio Class A Common Stock or result in a significant decline in the public trading price of the Presidio Class A Common Stock. In connection with the Business Combination, holders of 33,593,272 shares of EQV Class A common stock, or approximately 96% of the outstanding shares of EQV Class A Common Stock, exercised their rights to have those shares redeemed for cash at a redemption price of approximately $10.59 per share, or an aggregate of approximately $355.8 million. The shares of Presidio Class A Common Stock being offered for resale pursuant to this prospectus by the Selling Securityholders represent a substantial portion of the outstanding shares of Presidio Class A Common Stock as of the date of this prospectus. Even if the current trading price of the Presidio Class A Common Stock is close to the price at which the units were initially issued in EQV’s initial public offering, certain Selling Securityholders may have an incentive to sell because they will still profit on sales due to the lower price at which they purchased their shares compared to the public investors. The public securityholders may not experience a similar rate of return on the securities they purchase due to differences in the purchase prices and the current trading price.
There is no guarantee that the Presidio Warrants will be in the money, and they may expire worthless.
The exercise price for the Presidio Warrants is $11.50 per share of Presidio Class A Common Stock, subject to adjustment. There is no guarantee that the Presidio Warrants will be in the money prior to their expiration, and as such, the Presidio Warrants may expire worthless. In addition, warrant holders do not have the rights of holders of Presidio Class A Common Stock, and if we liquidate, holders of Presidio Warrants will not receive distributions with respect to such warrants.
An active market for Presidio’s securities may not develop, which would adversely affect the liquidity and price of Presidio’s securities.
The price of Presidio’s securities may vary significantly due to factors specific to Presidio as well as to general market or economic conditions. Furthermore, an active trading market for Presidio’s securities may never develop or, if developed, it may not be sustained. Additionally, if Presidio securities become delisted from NYSE for any reason and are quoted on the OTC Pink Sheets, an inter-dealer automated quotation system for equity securities not listed on a national exchange, the liquidity and price of Presidio securities may be more limited than if they were listed on the NYSE or another national exchange. You may be unable to sell your securities unless a market can be established and sustained.
32
In addition, NYSE may delist Presidio’s securities from trading on its exchange, which could limit investors’ ability to make transactions in Presidio’s securities and subject Presidio to additional trading restrictions.
The market price of the Presidio Class A Common Stock may decline if investors conclude that Presidio has not realized, or may not realize, the expected benefits of the Business Combination.
The market price of Presidio Class A Common Stock may decline if investors conclude that Presidio has not realized, or may not realize, the expected benefits of the Business Combination for a number of reasons, including if:
| ● | the effect of the Business Combination on Presidio’s business and prospects is not consistent with the expectations of financial or industry analysts; or |
| ● | Presidio does not achieve the perceived benefits of the Business Combination as rapidly or to the extent anticipated by financial or industry analysts. |
As a result, you may not receive any return on an investment in Presidio Class A Common Stock unless you sell your Presidio Class A Common Stock for a price greater than that which you paid for it.
The Series A Preferred Stock has rights, preferences and privileges that are senior to the Presidio Class A Common Stock and the Series B Preferred Stock.
As of September 18, 2026, we have 126,628 shares of Series A Preferred Stock outstanding. The Series A Preferred Stock has rights, preferences and privileges that are senior to those of the Presidio Class A Common Stock, including with respect to liquidation and, in certain circumstances, dividends and other distributions.
In the event of our liquidation, dissolution or winding up, holders of shares of Series A Preferred Stock will be entitled to receive distributions before any distribution is made to holders of the Presidio Class A Common Stock and the Series B Preferred Stock. As a result, holders of the Presidio Class A Common Stock and the Series B Preferred Stock bear a greater risk that they will not recover their investment in the event of our liquidation.
The exercise of outstanding warrants will increase the number of shares eligible for future resale and may adversely affect the market price of the Presidio Class A Common Stock.
As of September 18, 2026, there are 11,666,571 Public Warrants, 220,832 Private Placement Warrants and 881,250 Series A Preferred Investor Warrants outstanding. Each warrant entitles the holder to purchase one share of Presidio Class A Common Stock (subject to adjustment) at the applicable exercise price. We are registering the shares of Presidio Class A Common Stock issuable upon exercise of these warrants.
To the extent such warrants are exercised, the number of shares of Presidio Class A Common Stock outstanding will increase, which will dilute the ownership interests of existing stockholders. In addition, the resale of the shares underlying such warrants, or the perception that such resales may occur, could cause the market price of Presidio Class A Common Stock to decline.
The existence of a substantial number of warrants may also adversely affect our ability to obtain additional financing on favorable terms, as prospective investors may consider the potential dilutive impact of warrant exercises.
We may redeem the Public Warrants at a time that is disadvantageous to the holder, which could reduce the value of such investment.
Once the Public Warrants become exercisable, we may redeem the Public Warrants for $0.01 per warrant if the trading price of Presidio Class A Common Stock equals or exceeds $18.00 per share for 20 trading days within a 30-trading day period, and we provide at least 30 days’ prior notice. If we redeem the Public Warrants, holders will be forced to (i) exercise the warrants and pay the exercise price (or, if permitted, exercise on a cashless basis), (ii) sell the warrants at the then-current market price or (iii) accept the nominal redemption price, which is likely to be substantially less than the market value of the warrants at the time of redemption.
33
If we require or permit cashless exercise of warrants, you will receive fewer shares than if you exercised for cash, which could result in holders receiving fewer shares of Presidio Class A Common Stock than if such warrants were exercised for cash.
Pursuant to the Presidio Warrant Agreement, we may, at our option, require holders of the Public Warrants who exercise the warrants to do so on a “cashless basis” in certain circumstances, including if we redeem the Public Warrants. In a cashless exercise, the number of shares issuable is reduced based on a formula tied to market price, meaning holders of the Public Warrants would receive fewer shares of Presidio Class A Common Stock from such exercise than if such Public Warrants were exercised for cash.
Stockholders may experience dilution in the future.
The percentage of Presidio Class A Common Stock owned by current stockholders may be diluted in the future because of equity issuances for acquisitions, capital market transactions or otherwise, including, without limitation, equity awards that Presidio may grant to its directors, officers and employees, and the exercise of the Presidio Warrants and the Series A Preferred Investor Warrants. Such issuances may have a dilutive effect on Presidio’s earnings per share, which could adversely affect the market price of Presidio Class A Common Stock.
If securities or industry analysts do not publish research or reports about Presidio’s business, if they change their recommendations regarding Presidio Class A Common Stock or if Presidio’s operating results do not meet their expectations, the Presidio Class A Common Stock price and trading volume could decline.
The trading market for Presidio Class A Common Stock will depend in part on the research and reports that securities or industry analysts publish about Presidio or its businesses. If no securities or industry analysts commence coverage of Presidio, the trading price for Presidio Class A Common Stock could be negatively impacted. In the event securities or industry analysts initiate coverage, if one or more of the analysts who cover Presidio downgrade its securities or publish unfavorable research about its businesses, or if Presidio’s operating results do not meet analyst expectations, the trading price of Presidio Class A Common Stock would likely decline. If one or more of these analysts cease coverage of Presidio or fail to publish reports on Presidio regularly, demand for Presidio securities could decrease, which might cause the Presidio Class A Common Stock price and trading volume to decline.
Future sales, or the perception of future sales, by Presidio or its stockholders in the public market could cause the market price for Presidio Class A Common Stock to decline.
Sales of substantial amounts of Presidio Class A Common Stock in the public market, or the perception that such sales could occur, could harm the prevailing market price of Presidio Class A Common Stock. These sales, or the possibility that these sales may occur, also might make it more difficult for Presidio to sell equity securities in the future at a time and at a price that it deems appropriate. We cannot predict what effect, if any, market sales of Presidio Class A Common Stock or the availability of these securities for future sale will have on the market price of the Presidio Class A Common Stock.
34
Upon the Closing, the public shareholders retained an ownership interest of approximately 4.8% of the outstanding capital stock of Presidio, Sponsor retained an ownership interest of approximately 26.2% of the outstanding capital stock of Presidio and the PIH securityholders retained approximately 23.7% of the outstanding capital stock of Presidio. The foregoing ownership percentages with respect to Presidio exclude any Series A Preferred Stock, Series B Preferred Stock, Presidio Warrants, Series A Preferred Investor Warrants and Restricted Stock Units. All shares currently held by public shareholders are freely tradable without registration under the Securities Act, and without restriction by persons other than Presidio’s “affiliates” (as defined under Rule 144 under the Securities Act (“Rule 144”)), including Presidio’s directors, executive officers and other affiliates.
In connection with the Business Combination Agreement, certain individuals, each of whom was a member of the EQV Board or EQV management, and Sponsor, have agreed with EQV and PIH, subject to certain exceptions, not to dispose of or hedge certain of their Presidio Class A Common Stock or securities convertible into or exchangeable for Presidio Class A Common Stock during the period from the date of the Closing continuing through the earliest of: (i) the twelve-month anniversary of the Closing, and (ii) the date after the Closing on which Presidio consummates a liquidation, merger, capital stock exchange, or other similar transaction that results in all of the Presidio stockholders having the right to exchange their Presidio Class A Common Stock for cash, securities or other property. See “Certain Relationships and Related Person Transactions — Sponsor Arrangements.” These shares may be sold after the expiration of the applicable restrictions, and Presidio may file one or more registration statements prior to or shortly after the Closing to provide for the resale of such shares from time to time. The market price of the Presidio Class A Common Stock could decline if the holders of currently restricted shares sell them or are perceived by the market as intending to sell them.
Moreover, each of EQV, the Sponsor, Presidio, Prometheus Holdings, PIH and certain members of EQV’s board of directors and/or management (the “Insiders”) agreed to be bound by certain lock-up provisions during the lock-up periods described in the Sponsor Letter Agreement with respect to their equity interests in EQV, and the Sponsor agreed to subject certain of its Class B Shares to vesting (or forfeiture) on the basis of achieving certain trading price thresholds during the first five years following the Closing pursuant to an earnout program. The Sponsor also agreed to subject certain of its Class B Shares to time vesting during the first three years following the Closing pursuant to a dividend reinvestment program, which will fall away on the basis of achieving certain trading price thresholds during the first three years following the Closing.
In addition, the Presidio Class A Common Stock reserved for future issuance under the Incentive Plan will become eligible for sale in the public market once those shares are issued, subject to any applicable vesting requirements, lockup agreements and other restrictions imposed by law. A total number of shares representing about 10% of the fully diluted, and as converted, outstanding Presidio Class A Common Stock is reserved for future issuance under the Incentive Plan. The aggregate number of shares that may be issued under the Incentive Plan is subject to an annual increase on January 1 of each calendar year (commencing with the first January 1 following the Closing Date and ending on and including the January 1 immediately following the ninth anniversary of the Closing Date) of a number of shares equal to 5% of the total number of shares actually issued and outstanding on the last day of the preceding fiscal year. Presidio is expected to file one or more registration statements on Form S-8 under the Securities Act to register Presidio Class A Common Stock or securities convertible into or exchangeable for Presidio Class A Common Stock issued pursuant to the Incentive Plan. Any such Form S-8 registration statements will automatically become effective upon filing. Accordingly, shares registered under such registration statements will be available for sale in the open market.
In the future, Presidio may also issue its securities in connection with investments or acquisitions. The amount of Presidio Class A Common Stock issued in connection with an investment or acquisition could constitute a material portion of the then-outstanding Presidio Class A Common Stock. Any issuance of additional securities in connection with investments or acquisitions may result in additional dilution to Presidio stockholders.
The trading price of the Presidio Class A Common Stock is likely to continue to be volatile, which could result in substantial losses to investors.
The trading price of the Presidio Class A Common Stock is likely to continue to be volatile and fluctuate widely due to factors beyond its control or unrelated to its historical financial performance and condition and prospects. This may happen because of broad market and industry factors, including the performance and fluctuation of the market prices of other companies with business operations similar to Presidio. In addition to market and industry factors, the price and trading volume for the Presidio Class A Common Stock may be highly volatile for factors specific to Presidio’s operations, including the following:
| ● | variations in its revenues, earnings and cash flow; |
35
| ● | announcements of new investments, acquisitions, strategic partnerships or joint ventures by it or its competitors; |
| ● | announcements of new offerings, solutions and expansions by it or its competitors; |
| ● | changes in financial estimates by securities analysts; |
| ● | detrimental adverse publicity about it, its services or its industry; |
| ● | announcements of new regulations, rules or policies relevant for its business; |
| ● | additions or departures of key personnel; |
| ● | release of lockup or other transfer restrictions on its outstanding equity securities or sales of additional equity securities; and |
| ● | potential litigation or regulatory investigations. |
Any of these factors may result in large and sudden changes in the volume and price at which the Presidio Class A Common Stock will trade.
In the past, shareholders of public companies have often brought securities class action suits against those companies following periods of instability in the market price of their securities. If Presidio was to be involved in a class action suit, it could divert a significant amount of its management’s attention and other resources from its business and operations and require it to incur significant expenses to defend the suit, which could harm its results of operations. Any such class action suit, whether or not successful, could harm its reputation and restrict its ability to raise capital in the future. In addition, if a claim is successfully made against Presidio, it may be required to pay significant damages, which could have a material adverse effect on its financial condition and results of operations.
If securities or industry analysts do not publish research or reports about Presidio’s business, or if they adversely change their recommendations regarding the Presidio Class A Common Stock, the market price for the Presidio Class A Common Stock and trading volume could decline.
The trading market for the Presidio Class A Common Stock will be influenced by research or reports that industry or securities analysts publish about its business. If one or more analysts who cover Presidio downgrade the Presidio Class A Common Stock, the market price for the Presidio Class A Common Stock would likely decline. If one or more of these analysts cease to cover Presidio or fail to regularly publish reports on it, it could lose visibility in the financial markets, which in turn could cause the market price or trading volume for the Presidio Class A Common Stock to decline.
Techniques employed by short sellers may drive down the market price of the Presidio Class A Common Stock.
Short selling is the practice of selling securities that the seller does not own but rather has borrowed from a third party with the intention of buying identical securities back at a later date to return to the lender. The short seller hopes to profit from a decline in the value of the securities between the sale of the borrowed securities and the purchase of the replacement shares, as the short seller expects to pay less in that purchase than it received in the sale. As it is in the short seller’s interest for the price of the security to decline, many short sellers publish, or arrange for the publication of, negative opinions regarding the relevant issuer and its business prospects in order to create negative market momentum and generate profits for themselves after selling a security short. These short sellers’ attacks have, in the past, led to selling of shares in the market.
Public companies often are the subject of short selling. Much of the scrutiny and negative publicity often centers on allegations of a lack of effective internal control over financial reporting resulting in financial and accounting irregularities and mistakes, inadequate corporate governance policies or a lack of adherence thereto and, in many cases, allegations of fraud. As a result, many companies are now conducting internal and external investigations into the allegations and, in the interim, are subject to shareholder lawsuits and/or SEC enforcement actions.
36
It is not clear what effect such negative publicity could have on Presidio. If it were to become the subject of any unfavorable allegations, whether such allegations are proven to be true or untrue, Presidio could have to expend a significant amount of resources to investigate such allegations and/or defend itself. While Presidio would strongly defend against any such short seller attacks, it may be constrained in the manner in which it can proceed against the relevant short seller by principles of freedom of speech, applicable state law or issues of commercial confidentiality. Such a situation could be costly and time-consuming and could distract Presidio management from growing its business. Even if such allegations are ultimately proven to be groundless, allegations against Presidio could severely impact its business operations, and any investment in the Presidio Class A Common Stock could be greatly reduced or even rendered worthless.
Presidio incurs, and will continue to incur, significant costs and devotes substantial management time as a result of operating as a public company, particularly after it is no longer an “emerging growth company.”
Presidio incurs significant legal, accounting and other expenses that PIH did not incur as a private company and EQV did not incur as a blank check company. For example, it is required to comply with certain of the requirements of the Sarbanes-Oxley Act and the Dodd-Frank Wall Street Reform and Consumer Protection Act, as well as rules and regulations subsequently implemented by the SEC, including the establishment and maintenance of effective disclosure and financial controls and changes in corporate governance practices. Presidio expects that it will incur significant legal and financial compliance costs to maintain compliance with these requirements, and these requirements may make some activities more time consuming and costly. In addition, Presidio management and other personnel may need to divert attention from operational and other business matters to devote substantial time to these public company requirements. In particular, it expects to incur significant expenses and devote substantial management effort towards ensuring compliance with the requirements of Section 404 of the Sarbanes-Oxley Act. Presidio may not be able to complete its evaluation, testing and any required remediation in a timely fashion. In that regard, Presidio anticipates that it may need to hire additional accounting and financial staff with appropriate public company experience and technical accounting knowledge.
However, for as long as Presidio remains an “emerging growth company” as defined in the JOBS Act, it intends to take advantage of certain exemptions from various reporting requirements that are applicable to other public companies that are not “emerging growth companies” including, but not limited to, not being required to comply with the auditor attestation requirements of Section 404 of the Sarbanes-Oxley Act, reduced disclosure obligations regarding executive compensation in its periodic reports and proxy statements, and exemptions from the requirements of holding a nonbinding advisory vote on executive compensation and shareholder approval of any golden parachute payments not previously approved.
Under the JOBS Act, “emerging growth companies” can delay adopting new or revised accounting standards until such time as those standards apply to private companies. Presidio has elected to continue to accept this exemption from new or revised accounting standards and, therefore, will not be subject to the same new or revised accounting standards as other public companies that are not “emerging growth companies.”
After Presidio is no longer an “emerging growth company,” it expects to incur additional management time and cost to comply with the more stringent reporting requirements, including complying with the auditor attestation requirements of Section 404 of the Sarbanes-Oxley Act.
Presidio cannot predict or estimate the amount of additional costs it may incur as a result of becoming a public company or the timing of such costs.
Certain members of Presidio’s management team have limited experience in operating a public company.
Presidio’s executive officers have limited experience in the management of a publicly traded company. Presidio’s management team may not successfully or effectively manage a public company that will be subject to significant regulatory oversight and reporting obligations under federal securities laws. Their limited experience in dealing with the increasingly complex laws pertaining to public companies may be a significant disadvantage in that it is likely that an increasing amount of their time may be devoted to these activities which will result in less time being devoted to the management and growth of Presidio. Presidio may not have adequate personnel with the appropriate level of knowledge, experience, and training in the accounting policies, practices or internal control over financial reporting required of public companies in the United States. The development and implementation of the standards and controls necessary for Presidio to achieve the level of accounting standards required of a public company in the United States may require costs greater than expected. It is possible that we will be required to expand our employee base and hire additional employees to support our operations as a public company which will increase our operating costs in future periods.
37
If we fail to develop or maintain an effective system of internal controls over financial reporting, we may not be able to report our financial results accurately and timely or prevent fraud, which may result in material misstatements in our financial statements or failure to meet our periodic reporting obligations. As a result, current and potential stockholders could lose confidence in our financial reporting, which would harm our business and the trading price of the Presidio Class A Common Stock.
We have not historically been required to complete, and have not completed, an assessment of the effectiveness of our internal controls over financial reporting, and our independent registered public accounting firm was not required to, and did not, conduct an audit of our internal controls over financial reporting as of December 31, 2025 or 2024. Our internal controls over financial reporting do not currently meet all the standards contemplated by Section 404 of SOX (“Section 404”). Accordingly, we cannot assure you that we have identified all, or that we will not in the future have additional, material weaknesses. If we are not able to implement the requirements of Section 404 in a timely manner or with adequate compliance at the time required, this may cause us to be unable to report on a timely basis and thereby subject us to adverse regulatory consequences, including sanctions by the SEC or violations of applicable stock exchange listing rules.
Our management is responsible for establishing and maintaining adequate internal control over financial reporting. Internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements in accordance with GAAP. A material weakness is a deficiency, or a combination of deficiencies, in internal control over financial reporting such that there is a reasonable possibility that a material misstatement of our annual or interim financial statements will not be prevented or detected on a timely basis.
Effective internal controls are necessary for us to provide reliable financial reports, prevent fraud and operate successfully as a public company. If we cannot provide reliable financial reports or prevent fraud, our reputation and operating results may be harmed. We cannot be certain that our efforts to develop and maintain our internal controls will be successful, that we will be able to maintain adequate controls over our financial processes and reporting in the future or that we will be able to comply with our obligations under Section 404. Any failure to develop or maintain effective internal controls, or difficulties encountered in implementing or improving our internal controls, could harm our operating results or cause us to fail to meet our reporting obligations. Ineffective internal controls could also cause investors to lose confidence in our reported financial information, which would likely have a negative effect on the trading price of the Presidio Class A Common Stock. Additional material weaknesses may be identified in the future. If we identify such issues or if we are unable to produce accurate and timely financial statements, the trading price of the Presidio Class A Common Stock may decline and we may be unable to maintain compliance with the NYSE listing standards.
Changes in tax laws or adverse outcomes resulting from examination of our income or other tax returns could adversely affect Presidio’s results of operations and financial condition.
Presidio is subject to taxes by U.S. federal, state and local tax authorities. Tax laws and regulations, or their interpretation, and administrative practices in various jurisdictions may be subject to change, which may or may not be retroactively applied. A change in any U.S. federal, state or local or foreign tax law, treaty, policy, statute, rule, regulation or ordinance, or in the interpretation thereof, in any jurisdiction in which Presidio or any of its subsidiaries operate, or are organized, could result in Presidio incurring a materially higher tax expense, which could also adversely impact its results of operations and financial condition. For example, from time to time, legislation has been proposed that, if enacted into law, would make significant changes to U.S. federal income tax laws affecting the oil and gas industry. Such proposed legislation has included, but has not been limited to, eliminating the immediate deduction for intangible drilling and development costs. No accurate prediction can be made as to whether any such legislative changes will be proposed or enacted in the future or, if enacted, what the specific provisions or the effective date of any such legislation would be. The elimination or postponement of certain U.S. federal income tax deductions currently available to oil and natural gas exploration and production companies, as well as any other changes to, or the imposition of new, U.S. federal, state, local or non-U.S. taxes (including the imposition of or increases in production, severance or similar taxes), could adversely affect Presidio’s operating results and financial condition. In addition, Presidio and its subsidiaries, including Prometheus Holdings, may be subject to audits of its income, sales and other taxes by U.S. federal, state, and local and foreign taxing authorities. Outcomes from these audits could have an adverse effect on Presidio’s operating results and financial condition. Furthermore, if the IRS makes audit adjustments to Prometheus Holdings’ income tax returns, it (and some states) may assess and collect any taxes (including any applicable penalties and interest) resulting from such audit adjustment directly from Prometheus Holdings. Any such audit adjustment and resulting payment of taxes, penalties and interest by Prometheus Holdings could materially and adversely affect Prometheus Holdings’ or Presidio’s operating results and financial condition.
38
USE OF PROCEEDS
We are filing the registration statement of which this prospectus is a part to permit the Selling Securityholders to resell Presidio common stock. We will not receive any proceeds from the sale of Presidio common stock to be offered by the Selling Securityholders pursuant to this prospectus.
We would receive up to an aggregate of approximately $136.7 million from the exercise of the Presidio Warrants and Series A Preferred Investor Warrants, assuming the exercise in full of all of the Presidio Warrants and Series A Preferred Investor Warrants for cash. We expect to use any net proceeds from the exercise of the Presidio Warrants and Series A Preferred Investor Warrants for general corporate purposes. We will have broad discretion over any use of proceeds from the exercise of the Presidio Warrants and Series A Preferred Investor Warrants. There is no assurance that the holders of the Presidio Warrants and Series A Preferred Investor Warrants will elect to exercise any or all of such warrants. The exercise price of the Presidio Warrants is $11.50 per share, and the exercise price of the Series A Preferred Investor Warrants is $0.01 per share. We believe the likelihood that warrant holders will exercise their Presidio Warrants and Series A Preferred Investor Warrants, and therefore the amount of cash proceeds that we would receive, is dependent upon the trading price of the Presidio Class A Common Stock. If the trading price for the Presidio Class A Common Stock continues to be less than $11.50 per share, we believe holders of Presidio Warrants will be unlikely to exercise their warrants. To the extent that the Presidio Warrants and Series A Preferred Investor Warrants are exercised on a “cashless basis,” the amount of cash we would receive from the exercise of such warrants will decrease.
39
SECURITIES MARKET INFORMATION
Market Information
The Presidio Class A Common Stock is currently listed on the New York Stock Exchange under the symbol “FTW.”
As of September 18, 2026, there were approximately 19 holders of record of Presidio common stock.
Dividend Policy
We currently expect to pay a dividend from available funds and future earnings on the Presidio Class A Common Stock, at the discretion of the Presidio Board and subject to compliance with contractual restrictions and covenants in the agreements governing our current and future indebtedness. While we paid a special cash dividend of $0.10125 per share of Presidio Class A Common Stock on May 18, 2026 and a quarterly cash dividend of $0.3375 per share of Presidio Class A Common Stock on September 14, 2026, future dividends are not guaranteed and may vary in amount or be discontinued at any time. Any determination to pay cash dividends will be at the discretion of the Presidio Board and will depend upon a number of factors, including Presidio’s results of operations, financial condition, future prospects, contractual restrictions, restrictions imposed by applicable law and other factors the Presidio Board deems relevant.
The Presidio Board will take into account:
| ● | general economic and business conditions; |
| ● | the Company’s financial condition and operating results; |
| ● | the Company’s free cash flow and current and anticipated cash needs; |
| ● | the Company’s capital requirements; |
| ● | legal, tax, regulatory and contractual (including under any credit facility entered into by the Company or its subsidiaries) restrictions and implications on the payment of dividends by the Company to its stockholders or by the Company’s subsidiaries to it; and |
| ● | such other factors as the Presidio Board may deem relevant. |
Presidio will not have a legal obligation to pay dividends at any rate or at all, and there is no guarantee that it will declare or pay cash dividends to its common stockholders. If Presidio does not have sufficient cash at the end of each quarter, it may, but is under no obligation to, borrow funds to pay the dividends established by its dividend policy to its common stockholders.
Furthermore, the amount of dividends Presidio would be able to pay in any quarter may be limited by the DGCL, which provides that a Delaware corporation may pay dividends only (i) out of the corporation’s surplus, which is defined as the excess, if any, of net assets (total assets less total liabilities) over capital, or (ii) if there is no surplus, out of the corporation’s net profit for the fiscal year in which the dividend is declared, or the preceding fiscal year. Based on current estimates of future production from our existing reserves at current prices, we estimate that we will be unable to sustain paying dividends at the anticipated initial level for periods beyond 2027.
From and including the original issuance date of March 4, 2026 to, but excluding, the third anniversary of the Closing on March 4, 2029 (the “Step Up Date”), the Series A Preferred Stock will accrue cumulative quarterly dividends on the then-current investment amount at a rate of 12.0% per annum. On and after the Step Up Date, the dividend rate will increase on a quarterly basis by 0.25% per annum until the rate reaches 16.0% per annum. Prior to the fifth anniversary of the Closing on March 4, 2031, dividends will be payable in cash at a rate of at least 8.0% per annum, with the remainder payable, at Presidio’s option, in cash or in kind in additional shares of Series A Preferred Stock. After the fifth anniversary of the Closing, all dividends will be payable in cash until all shares of Series A Preferred Stock have been redeemed. Dividends will be payable quarterly in arrears on February 28, May 31, August 31 and November 30 of each year and will accrue on a daily basis. The dividend rate will increase by 2.0% per annum if Presidio fails to pay a required cash dividend before the Step Up Date or upon the occurrence and during the continuance of certain trigger events, and will remain at such increased rate until the relevant event is cured.
From and after the original issuance date of any shares of Series B Preferred Stock, the holders of the Series B Preferred Stock will be entitled to receive dividends when, as and if declared by the board of directors of Presidio and as otherwise provided in Presidio’s amended and restated certificate of incorporation, out of funds legally available therefor. If Presidio declares, pays or sets apart any dividend or other distribution on its common stock, Presidio will simultaneously declare, pay and/or set apart for payment or distribution for each share of Series B Preferred Stock a dividend and/or distribution in an amount equal to the amount the holder of the Series B Preferred Stock would be entitled to receive if the holder had converted the Series B Preferred Stock into common stock and had held such shares of common stock on the record date for such dividends and distributions. Payments will be made concurrently with the dividend or distribution to the holders of common stock. The Series B Preferred Stock ranks junior to the Series A Preferred Stock as to the payment of any dividends by Presidio.
40
UNAUDITED PRO FORMA CONDENSED COMBINED FINANCIAL STATEMENTS
Introduction
Presidio Production Company (“Presidio”, the “Company”) is providing the following unaudited pro forma condensed combined financial information to aid Presidio’s stockholders in their analysis of the financial aspects of the Business Combination, EQVR Acquisition and Arkoma Acquisition on the historical financial statements of Presidio Production Company (the “Company” or “Presidio”). The unaudited pro forma condensed combined financial information has been prepared in accordance with Article 11 of Regulation S-X.
The unaudited pro forma condensed combined balance sheet as of June 30, 2026 gives effect to the Arkoma Acquisition as if it had been consummated on June 30, 2026. The Company omitted the pro forma balance sheet reflecting the Business Combination and EQVR Acquisition because the impact is already reflected in the Company’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2026.
The unaudited pro forma condensed combined statements of operations for the six months ended June 30, 2026 and for the year ended December 31, 2025 give effect to the Business Combination, EQVR Acquisition and Arkoma Acquisition as if each had been consummated on January 1, 2025, the beginning of the earliest period presented.
The unaudited pro forma condensed combined financial information has been prepared by Presidio in accordance with accounting principles generally accepted in the United States of America (“US GAAP”).
This information should be read together with (i) the Company’s unaudited condensed consolidated financial statements and related notes for the quarterly period ended June 30, 2026, (ii) the audited consolidated financial statements of Presidio Investment Holdings LLC (“PIH” or the “Predecessor”) as of and for the year ended December 31, 2025, (iii) the audited financial statements of EQV Resources LLC (“EQVR”) as of and for the year ended December 31, 2025, (iv) the audited combined statement of revenues and direct operating expenses of the Arkoma Acquired Properties for the year ended December 31, 2025 and (v) the unaudited combined statement of revenues and direct operating expenses of the Arkoma Acquired Properties for the six months ended June 30, 2026, in each case, included elsewhere in this prospectus.
Description of the Business Combination and EQVR Acquisition
On March 4, 2026 (the “Closing Date”), Presidio Production Company (f/k/a Presidio PubCo Inc.), a Delaware corporation (the “Company”) consummated the previously announced business combination (the “Closing”) pursuant to the Business Combination Agreement, dated August 5, 2025 (the “Business Combination Agreement”), by and among EQV Ventures Acquisition Corp., a Cayman Islands exempted company (“EQV”), the Company, Prometheus PubCo Merger Sub Inc., a Delaware corporation (“EQV Merger Sub”), Prometheus Holdings LLC, a Delaware limited liability company (“EQV Holdings”), Prometheus Merger Sub LLC, a Delaware limited liability company (“Presidio Merger Sub”) and Presidio Investment Holdings LLC, a Delaware limited liability company (“PIH”). The transactions contemplated by the Business Combination Agreement are collectively referred to herein as the “Business Combination.” The Business Combination Agreement and related transactions were approved at an extraordinary general meeting of EQV’s shareholders held on February 27, 2026 (the “Extraordinary General Meeting”).
Pursuant to the Business Combination Agreement, on the Closing Date,
| (i) | EQV changed its jurisdiction of incorporation by deregistering as a Cayman Islands exempted company and registering by way of continuation and domesticating as a corporation incorporated under the laws of the State of Delaware, upon which (i) each then issued and outstanding Class A ordinary share of EQV, par value $0.0001 per share (the “Class A Shares”), held by the public (the “Public Class A Shares”) was automatically converted, on a one-for-one basis, into a share of Class A common stock, par value $0.0001 per share, of EQV (the “Presidio Midco Class A Common Stock”), (ii) each then issued and outstanding Class B ordinary share of EQV, par value $0.0001 per share (the “Class B Shares”) was automatically converted, on a one-for-one basis, into a share of Class B common stock, par value $0.0001 per share, of EQV (the “Presidio Midco Class B Common Stock” and, together with the Presidio Midco Class A Common Stock, the “Presidio Midco Common Stock”), (iii) each then issued and outstanding warrant to purchase one Class A Share at a price of $11.50 per share (the “EQV Warrants”) held by the public (the “EQV Public Warrants”) was automatically converted, on a one-for-one basis, into a whole warrant exercisable for one share of Presidio Midco Class A Common Stock at a price of $11.50 per share (the “Presidio Midco Warrants”), (iv) each then issued and outstanding unit (the “EQV Units”) held by the public (the “EQV Public Units”), each consisting of one Public Class A Share and one-third of one EQV Public Warrant, and each then issued and outstanding EQV Unit held by EQV Ventures Sponsor LLC, a Delaware limited liability company (the “Sponsor”) and BTIG, LLC, the underwriter in EQV’s initial public offering (the “EQV Private Units”), each consisting of one Class A Share and one third of one EQV Warrant (the “EQV Private Warrants”), was cancelled and each holder of EQV Units became entitled to receive one share of Presidio Midco Class A Common Stock and one-third of one Presidio Midco Warrant, and (v) the name of EQV changed from “EQV Ventures Acquisition Corp.” to “Presidio MidCo Inc.” (the “Domestication”); and |
41
| (ii) | following the Domestication, EQV Merger Sub merged with and into EQV (the “Merger”), with EQV surviving the Merger as a wholly owned subsidiary of the Company (the “EQV Surviving Subsidiary”), and pursuant to which (i) each then issued and outstanding share of Presidio Midco Common Stock was automatically converted, on a one for one basis, into shares of Class A common stock, par value $0.0001 per share, of the Company (the “Presidio Class A Common Stock”), (ii) each then issued and outstanding Presidio Midco Warrant was automatically converted, on a one-for-one basis, into a whole warrant exercisable for one share of Presidio Class A Common Stock at a price of $11.50 per share (the “Presidio Warrants”) and (iii) the Company changed its name to “Presidio Production Company” and received a managing member interest in EQV Holdings. Following the Merger, Presidio Merger Sub merged with and into PIH, with PIH as the surviving company in the Merger, all on the terms and subject to the conditions set forth in the Business Combination Agreement and in accordance with applicable law. |
On the Closing Date, (i) the Company contributed to EQV Surviving Subsidiary all of its assets and liabilities (excluding its interest in EQV Surviving Subsidiary), (ii) in exchange therefor, EQV Surviving Subsidiary issued to the Company (a) 27,652,068 common shares of EQV Surviving Subsidiary (“EQV Surviving Subsidiary Common Shares”), which is equal to the number of total shares of Presidio Class A Common Stock issued and outstanding immediately after the Closing, (b) 125,000 Class A preferred shares of EQV Surviving Subsidiary (the “EQV Surviving Subsidiary Preferred Shares”), which is equal to the number of the Company’s Series A perpetual preferred shares, each having a stated value of $1,000 per preferred share (the “Series A Preferred Shares”), outstanding and (c) 11,887,469 warrants to purchase EQV Surviving Subsidiary Common Shares, which is equal to the number of the Presidio Warrants outstanding immediately after the Closing, (iii) EQV Surviving Subsidiary then contributed to EQV Holdings all of its assets and liabilities (excluding its interests in EQV Holdings and the shares redeemed), including cash held by EQV Surviving Subsidiary, and (iv) in exchange therefor, EQV Holdings issued to EQV Surviving Subsidiary (a) 27,652,068 common units of EQV Holdings (“EQV Holdings Common Units”), equal to the number of total shares of Presidio Class A Common Stock issued and outstanding immediately after the Closing, (b) 125,000 Class A preferred units of EQV Holdings, which is equal to the number of EQV Surviving Subsidiary Preferred Shares outstanding and (c) 11,887,469 warrants to purchase EQV Holdings Common Units, which is equal to the number of Presidio Warrants outstanding immediately after the Closing.
Also on the Closing Date, the Company acquired all of the issued and outstanding equity interests of EQV Resources LLC, a Delaware limited liability company (“EQVR”), via merger (the “EQVR Merger”) pursuant to, and upon the terms and subject to the conditions set forth in, the agreement and plan of merger, dated as of August 5, 2025, by and among EQV, the Company, EQVR Merger Sub LLC, a Delaware limited liability company and a direct wholly owned subsidiary of the Company (“EQVR Merger Sub”), EQVR, EQV Resources Intermediate LLC, a Delaware limited liability company (“EQVR Intermediate”) and PIH (the “EQVR Merger Agreement”).
Holders of EQV Holdings Common Units (other than the Company) have the right (an “exchange right”), subject to certain limitations, to exchange interests of the Company (each interest consisting of one EQV Holdings Common Unit and one share of Class B common stock, par value $0.0001 per share (the “Presidio Class B Common Stock”), of the Company (the “Company Interests”)) for, at the Company’s option, (i) shares of Presidio Class A Common Stock on a one-for-one basis, subject to adjustment for stock splits, stock dividends, reorganizations, recapitalizations and the like, or (ii) a corresponding amount of cash. The Company’s decision to make a cash payment or issue shares upon an exercise of an exchange right will be made by the Company’s independent directors.
Holders of EQV Holdings Common Units (other than the Company) are generally permitted to exercise the exchange right on a quarterly basis, subject to certain de minimis allowances. In addition, additional exchanges may occur in connection with certain specified events, and any exchanges involving more than a specified number of EQV Holdings Common Units (subject to the Company’s discretion to permit exchanges of a lower number of Company Interests) may occur at any time with advanced notice. The exchange rights are subject to certain limitations and restrictions intended to reduce the administrative burden of exchanges upon the Company and ensure that EQV Holdings will continue to be treated as a partnership for U.S. federal income tax purposes.
42
Concurrently with the execution of the Business Combination Agreement, on August 5, 2025, EQV and the Company entered into subscription agreements (each, a “Subscription Agreement”) with certain investors (the “PIPE Investors”) pursuant to which, among other things, the PIPE Investors subscribed for and purchased an aggregate of 8,750,000 shares of Presidio Class A Common Stock issued by the Company following the Domestication for a purchase price of $10.00 per share, on the terms and subject to the conditions set forth therein (the “PIPE Financing”). Each Subscription Agreement contains customary representations and warranties of EQV and the Company, on the one hand, and the PIPE Investor, on the other hand. At the Closing, the Company issued an aggregate of 8,750,000 shares of Presidio Class A Common Stock to the PIPE Investors.
Concurrently with the execution of the Business Combination Agreement, on August 5, 2025, EQV, the Company and PIH entered into a Series A Preferred Securities Purchase Agreement (the “Series A Securities Purchase Agreement”) with certain investors (the “Series A Preferred Investors”), pursuant to which the Series A Preferred Investors purchased in a private placement from the Company an aggregate of 125,000 Series A Preferred Shares and warrants to purchase 937,500 shares of Presidio Class A Common Stock with an exercise price of $0.01 per warrant (the “Preferred Investor Warrants”) for a cash purchase price of $123,750,000 (net of all applicable original issue discounts) (the “Series A Preferred Financing”). The Series A Preferred Shares have the rights, preferences, and privileges set forth in the Company’s Certificate of Designation of Preferences, Rights and Limitations of Series A Perpetual Preferred Stock (the “Series A Certificate of Designation”), and certain holders of the Series A Preferred Shares have certain rights pursuant to the agreement between certain Series A Preferred Investors and the Company entered into at the Closing (the “Series A Preferred Stockholders’ Agreement”).
At the Closing, each Series A Preferred Investor received Series A Preferred Shares and Preferred Investor Warrants to purchase a specified number of shares of Presidio Class A Common Stock, as set forth in the Series A Securities Purchase Agreement. In addition, the Company entered into the Series A Preferred Stockholders’ Agreement with certain Series A Preferred Investors at the Closing. The Preferred Investor Warrants have an exercise price of $0.01, subject to adjustment as provided therein, and may be exercised for cash or on a cashless basis. The Preferred Investor Warrants will become exercisable in two tranches, with 50% exercisable six months following the Closing and 50% exercisable 12 months following the Closing, and have a term of exercise equal to five years from the applicable exercise date, as provided further in the Preferred Investor Warrants. The Company shall use commercially reasonable efforts to file a resale registration statement within 45 days following the Closing to register the Presidio Class A Common Stock underlying the Preferred Investor Warrants, subject to certain conditions.
The Series A Securities Purchase Agreement contains customary representations and warranties by EQV, PIH, and the Series A Preferred Investors, including with respect to organization, authority, enforceability, compliance with laws, absence of conflicts, and the validity of the Series A Preferred Shares and Preferred Investor Warrants. In addition, subject to certain conditions, so long as any Series A Preferred Shares remain outstanding, the Series A Certificate of Designation will provide holders of a majority of the then issued and outstanding Series A Preferred Shares the right to elect one Series A Director (as defined therein) and, in certain circumstances, two additional Preferred Stock Directors (as defined therein).
In connection with the Business Combination, contemporaneously with the execution and delivery of the Business Combination Agreement, EQV, EQV Holdings, PIH, certain existing investors and certain unitholders of PIH (the “PIH Rollover Holders”) entered into those certain rollover agreements, dated as of August 5, 2025 (each, a “Rollover Agreement”, and collectively, the “Rollover Agreements”), pursuant to which the Class A ParentCo Rollover Units (as defined in the Rollover Agreement) of such PIH Rollover Holders converted into the right to receive a number of EQV Holdings Common Units and a number of shares of Presidio Class B Common Stock at par value (the “Rollovers”). In addition, in connection with the Business Combination, contemporaneously with the execution and delivery of the Business Combination Agreement, EQV, the Company, the Sponsor, certain PIH Rollover Holders and certain PIPE Investors party thereto entered into Securities Contribution and Transfer Agreements (the “Securities Contribution and Transfer Agreements”) in order to reflect the intended ownership interests of the shareholders of the Company following the Business Combination. Pursuant to and subject to the terms and conditions of the Securities Contribution and Transfer Agreements, (i) Sponsor agreed to contribute 562,746 Class B Shares to EQV as a contribution to capital at Closing and, in exchange, Presidio agreed to issue 562,746 shares of Presidio Class A Common Stock (or securities convertible into Presidio Class A Common Stock) to the PIH Rollover Holders (the “PIH Rollover Share Contributions”) and (ii) Sponsor agreed to contribute 565,217 Class B Shares to EQV as a contribution to capital at Closing and, in exchange, Presidio agreed to issue 565,217 shares of Presidio Class A Common Stock to such PIPE Investors (the “PIPE Share Contributions”).
43
In connection with the Extraordinary General Meeting, on February 23, 2026, EQV and the Sponsor entered into a non-redemption agreement (the “Non-Redemption Agreement”) with Fort Baker Capital Management LP (“Fort Baker”), pursuant to which Fort Baker agreed not to redeem (or to validly rescind any redemption requests on) up to 751,880 Class A Shares in connection with the Extraordinary General Meeting. In exchange for the foregoing commitment not to redeem such Class A Shares of EQV, the Sponsor agreed to assign to Fort Baker, for no additional consideration, up to 117,686 Class A Shares. Fort Baker reversed redemption on the maximum number of shares provided for by the Non-Redemption Agreement and the Sponsor assigned the maximum number of Class A Shares provided for by the Non-Redemption Agreement. The Non-Redemption Agreement increased the amount of funds remaining in EQV’s trust account following the Extraordinary General Meeting relative to the amount of funds that would have been expected to be remaining in the trust account following the Extraordinary General Meeting had the Non-Redemption Agreement not been entered into and the Class A Shares subject to such agreements had been redeemed.
In connection with the Business Combination, on February 23, 2026, EQV, Presidio and PIH entered into a Series B Preferred Securities Purchase Agreement (the “Series B Securities Purchase Agreement”) with Adage Capital Partners, L.P. (the “Series B Preferred Investor”), pursuant to which, immediately prior to or substantially concurrently with the Closing, the Series B Preferred Investor purchased in a private placement from Presidio an aggregate of 27,173 shares of Series B Perpetual Participating Convertible Preferred Stock of Presidio PubCo Inc., par value $0.0001 per share (the “Series B Preferred Shares”), with each Series B Preferred Share convertible into 100 shares of Presidio Class A Common Stock and entitled to participate in dividends declared on shares of Presidio Class A Common Stock on an as-converted basis, for an aggregate cash purchase price of $25,000,000 (the “Series B Preferred Financing”). The Series B Preferred Shares have the rights, preferences, and privileges set forth in Presidio’s Certificate of Designation of Preferences, Rights and Limitations of Series B Perpetual Participating Convertible Preferred Stock (the “Series B Certificate of Designation”).
The Series B Securities Purchase Agreement contains customary representations and warranties by EQV, Presidio, PIH, and the Series B Preferred Investor, including with respect to organization, authority, enforceability, compliance with laws, absence of conflicts, and the validity of the Series B Preferred Shares issued. Presidio shall use commercially reasonable efforts to register the Presidio Class A Common Stock issuable upon conversion of the Series B Preferred Shares on a resale registration statement within 45 days following the Closing.
The Public Class A Shares, EQV Public Warrants and EQV Public Units were listed on the New York Stock Exchange (the “NYSE”) under the symbols “FTW,” “FTW WS” and “FTW U,” respectively, and were voluntarily delisted from the NYSE on March 5, 2026, in connection with the Closing. The Presidio Class A Common Stock and Presidio Warrants commenced trading on the NYSE under the symbols “FTW” and “FTW WS,” respectively, on March 4, 2026. As of the Closing Date, the Company is organized in an “Up-C” structure, such that the Company and the subsidiaries of the Company hold and operate substantially all of the assets and business of PIH, and the Company is a publicly listed holding company that holds equity interests in PIH.
In connection with the Business Combination and EQVR Acquisition, on March 4, 2026, Presidio Borrower LLC, a wholly owned subsidiary of the Company (“Presidio Borrower”), entered into a senior secured revolving credit agreement (the “Credit Agreement”) among Presidio Borrower, as borrower, Citizens Bank, N.A., as administrative agent, and the lenders from time to time party thereto. The Credit Agreement provides for, as of the closing date of the Credit Agreement, aggregate commitments of $65.0 million, an initial borrowing base of $65.0 million and aggregate maximum credit amounts of $500.0 million. Presidio Borrower drew $37.0 million of the initial borrowing base on March 4, 2026 (the “RBL Financing”) and used the proceeds to fund a portion of the Business Combination and EQVR Acquisition. The borrowing base under the Credit Agreement is scheduled to be redetermined semiannually on or about May 1 and November 1 of each calendar year, commencing on or about May 1, 2026, and is subject to additional adjustments from time to time pursuant to the provisions of the Credit Agreement, including for certain asset sales and the elimination or reduction of hedge positions. Additionally, each of Presidio Borrower and the Required Lenders (as defined in the Credit Agreement) may request one unscheduled redetermination of the borrowing base between each scheduled redetermination. The amount of the borrowing base is determined by the lenders in their sole discretion and consistent with the oil and gas lending criteria of the lenders at the time of the relevant redetermination. The amount Presidio Borrower is able to borrow under the Credit Agreement is subject to compliance with the financial covenants, satisfaction of various conditions precedent to borrowing and other provisions of the Credit Agreement. The Credit Agreement has a scheduled maturity of four years from the effective date thereof. Borrowings under the Credit Agreement may be base rate loans or SOFR loans. Interest is payable quarterly for base rate loans and at the end of the applicable interest period for SOFR loans. SOFR loans bear interest at Term SOFR plus an applicable margin ranging from 300 to 400 basis points, depending on the percentage of the borrowing base utilized. Base rate loans bear interest at a rate per annum equal to the greatest of: (i) the prime rate announced by Citizens Bank, N.A. or its parent; (ii) the federal funds effective rate plus 50 basis points; and (iii) the Term SOFR rate for a one-month interest period plus 100 basis points, plus an applicable margin ranging from 200 to 300 basis points, depending on the percentage of the borrowing base utilized. Presidio Borrower also pays a commitment fee on unused elected commitment amounts under its facility of 50 basis points. Presidio Borrower may repay any amounts borrowed under the Credit Agreement prior to the maturity date without any premium or penalty (other than customary breakage costs).
44
Sponsor Letter Agreement
Concurrently with the execution of the Business Combination Agreement, on August 5, 2025, EQV, the Sponsor, Presidio, EQV Holdings, PIH and the Insiders entered into the Sponsor Letter Agreement, pursuant to which (a) each of the Sponsor and the Insiders agreed to vote in favor of the Business Combination Agreement and the Business Combination, (b) each of the Sponsor and the Insiders agreed to be bound by certain restrictions on transfer with respect to their equity interests in EQV prior to Closing, (c) the Sponsor agreed to be bound by certain lock-up provisions during the post-Closing lock-up periods described therein with respect to its equity interests in EQV, (d) the Sponsor agreed to subject certain of its Class B Shares to vesting (or forfeiture) on the basis of achieving certain trading price thresholds during the first five years following the Closing pursuant to an earnout program, (e) the Sponsor agreed to subject certain of its Class B Shares to time vesting during the first three years following the Closing pursuant to a dividend reinvestment program and (f) the Sponsor and the Insiders agreed to waive any adjustment to the conversion ratio set forth in the respective governing documents of any of EQV, Presidio, EQV Merger Sub, EQV Holdings, and Presidio Merger Sub or any other anti-dilution or similar protection with respect to any equity interests in EQV, as more fully set forth in the Sponsor Letter Agreement.
Pursuant to the Sponsor Letter Agreement, 1,851,161 Class B Shares held by the Sponsor will be subject to forfeiture, and vest in two equal 50% increments if, over any 20 trading days within any 30 consecutive trading-day period during the five years following the Closing, the trading share price of the Presidio Class A Common Stock is greater than or equal to $12.50 per share and $15.00 per share, respectively (or if Presidio consummates a sale that would value such shares at the aforementioned thresholds).
Pursuant to the Sponsor Letter Agreement, immediately following the Closing, 3,702,323 Class B Shares held by the Sponsor, as may be adjusted for stock splits, stock dividends, reorganizations, recapitalizations and the like or exchanged for Presidio Class A Common Stock pursuant to the Business Combination Agreement and any newly issued Presidio Class A Common Stock resulting from dividends owed to the Sponsor pursuant to the terms of the Sponsor Letter Agreement, will vest in three tranches, with one-third of such shares vesting on the date that is 12 months following the Closing, one-half of the remainder of such shares vesting on the date that is 24 months following the Closing and the remaining of such shares vesting on the date that is 36 months following the Closing.
Sponsor and the Insiders also agreed to be bound by certain “lock-up” provisions. Pursuant to the terms and conditions of the Sponsor Letter Agreement, 1,851,161 of the Sponsor’s equity interests in EQV will be restricted from transfer for a period ending on the earlier of the date (i) that is 12 months following the Closing Date and (ii) upon which Presidio completes a liquidation, merger, share exchange or other similar transaction following the Closing Date that results in all the equityholders of Presidio having the right to exchange their shares of Presidio Class A Common Stock for cash, securities or other property, subject to customary exceptions and potential early-release 150 days after the Closing based on the stock price sustaining specified price thresholds for 20 trading days within any 30 consecutive trading-day period.
Subscription Agreements
Concurrently with the execution of the Business Combination Agreement, on August 5, 2025, EQV and the Company entered into subscription agreements (each, a “Subscription Agreement”) with certain investors (the “PIPE Investors”) pursuant to which, among other things, the PIPE Investors subscribed for and purchased an aggregate of 8,750,000 shares of Presidio Class A Common Stock to be issued by the Company following the Domestication for a purchase price of $10.00 per share, on the terms and subject to the conditions set forth therein (the “PIPE Financing”). Each Subscription Agreement contains customary representations and warranties of EQV and the Company, on the one hand, and the PIPE Investor, on the other hand. At the Closing, the Company issued an aggregate of 8,750,000 shares of Presidio Class A Common Stock to the PIPE Investors. Concurrently with the execution of the Business Combination Agreement, on August 5, 2025, EQV and Presidio entered into Subscription Agreements with the PIPE Investors (and may enter into, before the Closing, additional agreements with additional PIPE Investors on the same forms, as applicable) pursuant to which, among other things, the PIPE Investors have agreed to subscribe for and purchase, and EQV and Presidio have agreed to issue and sell to the PIPE Investors, an aggregate of 8,750,000 shares of Presidio Class A Common Stock following the Domestication for a purchase price of $10.00 per share, on the terms and subject to the conditions set forth therein. Each Subscription Agreement contains customary representations and warranties of EQV and Presidio, on the one hand, and the PIPE Investor, on the other hand, and customary conditions to closing, including the consummation of the Business Combination immediately following the consummation of the PIPE Financing.
45
Preferred Investment
Concurrently with the execution of the Business Combination Agreement, on August 5, 2025, EQV, the Company and PIH entered into a Series A Preferred Securities Purchase Agreement (the “Series A Securities Purchase Agreement”) with certain investors (the “Series A Preferred Investors”), pursuant to which the Series A Preferred Investors purchased in a private placement from the Company an aggregate of 125,000 Series A Preferred Shares (the “Series A Preferred Shares”) and warrants to purchase 937,500 shares of Presidio Class A Common Stock with an exercise price of $0.01 per warrant (the “Series A Preferred Investor Warrants”) for a cash purchase price of $123,750,000 (net of all applicable original issue discounts) (the “Series A Preferred Financing”). The Series A Preferred Shares have the rights, preferences, and privileges set forth in the Company’s Certificate of Designation of Preferences, Rights and Limitations of Series A Perpetual Preferred Stock (the “Certificate of Designation”), and certain holders of the Series A Preferred Shares have certain rights pursuant to the agreement between certain Series A Preferred Investors and the Company entered into at the Closing (the “Series A Preferred Stockholders’ Agreement”).
At the Closing, each Series A Preferred Investor received Series A Preferred Shares and Series A Preferred Investor Warrants to purchase a specified number of shares of Presidio Class A Common Stock, as set forth in the Series A Securities Purchase Agreement. In addition, the Company entered into the Series A Preferred Stockholders’ Agreement with certain Series A Preferred Investors at the Closing. The Series A Preferred Investor Warrants have an exercise price of $0.01, subject to adjustment as provided therein, and may be exercised for cash or on a cashless basis. The Series A Preferred Investor Warrants will become exercisable in two tranches, with 50% exercisable six months following the Closing and 50% exercisable 12 months following the Closing, and have a term of exercise equal to five years from the applicable exercise date, as provided further in the Series A Preferred Investor Warrants. The Company shall use commercially reasonable efforts to file a resale registration statement within 45 days following the Closing to register the Presidio Class A Common Stock underlying the Series A Preferred Investor Warrants, subject to certain conditions.
The Series A Securities Purchase Agreement contains customary representations and warranties by EQV, PIH, and the Series A Preferred Investors, including with respect to organization, authority, enforceability, compliance with laws, absence of conflicts, and the validity of the Series A Preferred Shares and Series A Preferred Investor Warrants. In addition, subject to certain conditions, so long as any Series A Preferred Shares remain outstanding, the Certificate of Designation will provide holders of a majority of the then issued and outstanding Series A Preferred Shares the right to elect one Series A Director (as defined therein) and, in certain circumstances, two additional Preferred Stock Directors (as defined therein).
In connection with the Business Combination, on February 23, 2026, EQV, Presidio and PIH entered into a Series B Preferred Securities Purchase Agreement (the “Series B Securities Purchase Agreement”) with Adage Capital Partners, L.P. (the “Series B Preferred Investor”), pursuant to which, immediately prior to or substantially concurrently with the Closing, the Series B Preferred Investor purchased in a private placement from Presidio an aggregate of 27,173 Series B Perpetual Participating Convertible Preferred Stock of Presidio PubCo Inc., par value $0.0001 per share (the “Series B Preferred Shares”), with each Series B Preferred Share convertible into 100 shares of Presidio Class A Common Stock and entitled to participate in dividends declared on shares of Presidio Class A Common Stock on an as-converted basis, for an aggregate cash purchase price of $25,000,000 (the “Series B Preferred Financing”). The Series B Preferred Shares have the rights, preferences, and privileges set forth in Presidio’s Certificate of Designation of Preferences, Rights and Limitations of Series B Perpetual Participating Convertible Preferred Stock (the “Series B Certificate of Designation”).
The Series B Securities Purchase Agreement contains customary representations and warranties by EQV, Presidio, PIH, and the Series B Preferred Investor, including with respect to organization, authority, enforceability, compliance with laws, absence of conflicts, and the validity of the Series B Preferred Shares issued. Presidio shall use commercially reasonable efforts to register the Presidio Class A Common Stock issuable upon conversion of the Series B Preferred Shares on a resale registration statement within 45 days following the Closing.
Rollover Agreement
In connection with the Business Combination, contemporaneously with the execution and delivery of the Business Combination Agreement, EQV, EQV Holdings, PIH, certain existing investors and certain unitholders of PIH (the “PIH Rollover Holders”) entered into those certain rollover agreements, dated as of August 5, 2025 (each, a “Rollover Agreement”, and collectively, the “Rollover Agreements”), pursuant to which the Class A ParentCo Rollover Units (as defined in the Rollover Agreement) of such PIH Rollover Holders converted into the right to receive a number of EQV Holdings Common Units and a number of shares of Presidio Class B Common Stock at par value (the “Rollovers”). In addition, in connection with the Business Combination, contemporaneously with the execution and delivery of the Business Combination Agreement, EQV, the Company, the Sponsor, certain PIH Rollover Holders and certain PIPE Investors party thereto entered into Securities Contribution and Transfer Agreements (the “Securities Contribution and Transfer Agreements”) in order to reflect the intended ownership interests of the shareholders of the Company following the Business Combination. Pursuant to and subject to the terms and conditions of the Securities Contribution and Transfer Agreements, (i) Sponsor agreed to contribute 562,746 Class B Shares to EQV as a contribution to capital at Closing and, in exchange, Presidio agreed to issue 562,746 shares of Presidio Class A Common Stock (or securities convertible into Presidio Class A Common Stock) to the PIH Rollover Holders (the “PIH Rollover Share Contributions”) and (ii) Sponsor agreed to contribute 565,217 Class B Shares to EQV as a contribution to capital at Closing and, in exchange, Presidio agreed to issue 565,217 shares of Presidio Class A Common Stock to such PIPE Investors (the “PIPE Share Contributions”).
46
In connection with the Business Combination, contemporaneously with the execution and delivery of the Series B Preferred Purchase Agreement, EQV, the Company, the Sponsor and PIH entered into a Forfeiture Agreement (the “Series B Forfeiture Agreement”) in order to reflect the intended ownership interests of the shareholders of the Company following the Business Combination. Pursuant to and subject to the terms and conditions of the Series B Forfeiture Agreement, Sponsor agreed to contribute 217,391 Class B Shares to EQV as a contribution to capital at Closing and, in exchange, Presidio agreed to reserve 217,300 shares of Presidio Class A Common Stock to such Series B Preferred Investor.
In connection with the public share redemptions, EQV, the Company, the Sponsor and PIH entered into a Non-Redemption Agreement (the “Non-Redemption Agreement”) with a certain Public Class A Shareholder (the “NRA Public Investor”) where the NRA Public Investor agreed to not exercise their right to redeem Class A Shares. Contemporaneously with the execution and delivery of the Non-Redemption Agreement, EQV, the Company, the Sponsor and PIH entered into a Forfeiture Agreement (the “NRA Forfeiture Agreement”) in order to reflect the intended ownership interests of the shareholders of the Company following the Business Combination. Pursuant to and subject to the terms and conditions of the NRA Forfeiture Agreement, Sponsor agreed to contribute 117,686 Class A Shares to EQV as a contribution to capital at Closing and, in exchange, Presidio agreed to issue 117,686 shares of Presidio Class A Common Stock to such NRA Public Investor.
Agreement and Plan of Merger
In connection with the Business Combination, EQV and PIH negotiated the acquisition of all of the issued and outstanding equity interests of EQVR via merger and, contemporaneous with the execution of the Business Combination Agreement, EQV, Presidio, EQVR Merger Sub, EQVR Intermediate, EQVR and PIH entered into the EQVR Merger Agreement, pursuant to which Presidio will effect the EQVR Acquisition on the terms and subject to the conditions set forth in the EQVR Merger Agreement and in accordance with applicable law following the Closing.
Registration and Stockholders’ Rights Agreement
In connection with Closing, the Registration Rights Parties, EQV, EQV Holdings, and Presidio will enter into the Registration and Stockholders’ Rights Agreement. Under the Registration and Stockholders’ Rights Agreement, Sponsor or its permitted transferees will have the right to designate two directors so long as they own in the aggregate greater than 20% of Presidio’s common equity and one director so long as they own in the aggregate greater than 10% of Presidio’s common equity.
Pursuant to the terms of the Registration and Stockholders’ Rights Agreement, the Registration Rights Parties will be granted certain customary registration rights, including demand and piggyback rights. In addition, certain of the Registration Rights Parties will agree, subject to the terms provided therein, that each such party will not transfer any of its registrable securities under the Registration and Stockholders’ Rights Agreement for a period ending 180 days after the Closing.
Amended and Restated Limited Liability Company Agreement
The Public Class A Shares, EQV Public Warrants and EQV Public Units were listed on the New York Stock Exchange (the “NYSE”) under the symbols “FTW,” “FTW WS” and “FTW U,” respectively, and were voluntarily delisted from the NYSE on March 5, 2026, in connection with the Closing. As of the Closing Date, the Company is organized in an “Up-C” structure, such that the Company and the subsidiaries of the Company hold and operate substantially all of the assets and business of PIH, and the Company is a publicly listed holding company that holds equity interests in PIH.
Arkoma Acquisition
Pursuant to seven Purchase and Sale Agreements, each dated May 7, 2026 (collectively, the “Purchase and Sale Agreements”), the Company acquired oil and gas leases, oil, gas, and mineral leases and subleases, carried interests, operating rights, record title interests, overriding royalty interests and other interests to the crude oil, gas, casinghead gas, condensate, natural gas liquids, and other gaseous or liquid hydrocarbons that may be produced from or are otherwise attributable to certain properties in Oklahoma (the “Arkoma Acquired Properties,” and the acquisitions of the Properties, the “Arkoma Acquisition”), from Canyon Creek Energy – Arkoma, LLC (“CCE”), Alchemist Energy Leaseco, LP (“Alchemist”), Pivotal Arkoma Basin II, LLC (“Pivotal”), Harvard Petroleum Company, LLC (“Harvard”), Harbor Island, LLC (“Harbor Island”), FBF Energy, LLC (“FBF”) and East Dennis Oil Company, LLC (“East Dennis”). Six of the acquisitions closed on July 1, 2026 and the Harbor Island acquisition closed on July 21, 2026.
Aggregate purchase consideration consisted of cash of $53.1 million and equity interests with a fair value of $24.0 million, together with capitalized transaction costs of $5.2 million, for total cost of acquisition of $82.3 million.
In connection with the Arkoma Acquisition, on July 1, 2026, Presidio Acquisitions LLC, as borrower (the “Borrower”), and Presidio Intermediate Holding Company II LLC, as a guarantor, each an indirect wholly owned subsidiary of the Company, entered into a Loan and Security Agreement with Goldman Sachs Bank USA, as administrative agent and collateral agent, Goldman Sachs Bank USA and Citizens Bank, N.A., as joint lead arrangers, and the lenders party thereto, providing for a senior secured warehouse credit facility with aggregate commitments of up to $1.0 billion, consisting of an initial $55.0 million closing date loan commitment and $945.0 million of delayed draw loan commitments. The Borrower drew the full $55.0 million closing date loan commitment on July 1, 2026 (the “Warehouse Financing”) and used the proceeds to fund a portion of the Arkoma Acquisition. The closing date loans mature on the third anniversary of the closing date. Borrowings bear interest, at the Borrower’s election, at a base rate or Term SOFR plus an applicable margin, initially 3.00% for Term SOFR loans and 2.00% for base rate loans, increasing to 4.00% and 3.00% in months 13 through 24 following the funding date and to 5.00% and 4.00% thereafter. The Loan Agreement also provides for upfront, administrative and duration fees, requires specified commodity and interest rate hedging arrangements and a debt service reserve account, and is guaranteed and securitized by certain oil and gas properties and related assets.
47
PRESIDIO PRODUCTION COMPANY
Unaudited Pro Forma Condensed Combined Balance Sheet
As of June 30, 2026
(Dollars in thousands)
Presidio Historical | Arkoma Transaction Accounting Adjustments | Pro Forma Combined | ||||||||||||
| Assets | ||||||||||||||
| Cash and cash equivalents | $ | 42,317 | $ | (3,948 | ) | $ | 38,369 | |||||||
| (58,327 | ) | (a) | ||||||||||||
| 54,379 | (c) | |||||||||||||
| Restricted cash | 11,278 | — | 11,278 | |||||||||||
| Accounts receivable, oil and gas | 18,105 | 3,492 | (b) | 21,597 | ||||||||||
| Accounts receivable, joint interest owners | 10,623 | 56 | (b) | 10,679 | ||||||||||
| Derivative assets - current | 54,555 | 2,267 | (b) | 56,822 | ||||||||||
| Hedge receivable | 6,586 | — | 6,586 | |||||||||||
| Prepaid expenses and other current assets | 2,414 | 6 | (b) | 2,420 | ||||||||||
| Total current assets | 145,878 | 1,873 | 147,751 | |||||||||||
| Oil and natural gas properties, successful efforts | 693,519 | 88,720 | (b) | 782,239 | ||||||||||
| Less accumulated depletion, depreciation, and amortization | (19,535 | ) | — | (19,535 | ) | |||||||||
| Total oil and natural gas properties, net | 673,984 | 88,720 | 762,704 | |||||||||||
| Other property and equipment, net | 4,590 | — | 4,590 | |||||||||||
| Derivative assets - noncurrent | 11,058 | — | 11,058 | |||||||||||
| Right-of-use assets | 3,561 | — | 3,561 | |||||||||||
| Deferred tax assets - noncurrent | 182 | — | 182 | |||||||||||
| Other noncurrent assets | 8,491 | — | 8,491 | |||||||||||
| Total assets | $ | 847,744 | $ | 90,593 | $ | 938,337 | ||||||||
| Liabilities | ||||||||||||||
| Accounts payable | $ | 15,696 | $ | — | $ | 15,696 | ||||||||
| Production taxes payable | 3,570 | — | 3,570 | |||||||||||
| Revenue and royalties payable | 26,071 | 10,070 | (b) | 36,141 | ||||||||||
| Derivative liabilities - current | 10,946 | — | 10,946 | |||||||||||
| Hedge payable | 10,092 | — | 10,092 | |||||||||||
| Current portion of long-term debt | 35,836 | 6,661 | (c) | 42,497 | ||||||||||
| Lease liabilities, current | 299 | — | 299 | |||||||||||
| Other current liabilities | 21,090 | 308 | (b) | 21,398 | ||||||||||
| Total current liabilities | 123,600 | 17,039 | 140,639 | |||||||||||
| Long-term debt, net | 307,236 | 47,718 | (c) | 354,954 | ||||||||||
| Asset retirement obligations | 79,921 | 1,825 | (b) | 81,746 | ||||||||||
| Lease liabilities | 3,328 | — | 3,328 | |||||||||||
| Derivative liabilities - noncurrent | 2,058 | — | 2,058 | |||||||||||
| Earnout liability | 17,772 | — | 17,772 | |||||||||||
| Total liabilities | 533,915 | 66,582 | 600,497 | |||||||||||
| Redeemable Preferred Stock | ||||||||||||||
| Series A redeemable preferred stock | 112,123 | — | 112,123 | |||||||||||
| Series B convertible redeemable preferred | 24,701 | — | 24,701 | |||||||||||
| Stockholders’ Equity | ||||||||||||||
| Class A common stock | 3 | — | 3 | |||||||||||
| Class B common stock | — | — | — | |||||||||||
| Additional paid-in capital | 191,524 | 24,011 | (a) | 215,535 | ||||||||||
| Accumulated deficit | (32,166 | ) | — | (32,166 | ) | |||||||||
| Total stockholders’ equity attributable to Presidio Production Company | 159,361 | 24,011 | 183,372 | |||||||||||
| Non-controlling interest | 17,644 | — | 17,644 | |||||||||||
| Total stockholders’ equity | 177,005 | 24,011 | 201,016 | |||||||||||
| Total liabilities, redeemable preferred stock and stockholders’ equity | $ | 847,744 | $ | 90,593 | $ | 938,337 | ||||||||
See accompanying “Notes to the Unaudited Pro Forma Condensed Combined Financial Statements”
48
PRESIDIO PRODUCTION COMPANY
Unaudited Pro Forma Condensed Combined Statement of Operations
For the Six Months Ended June 30, 2026
(Dollars in thousands, except share and per share amounts)
| Successor | Predecessor | |||||||||||||||||||||||||||||||||||
March 4, 2026 to June 30, 2026 | January 1, 2026 to March 3, 2026 | January 1, 2026 to March 3, 2026 | Six Months Ended June 30, 2026 | |||||||||||||||||||||||||||||||||
PubCo Historical | PIH Historical | EQVR Historical | Presidio Transaction Accounting Adjustments | Presidio Pro Forma | Arkoma Acquired Properties Historical | Arkoma Transaction Accounting Adjustments | Pro Forma Combined | |||||||||||||||||||||||||||||
| Revenues: | ||||||||||||||||||||||||||||||||||||
| Oil sales | $ | 39,476 | $ | 12,017 | $ | 839 | $ | — | $ | 52,332 | $ | 276 | $ | — | $ | 52,608 | ||||||||||||||||||||
| Natural gas sales | 9,675 | 17,497 | 2,429 | — | 29,601 | 8,406 | — | 38,007 | ||||||||||||||||||||||||||||
| Natural gas liquids sales | 19,806 | 6,207 | 1,015 | — | 27,028 | 4,584 | — | 31,612 | ||||||||||||||||||||||||||||
| Field services revenue | 388 | 155 | — | — | 543 | — | — | 543 | ||||||||||||||||||||||||||||
| Total revenues | $ | 69,345 | $ | 35,876 | $ | 4,283 | $ | — | $ | 109,504 | $ | 13,266 | $ | — | $ | 122,770 | ||||||||||||||||||||
| Operating expenses: | ||||||||||||||||||||||||||||||||||||
| Lease operating expenses | 25,345 | 12,277 | 1,145 | — | 38,767 | 1,630 | — | 40,397 | ||||||||||||||||||||||||||||
| Gathering, compression and transportation | — | — | — | — | — | 2,323 | — | 2,323 | ||||||||||||||||||||||||||||
| Production taxes | 3,968 | 2,098 | 164 | — | 6,230 | 796 | — | 7,026 | ||||||||||||||||||||||||||||
| Ad valorem taxes | 1,208 | 758 | 62 | — | 2,028 | — | — | 2,028 | ||||||||||||||||||||||||||||
| Depletion, oil and gas properties | 19,535 | 4,276 | 916 | 4,485 | (aa) | 29,212 | — | 3,041 | (mm) | 32,253 | ||||||||||||||||||||||||||
| Depreciation and amortization, other property and equipment | 1,122 | 673 | 2 | — | 1,797 | — | — | 1,797 | ||||||||||||||||||||||||||||
| Accretion of asset retirement obligation | 1,518 | 643 | 160 | 183 | (bb) | 2,504 | — | 60 | (nn) | 2,564 | ||||||||||||||||||||||||||
| General and administrative | 8,864 | 48,649 | 522 | (46,021 | ) | 12,014 | — | — | 12,014 | |||||||||||||||||||||||||||
| (46,982 | ) | (cc) | ||||||||||||||||||||||||||||||||||
| 961 | (dd) | |||||||||||||||||||||||||||||||||||
| Acquisition and transaction costs | 768 | 6,993 | — | (7,761 | ) | (ee) | — | — | — | — | ||||||||||||||||||||||||||
| Cost of field services revenue | 4 | 9 | — | — | 13 | — | — | 13 | ||||||||||||||||||||||||||||
| Gain on sale of assets | (188 | ) | (816 | ) | (627 | ) | — | (1,631 | ) | — | — | (1,631 | ) | |||||||||||||||||||||||
| Total operating expenses | $ | 62,144 | $ | 75,560 | $ | 2,344 | $ | (49,114 | ) | $ | 90,934 | $ | 4,749 | $ | 3,101 | $ | 98,784 | |||||||||||||||||||
| Income (loss) from operations | $ | 7,201 | $ | (39,684 | ) | $ | 1,939 | $ | 49,114 | $ | 18,570 | $ | 8,517 | $ | (3,101 | ) | $ | 23,986 | ||||||||||||||||||
| Other income (expense): | ||||||||||||||||||||||||||||||||||||
| Gain (loss) on commodity derivatives | (8,342 | ) | (27,905 | ) | (218 | ) | — | (36,465 | ) | — | — | (36,465 | ) | |||||||||||||||||||||||
| Change in fair value of earnout liability | (2,876 | ) | — | — | — | (2,876 | ) | — | — | (2,876 | ) | |||||||||||||||||||||||||
| Loss on early extinguishment of debt | (4,475 | ) | — | — | — | (4,475 | ) | — | — | (4,475 | ) | |||||||||||||||||||||||||
| Interest expense | (6,001 | ) | (3,920 | ) | (663 | ) | 224 | (10,360 | ) | — | (2,107 | ) | (oo) | (12,467 | ) | |||||||||||||||||||||
| (471 | ) | (ff) | ||||||||||||||||||||||||||||||||||
| 32 | (gg) | |||||||||||||||||||||||||||||||||||
| 663 | (hh) | |||||||||||||||||||||||||||||||||||
| Other income (expense) | 13 | 170 | (658 | ) | 500 | (ii) | 25 | — | — | 25 | ||||||||||||||||||||||||||
| Total other income (expense) | $ | (21,681 | ) | $ | (31,655 | ) | $ | (1,539 | ) | $ | 724 | $ | (54,151 | ) | $ | — | $ | (2,107 | ) | $ | (56,258 | ) | ||||||||||||||
| Net income (loss) before income taxes | $ | (14,480 | ) | $ | (71,339 | ) | $ | 400 | $ | 49,838 | $ | (35,581 | ) | $ | 8,517 | $ | (5,208 | ) | $ | (32,272 | ) | |||||||||||||||
| Income tax expense (benefit) | (2,993 | ) | — | — | (4,362 | ) | (jj) | (7,355 | ) | — | 684 | (pp) | (6,671 | ) | ||||||||||||||||||||||
| Net income (loss) | $ | (11,487 | ) | $ | (71,339 | ) | $ | 400 | $ | 54,200 | $ | (28,226 | ) | $ | 8,517 | $ | (5,892 | ) | $ | (25,601 | ) | |||||||||||||||
| Net income (loss) attributable to non-controlling interests | (493 | ) | — | — | (955 | ) | (kk) | (1,448 | ) | — | 232 | (qq) | (1,216 | ) | ||||||||||||||||||||||
| Net income (loss) attributable to common shareholders | $ | (10,994 | ) | $ | (71,339 | ) | $ | 400 | $ | 55,155 | $ | (26,778 | ) | $ | 8,517 | $ | (6,124 | ) | $ | (24,385 | ) | |||||||||||||||
| Preferred stock dividends | 5,380 | — | — | 2,625 | (ll) | 8,005 | — | — | 8,005 | |||||||||||||||||||||||||||
| Net income (loss) available to common shareholders | $ | (16,374 | ) | $ | (71,339 | ) | $ | 400 | $ | 52,530 | $ | (34,783 | ) | $ | 8,517 | $ | (6,124 | ) | $ | (32,390 | ) | |||||||||||||||
| Basic and diluted weighted average Class A common shares outstanding | 26,751,925 | 26,751,925 | 1,962,240 | (rr) | 28,714,165 | |||||||||||||||||||||||||||||||
| Basic and diluted net income (loss) per Class A common share | $ | (0.61 | ) | $ | (1.30 | ) | $ | (1.13 | ) | |||||||||||||||||||||||||||
See accompanying “Notes to the Unaudited Pro Forma Condensed Combined Financial Statements”
49
PRESIDIO PRODUCTION COMPANY
Unaudited Pro Forma Condensed Combined Statement of Operations
For the Year Ended December 31, 2025
(Dollars in thousands, except share and per share amounts)
PIH Historical | EQVR Historical | Presidio Transaction Accounting Adjustments | Presidio Pro Forma | Arkoma Acquired Properties Historical | Arkoma Transaction Accounting Adjustments | Pro Forma Combined | ||||||||||||||||||||||||||
| Revenues: | ||||||||||||||||||||||||||||||||
| Oil sales | $ | 81,640 | $ | 5,769 | $ | — | $ | 87,409 | $ | 543 | $ | — | $ | 87,952 | ||||||||||||||||||
| Natural gas sales | 50,309 | 9,680 | — | 59,989 | 18,222 | — | 78,211 | |||||||||||||||||||||||||
| Natural gas liquids sales | 45,864 | 5,720 | — | 51,584 | 9,663 | — | 61,247 | |||||||||||||||||||||||||
| Field services revenue | 1,243 | — | — | 1,243 | — | — | 1,243 | |||||||||||||||||||||||||
| Total revenues | $ | 179,056 | $ | 21,169 | $ | — | $ | 200,225 | $ | 28,428 | $ | — | $ | 228,653 | ||||||||||||||||||
| Operating expenses: | ||||||||||||||||||||||||||||||||
| Lease operating expenses | 73,016 | 10,355 | — | 83,371 | 3,342 | — | 86,713 | |||||||||||||||||||||||||
| Gathering, compression and transportation | — | — | — | — | 5,126 | — | 5,126 | |||||||||||||||||||||||||
| Production taxes | 9,795 | 862 | — | 10,657 | 1,662 | — | 12,319 | |||||||||||||||||||||||||
| Ad valorem taxes | 5,500 | 973 | — | 6,473 | — | — | 6,473 | |||||||||||||||||||||||||
| Depletion, oil and gas properties | 28,418 | 4,917 | 22,938 | (aa) | 56,273 | — | 6,838 | (mm) | 63,111 | |||||||||||||||||||||||
| Depreciation and amortization, other property and equipment | 3,279 | — | — | 3,279 | — | — | 3,279 | |||||||||||||||||||||||||
| Accretion of asset retirement obligation | 4,134 | 747 | 567 | (bb) | 5,448 | — | 115 | (nn) | 5,563 | |||||||||||||||||||||||
| General and administrative | 24,216 | 2,379 | 52,637 | 79,232 | — | — | 79,232 | |||||||||||||||||||||||||
| 46,982 | (cc) | |||||||||||||||||||||||||||||||
| 5,655 | (dd) | |||||||||||||||||||||||||||||||
| Acquisition and transaction costs | 4,156 | — | 7,761 | (ee) | 11,917 | — | — | 11,917 | ||||||||||||||||||||||||
| Cost of field services revenue | 823 | — | — | 823 | — | — | 823 | |||||||||||||||||||||||||
| Gain on sale of assets | (8,455 | ) | — | — | (8,455 | ) | — | — | (8,455 | ) | ||||||||||||||||||||||
| Total operating expenses | $ | 144,882 | $ | 20,233 | $ | 83,903 | $ | 249,018 | $ | 10,130 | $ | 6,953 | $ | 266,101 | ||||||||||||||||||
| Income (loss) from operations | $ | 34,174 | $ | 936 | $ | (83,903 | ) | $ | (48,793 | ) | $ | 18,298 | $ | (6,953 | ) | $ | (37,448 | ) | ||||||||||||||
| Other income (expense): | ||||||||||||||||||||||||||||||||
| Gain (loss) on commodity derivatives | 47,161 | 4,798 | — | 51,959 | — | — | 51,959 | |||||||||||||||||||||||||
| Interest expense | (24,491 | ) | (4,048 | ) | 1,451 | (27,088 | ) | — | (3,663 | ) | (oo) | (30,751 | ) | |||||||||||||||||||
| (2,775 | ) | (ff) | ||||||||||||||||||||||||||||||
| 178 | (gg) | |||||||||||||||||||||||||||||||
| 4,048 | (hh) | |||||||||||||||||||||||||||||||
| Other income (expense) | 23 | 10 | 2,000 | (ii) | 2,033 | — | — | 2,033 | ||||||||||||||||||||||||
| Total other income (expense) | $ | 22,693 | $ | 760 | $ | 3,451 | $ | 26,904 | $ | — | $ | (3,663 | ) | $ | 23,241 | |||||||||||||||||
| Net income (loss) before income taxes | $ | 56,867 | $ | 1,696 | $ | (80,452 | ) | $ | (21,889 | ) | $ | 18,298 | $ | (10,616 | ) | $ | (14,207 | ) | ||||||||||||||
| Income tax expense (benefit) | 992 | — | (5,516 | ) | (jj) | (4,524 | ) | — | 1,588 | (pp) | (2,936 | ) | ||||||||||||||||||||
| Net income (loss) | $ | 55,875 | $ | 1,696 | $ | (74,936 | ) | $ | (17,365 | ) | $ | 18,298 | $ | (12,204 | ) | $ | (11,271 | ) | ||||||||||||||
| Net income (loss) attributable to non-controlling interests | — | — | (992 | ) | (kk) | (992 | ) | — | 389 | (qq) | (603 | ) | ||||||||||||||||||||
| Net income (loss) attributable to common shareholders | $ | 55,875 | $ | 1,696 | $ | (73,944 | ) | $ | (16,373 | ) | $ | 18,298 | $ | (12,593 | ) | $ | (10,668 | ) | ||||||||||||||
| Preferred stock dividends | — | — | 15,000 | (ll) | 15,000 | — | — | 15,000 | ||||||||||||||||||||||||
| Net income (loss) available to common shareholders | $ | 55,875 | $ | 1,696 | $ | (88,944 | ) | $ | (31,373 | ) | $ | 18,298 | $ | (12,593 | ) | $ | (25,668 | ) | ||||||||||||||
| Basic and diluted weighted average Class A common shares outstanding | 26,738,407 | 1,962,240 | (rr) | 28,700,647 | ||||||||||||||||||||||||||||
| Basic and diluted net income (loss) per Class A common share | $ | (1.17 | ) | $ | (0.89 | ) | ||||||||||||||||||||||||||
See accompanying “Notes to the Unaudited Pro Forma Condensed Combined Financial Statements”
50
NOTES TO UNAUDITED PRO FORMA CONDENSED COMBINED FINANCIAL INFORMATION
Note 1 — Basis of Presentation
The unaudited pro forma condensed combined financial information was prepared in accordance with Article 11 of Regulation S-X, as amended by the final rule, Release No. 33-10786, and presents the pro forma financial condition and results of operations of Presidio based upon the historical financial information of Presidio, PIH, EQVR, and the Arkoma Acquired Properties after giving effect to the Business Combination, EQVR Acquisition and Arkoma Acquisition and related adjustments set forth in the notes to the unaudited pro forma condensed combined financial information.
The unaudited pro forma condensed combined financial information reflects pro forma adjustments that are based on available information and certain assumptions that management believes are reasonable. However, actual results may differ from those reflected in these statements. In management’s opinion, all adjustments known to date that are necessary to fairly present the unaudited pro forma condensed combined financial information have been made. The unaudited pro forma condensed combined financial information is presented for informational purposes only and is not necessarily indicative of the results of operations or financial position that would have been achieved had the Business Combination, EQVR Acquisition and Arkoma Acquisition been consummated on the dates indicated, nor of future results of operations or financial position.
Accounting for the Business Combination and EQVR Acquisition
The Business Combination and the EQVR Acquisition were accounted for as acquisitions of variable interest entities that are not a business under ASC 810. Under this method of accounting, PIH’s and EQVR’s identifiable assets acquired, liabilities assumed, and non-controlling interests are measured at their acquisition date fair values. Presidio determined that PIH was the predecessor as PIH comprises most of the combined entity’s assets and operations and is managed by PIH’s management team after consummation of the Business Combination.
Accounting for the Arkoma Acquisition
The Arkoma Acquisition is accounted for as an asset acquisition under ASC 805-50. The total cost of the acquisition is allocated to the individual assets acquired and liabilities assumed on a relative fair value basis as of the acquisition date using the relevant information available as of the acquisition date. Transaction costs that are directly related and incremental are capitalized as a component of cost rather than expensed.
No historical balance sheet is presented for the Arkoma Acquired Properties. The historical financial statements of the Arkoma Acquired Properties filed under Item 9.01(a) of this Form 8-K/A consist of statements of revenues and direct operating expenses prepared in accordance with Rule 3-05(f) of Regulation S-X, which does not require a balance sheet for an acquired business that includes significant oil and gas producing activities, and the sellers did not maintain distinct and separate accounts from which a balance sheet for the Arkoma Acquired Properties could be prepared.
The statements of revenues and direct operating expenses for the Arkoma Acquired Properties represent abbreviated financial statements that include less information about the historical business associated with the assets or about our current and future results as the owner of the assets than full financial statements. For example, the statements of revenues and direct operating expenses do not include depreciation, depletion and amortization, general and administrative expenses, interest expense, income taxes and other indirect expenses, because such expenses were not separately allocated to the acquired properties in the sellers’ accounting records. The unaudited pro forma condensed combined financial information reflects adjustments to estimate certain indirect expenses excluded from the historical financial information.
51
Note 2 — Preliminary Acquisition Accounting
The following table summarizes the total cost of acquisition for the Arkoma Acquisition:
| (in thousands) | ||||
| Cash | $ | 53,060 | ||
| Equity interests | 24,011 | |||
| Consideration transferred | $ | 77,071 | ||
| Capitalized transaction costs | 5,267 | |||
| Total cost of acquisition | $ | 82,338 | ||
Equity interests issued as consideration were measured on the acquisition date using the closing market price of the Company’s Class A common stock on the applicable closing dates, $12.24 per share for the six acquisitions that closed July 1, 2026 and $12.03 per share for the Harbor Island acquisition that closed July 21, 2026.
The following table summarizes the fair value of equity interests issued:
| (in thousands, except share and per share amounts) | ||||
| Class A common stock | 1,962,240 | |||
| Share price (weighted average) | $ | 12.24 | ||
| Fair value of equity interests | $ | 24,011 | ||
The preliminary allocation of the total costs for the Arkoma Acquisition is based upon management’s estimates and assumptions related to the fair value of the assets acquired and liabilities assumed as of June 30, 2026 using currently available information. Because the unaudited pro forma condensed combined financial information has been prepared based on these preliminary estimates, the final total cost allocation and the resulting effect on the Company’s financial position and results of operations may differ significantly from the pro forma amounts included herein.
The following table summarizes the identified assets acquired and liabilities assumed:
| (in thousands) | ||||
| Oil and natural gas properties, successful efforts | $ | 88,720 | ||
| Accounts receivable, oil and gas | 3,492 | |||
| Accounts receivable, joint interest owners | 56 | |||
| Derivative assets, net | 2,267 | |||
| Prepaid expenses | 6 | |||
| Total assets acquired | $ | 94,541 | ||
| Suspended revenues | 9,109 | |||
| Accrued royalties | 961 | |||
| Accrued costs | 308 | |||
| Asset retirement obligations | 1,825 | |||
| Total liabilities assumed | $ | 12,203 | ||
| Net assets acquired | $ | 82,338 | ||
52
Note 3 — Transaction Accounting Adjustments
The unaudited pro forma condensed combined financial information has been prepared to illustrate the effect of the Business Combination, EQVR Acquisition, and Arkoma Acquisition and has been prepared for informational purposes only.
The pro forma combined provision for income taxes does not necessarily reflect the amounts that would have resulted had Presidio filed consolidated income tax returns during the periods presented.
The pro forma basic and diluted earnings per share amounts presented in the unaudited pro forma condensed combined statement of operations are based upon the number of Presidio’s shares outstanding, assuming the Business Combination, EQVR Acquisition and Arkoma Acquisition occurred on January 1, 2025.
Arkoma Transaction Accounting Adjustments to Unaudited Pro Forma Condensed Combined Balance Sheet
| (a) | Reflects the costs of the Arkoma Acquisition, consisting of cash of $53.1 million and equity interests with a fair value of $24.0 million, together with capitalized transaction costs of $5.2 million, for total cost of acquisition of $82.3 million. |
| (b) | Reflects the assets and liabilities acquired from the Arkoma Acquisition (see Note 2). |
| (c) | Reflects the cash proceeds of $55.0 million from the Warehouse Financing, net of $0.6 million debt issuance costs. |
Presidio Transaction Accounting Adjustments to Unaudited Pro Forma Condensed Combined Statements of Operations
| (aa) | Reflects the adjustment to depletion expense for the new basis of oil and natural gas properties as a result of the final purchase price allocation, as the pro forma closing of the Business Combination is assumed to be January 1, 2025. |
| (bb) | Reflects the adjustment to accretion expense for the new basis of the asset retirement obligations as a result of the final purchase price allocation, as the pro forma closing of the Business Combination is assumed to be January 1, 2025. |
| (cc) | Reflects general and administrative expense related to compensation expense contingent upon change of control, which was originally recognized in the six months ended June 30, 2026 but reclassified to the year ended December 31, 2025, as the pro forma closing of the Business Combination is assumed to be January 1, 2025. This expense will not recur beyond 12 months after the transaction. |
| (dd) | Reflects the adjustment to include compensation expense related to the vesting of the Restricted Stock Units (“RSUs”) granted to Presidio’s officers upon Closing pursuant to the Company’s compensation plan. Additionally, the historical general and administrative expenses include $15.0 million recognized as non-recurring compensation expense following the sale of certain undeveloped properties that triggered a distribution to PIH Class B unitholders during the year ended December 31, 2025. This expense will not recur beyond 12 months after the transaction. |
| (ee) | Reflects transaction costs associated with the Business Combination originally recognized in the six months ended June 30, 2026 but reclassified to the year ended December 31, 2025, as the pro forma closing of the Business Combination is assumed to be January 1, 2025. This charge is not expected to recur in the twelve months following closing. |
| (ff) | Reflects interest expense related to the RBL Financing. The RBL Financing bears interest at 7.50% per annum based on the 3.75% Secured Overnight Financing Rate (“SOFR”) spread, plus the higher of the estimated SOFR curve of 3.75% or SOFR floor of 0.75%. |
| (gg) | Reflects the elimination of the interest expense associated with PIH’s note payable paid off at Closing. |
| (hh) | Reflects the elimination of the interest expense associated with EQVR’s note payable paid off at Closing. |
| (ii) | Reflects the elimination of certain management fees for EQVR. This expense will not recur beyond 12 months after the transaction. |
53
| (jj) | Reflects the pro forma adjustment to income tax expense (benefit) resulting from the pro forma adjustments made to the unaudited condensed combined statement of operations and change in tax status, which was calculated using an effective tax rate of 20.7%. |
| (kk) | Immediately following the Business Combination and EQVR Acquisition, the ownership of Presidio represented by the economic interests held by the non-controlling interests (comprising of EQV Holdings Units and excluding shares of Presidio Class A Common Stock) was approximately 5.7%. Net income/(loss) attributable to the non-controlling interest was then calculated by multiplying the non-controlling interest percentage by net income/(loss), inclusive of the impacts of all other adjustments. |
| (ll) | Reflects the adjustment for the pro forma dividends attributable to the Series A Preferred Investors at 12% per annum. |
Arkoma Transaction Accounting Adjustments to Unaudited Pro Forma Condensed Combined Statements of Operations
| (mm) | Reflects the adjustment to depletion expense for the new basis of oil and natural gas properties as a result of the preliminary purchase price allocation, as the pro forma closing of the Arkoma Acquisition is assumed to be January 1, 2025. |
| (nn) | Reflects the adjustment to accretion expense for the new basis of the asset retirement obligations as a result of the preliminary purchase price allocation, as the pro forma closing of the Arkoma Acquisition is assumed to be January 1, 2025. |
| (oo) | Reflects interest expense related to the Warehouse Financing. The interest was calculated using a 3.66% Secured Overnight Financing Rate (“SOFR”) plus an applicable margin of 3.00% for the year ended December 31, 2025 and 4.00% for the six months ended June 30, 2026. |
| (pp) | Reflects the pro forma adjustment to income tax expense (benefit) resulting from the pro forma adjustments made to the unaudited condensed combined statement of operations and change in tax status, which was calculated using an effective tax rate of 20.7%. |
| (qq) | Net income/(loss) attributable to the non-controlling interest was calculated by multiplying the non-controlling interest percentage of approximately 5.4% by net income/(loss), inclusive of the impacts of all other adjustments. |
| (rr) | Reflects shares issued as consideration for the Arkoma Acquisition (see Note 2). |
54
Note 4 — Pro Forma Net Income (Loss) per Share
Basic net income (loss) per share is computed on the weighted average number of Class A shares outstanding during the period together with the shares issued as consideration in the Business Combination, EQVR Acquisition and Arkoma Acquisition, assuming those shares were outstanding since January 1, 2025. As the Business Combination, EQVR Acquisition and Arkoma Acquisition are being reflected as if they had occurred at the beginning of the period presented, the calculation of weighted average shares outstanding for basic and diluted net loss per share assumes that the shares issuable in connection with the transactions have been outstanding for the entire period presented. Diluted net income (loss) per share is computed on the weighted average number of shares of common stock plus the effect of dilutive potential common shares using the treasury stock method.
| (in thousands, except share and per share amounts) | Six Months Ended June 30, 2026 | Year Ended December 31, 2025 | ||||||
| Pro forma net income (loss) available to common shareholders (1) | $ | (32,390 | ) | $ | (25,668 | ) | ||
| Pro forma weighted average Class A common stock outstanding — basic and diluted (2) | 28,714,165 | 28,700,647 | ||||||
| Pro forma Class A net income (loss) per share, basic and diluted | $ | (1.13 | ) | $ | (0.89 | ) | ||
| (1) | No allocation of undistributed losses to unvested RSUs is reflected as the participating securities have no contractual obligation to share in losses. |
| (2) | Inclusive of 937,500 Series A Preferred Investor Warrants which considered outstanding shares of common stock as the shares are issuable for little or no consideration with no conditions that must be met other than the passage of time, and excludes the Presidio Interests convertible into 1,676,830 shares of Presidio Class A Common Stock which are EQV Holdings Units that represent the economic interests of the combined company held by the non-controlling interests. |
The following potential shares of Presidio common stock were excluded from the computation of pro forma diluted net income (loss) per share for the six months ended June 30, 2026 and the year ended December 31, 2025:
| Excluded Securities | Six Months Ended June 30, 2026 | Year Ended December 31, 2025 | ||||||
| EQV Public Warrant Holders (1) | 11,666,637 | 11,666,637 | ||||||
| Private Placement Warrant Holders (1) | 220,832 | 220,832 | ||||||
| Earn-out Shares (2) | 1,851,161 | 1,851,161 | ||||||
| Series B Convertible Preferred Stock (3) | 2,717,300 | 2,717,300 | ||||||
| Restricted Stock Units (3) | 2,210,099 | 1,535,250 | ||||||
| Total | 18,666,029 | 17,991,180 | ||||||
| (1) | The Public and Private Placement Warrants are excluded as they are not assumed to be exercised based on the exercise price. |
| (2) | The Earn-Out Shares are considered contingently issuable shares and are excluded as the specified conditions would not be satisfied if the end of the reporting period were the end of the contingency period. |
| (3) | The Series B Convertible Preferred Stock and unvested RSUs are excluded as their inclusion is anti-dilutive. |
55
Note 5 — Supplemental Pro Forma Oil and Natural Gas Reserve Information
Pro forma combined estimated quantities of oil and gas reserves
The following tables present estimated pro forma combined net proved developed and undeveloped oil and natural gas reserve information as of December 31, 2025, together with a summary of changes in quantities of net remaining proved reserves during the year ended December 31, 2025. The historical information regarding net proved oil and natural gas reserves attributable to PIH and EQVR are based on reserve estimates prepared by Cawley, Gillespie & Associates, Inc., an independent petroleum engineering firm, as of December 31, 2025. The historical information regarding net proved oil and natural gas reserves attributable to the Arkoma Acquired Properties are based on reserve estimates prepared by Pinnacle Energy Services, LLC, an independent petroleum engineering firm, as of December 31, 2025.
This information is not necessarily indicative of the results that might have occurred had the Business Combination, EQVR Acquisition and Arkoma Acquisition been completed on December 31, 2025 and is not intended to be a projection of future results.
Pro Forma Oil Reserves
| Oil (MBbls) | PIH Historical | EQVR Historical | Presidio Pro Forma | Arkoma Acquired Properties Historical | Pro Forma Combined | |||||||||||||||
| Balance at December 31, 2024 | 14,194 | 867 | 15,061 | 55 | 15,116 | |||||||||||||||
| Revisions of previous estimates | (249 | ) | 37 | (212 | ) | 7 | (205 | ) | ||||||||||||
| Extensions, discoveries and other additions | 36 | — | 36 | — | 36 | |||||||||||||||
| Production | (1,290 | ) | (91 | ) | (1,381 | ) | (8 | ) | (1,389 | ) | ||||||||||
| Purchase of reserves | — | — | — | — | — | |||||||||||||||
| Sale of reserves | (10 | ) | — | (10 | ) | — | (10 | ) | ||||||||||||
| Balance at December 31, 2025 | 12,681 | 813 | 13,494 | 54 | 13,548 | |||||||||||||||
| Proved Developed Reserves: | ||||||||||||||||||||
| Balance at December 31, 2024 | 14,144 | 867 | 15,011 | 55 | 15,066 | |||||||||||||||
| Balance at December 31, 2025 | 12,681 | 813 | 13,494 | 54 | 13,548 | |||||||||||||||
| Proved Undeveloped Reserves: | ||||||||||||||||||||
| Balance at December 31, 2024 | 50 | — | 50 | — | 50 | |||||||||||||||
| Balance at December 31, 2025 | — | — | — | — | — | |||||||||||||||
Pro Forma Natural Gas Reserves
| Natural gas (MMcf) | PIH Historical | EQVR Historical | Presidio Pro Forma | Arkoma Acquired Properties Historical | Pro Forma Combined | |||||||||||||||
| Balance at December 31, 2024 | 301,701 | 42,003 | 343,704 | 83,415 | 427,119 | |||||||||||||||
| Revisions of previous estimates | 37,074 | 3,895 | 40,969 | 2,965 | 43,934 | |||||||||||||||
| Extensions, discoveries and other additions | 278 | — | 278 | — | 278 | |||||||||||||||
| Production | (25,778 | ) | (4,377 | ) | (30,155 | ) | (6,185 | ) | (36,340 | ) | ||||||||||
| Purchase of reserves | — | — | — | — | — | |||||||||||||||
| Sale of reserves | (370 | ) | — | (370 | ) | — | (370 | ) | ||||||||||||
| Balance at December 31, 2025 | 312,905 | 41,521 | 354,426 | 80,195 | 434,621 | |||||||||||||||
| Proved Developed Reserves: | ||||||||||||||||||||
| Balance at December 31, 2024 | 301,318 | 42,003 | 343,321 | 83,415 | 426,736 | |||||||||||||||
| Balance at December 31, 2025 | 312,905 | 41,521 | 354,426 | 80,195 | 434,621 | |||||||||||||||
| Proved Undeveloped Reserves: | ||||||||||||||||||||
| Balance at December 31, 2024 | 383 | — | 383 | — | 383 | |||||||||||||||
| Balance at December 31, 2025 | — | — | — | — | — | |||||||||||||||
56
Pro Forma Natural Gas Liquid Reserves
| NGLs (MBbls) | PIH Historical | EQVR Historical | Presidio Pro Forma | Arkoma Acquired Properties Historical | Pro Forma Combined | |||||||||||||||
| Balance at December 31, 2024 | 27,111 | 4,120 | 31,231 | 5,952 | 37,183 | |||||||||||||||
| Revisions of previous estimates | 91 | (152 | ) | (61 | ) | 313 | 252 | |||||||||||||
| Extensions, discoveries and other additions | 6 | — | 6 | — | 6 | |||||||||||||||
| Production | (2,093 | ) | (369 | ) | (2,462 | ) | (445 | ) | (2,907 | ) | ||||||||||
| Purchase of reserves | — | — | — | — | — | |||||||||||||||
| Sale of reserves | (44 | ) | — | (44 | ) | — | (44 | ) | ||||||||||||
| Balance at December 31, 2025 | 25,071 | 3,599 | 28,670 | 5,820 | 34,490 | |||||||||||||||
| Proved Developed Reserves: | ||||||||||||||||||||
| Balance at December 31, 2024 | 27,111 | 4,120 | 31,231 | 5,952 | 37,183 | |||||||||||||||
| Balance at December 31, 2025 | 25,071 | 3,599 | 28,670 | 5,820 | 34,490 | |||||||||||||||
| Proved Undeveloped Reserves: | ||||||||||||||||||||
| Balance at December 31, 2024 | — | — | — | — | — | |||||||||||||||
| Balance at December 31, 2025 | — | — | — | — | — | |||||||||||||||
Pro Forma Total Reserves
| Total (MBoe) | PIH Historical | EQVR Historical | Presidio Pro Forma | Arkoma Acquired Properties Historical | Pro Forma Combined | |||||||||||||||
| Balance at December 31, 2024 | 91,589 | 11,987 | 103,576 | 19,910 | 123,486 | |||||||||||||||
| Revisions of previous estimates | 6,021 | 534 | 6,555 | 814 | 7,369 | |||||||||||||||
| Extensions, discoveries and other additions | 88 | — | 88 | — | 88 | |||||||||||||||
| Production | (7,679 | ) | (1,190 | ) | (8,869 | ) | (1,484 | ) | (10,353 | ) | ||||||||||
| Purchase of reserves | — | — | — | — | — | |||||||||||||||
| Sale of reserves | (116 | ) | — | (116 | ) | — | (116 | ) | ||||||||||||
| Balance at December 31, 2025 | 89,903 | 11,331 | 101,234 | 19,240 | 120,474 | |||||||||||||||
| Proved Developed Reserves: | ||||||||||||||||||||
| Balance at December 31, 2024 | 91,475 | 11,987 | 103,462 | 19,910 | 123,372 | |||||||||||||||
| Balance at December 31, 2025 | 89,903 | 11,331 | 101,234 | 19,240 | 120,474 | |||||||||||||||
| Proved Undeveloped Reserves: | ||||||||||||||||||||
| Balance at December 31, 2024 | 114 | — | 114 | — | 114 | |||||||||||||||
| Balance at December 31, 2025 | — | — | — | — | — | |||||||||||||||
Notable changes in proved reserves for the year ended December 31, 2025 included the following:
| ● | Extensions and Discoveries: In 2025, total extensions and discoveries for PIH increased proved reserves by 88 MBoe. The primary driver was successful partner-operated activity within the basin. The Arkoma Acquired Properties had no extensions or discoveries in 2025. |
| ● | Revisions of Previous Estimates: In 2025, revisions of previous estimates for PIH resulted in a net increase of 6.0 MMBoe. Approximately 7.1 MMBoe of this change was attributable to higher prices utilized for the year ended December 31, 2025. While year-end SEC pricing increased compared to December 31, 2024, revisions to other economic assumptions, including forward pricing considerations, contributed to changes in the timing of certain workover activities. These factors, together with updates to cost estimates, deduct modeling, and midstream election assumptions, resulted in an offsetting decrease of approximately 1.1 MMBoe. Revisions of previous estimates for EQVR resulted in a net increase of 534 MBoe. Of this increase, 1,156 MBoe was attributable to higher SEC pricing, counteracted by other revisions resulting in a decrease of 622 MBoe. The Arkoma Acquired Properties saw upward revisions of previous estimates based on increased pricing in 2025 resulting in approximately a net increase of 814 MBoe which was offset by the natural decline curve of the wells. |
57
Pro forma combined discounted future net cash flows
The pro forma standardized measure related to proved oil, gas and NGL reserves is summarized below. This summary is based on a valuation of proved reserves using discounted cash flows based on SEC pricing applicable for each year, costs and economic conditions and a 10% discount rate. The additions to proved reserves from new discoveries and extensions and the impact of changes in prices and costs associated with proved reserves could vary significantly from year to year. Accordingly, the information presented below is not an estimate of fair value and should not be considered indicative of any trends.
The pro forma standardized measure of discounted future cash flows does not purport, nor should it be interpreted to present, estimates of the fair value of the properties. An estimate of fair value would also take into account, among other things, the recovery of reserves not presently classified as proved, anticipated future changes in prices and costs and a discount factor more representative of the time value of money and risks inherent in reserve estimates.
The following summary sets forth the standardized measure of future net cash flows relating to proved oil and gas reserves as of December 31, 2025:
(in thousands) — as of December 31, 2025 | PIH Historical | EQVR Historical | Pro Forma Adjust- ments (2) | Presidio Pro Forma | Arkoma Acquired Properties Historical | Pro Forma Adjust- ments (2) | Pro Forma Combined | |||||||||||||||||||||
| Future cash inflows | $ | 2,385,532 | $ | 250,885 | $ | — | $ | 2,636,417 | $ | 298,439 | $ | — | $ | 2,934,856 | ||||||||||||||
| Future production costs | (1,390,660 | ) | (132,921 | ) | — | (1,523,581 | ) | (60,054 | ) | — | (1,583,635 | ) | ||||||||||||||||
| Future development costs | (135,812 | ) | (24,791 | ) | — | (160,603 | ) | (1,689 | ) | — | (162,292 | ) | ||||||||||||||||
| Future net cash flows before income tax | $ | 859,060 | $ | 93,173 | $ | — | $ | 952,233 | $ | 236,696 | $ | — | $ | 1,188,929 | ||||||||||||||
| Future income tax expense (1) | (3,871 | ) | — | (89,836 | ) | (93,707 | ) | — | (24,468 | ) | (118,175 | ) | ||||||||||||||||
| Future net cash flows | $ | 855,189 | $ | 93,173 | $ | (89,836 | ) | $ | 858,526 | $ | 236,696 | $ | (24,468 | ) | $ | 1,070,754 | ||||||||||||
| 10% annual discount for estimated timing of cash flows | (341,090 | ) | (37,027 | ) | 35,497 | (342,620 | ) | (132,325 | ) | 11,914 | (463,031 | ) | ||||||||||||||||
| Standardized measure of discounted future net cash flows | $ | 514,099 | $ | 56,146 | $ | (54,339 | ) | $ | 515,906 | $ | 104,371 | $ | (12,554 | ) | $ | 607,723 | ||||||||||||
| (1) | Historical future net cash flows do not include the effects of income taxes on future revenues because it was a limited liability company not subject to entity-level income taxation as of December 31, 2025. Accordingly, no provision for federal or state corporate income taxes has been provided historically because taxable income was passed through to the PIH, EQVR and Arkoma Acquired Properties equity members. |
| (2) | The pro forma adjustments reflect the impact of the entity-level income taxation that would have been applicable to the Company as of December 31, 2025, on an undiscounted and discounted basis, based on an estimated 22.4% blended statutory U.S. federal and state tax rate. |
Sources of change in pro forma combined discounted future net cash flows
The principal changes in the pro forma consolidated standardized measure of discounted future net cash flows relating to proved reserves for the year ended December 31, 2025, are as follows:
(in thousands) — year ended December 31, 2025 | PIH Historical | EQVR Historical | Pro Forma Adjust- ments (1) | Presidio Pro Forma | Arkoma Acquired Properties Historical | Pro Forma Adjust- ments (1) | Pro Forma Combined | |||||||||||||||||||||
| Sales of oil and gas, net of production costs | (89,621 | ) | (8,978 | ) | — | (98,599 | ) | (18,298 | ) | — | (116,897 | ) | ||||||||||||||||
| Net changes in prices and production costs | 48,728 | 15,505 | — | 64,233 | 45,137 | — | 109,370 | |||||||||||||||||||||
| Changes in future development costs | 235 | — | — | 235 | (67 | ) | — | 168 | ||||||||||||||||||||
| Extensions, discoveries and other additions | 1,525 | — | — | 1,525 | — | — | 1,525 | |||||||||||||||||||||
| Development costs incurred during the period | 261 | — | — | 261 | — | — | 261 | |||||||||||||||||||||
| Revisions of previous quantity estimates | 36,872 | 3,595 | — | 40,467 | 4,767 | — | 45,234 | |||||||||||||||||||||
| Purchases of reserves-in-place | — | — | — | — | — | — | — | |||||||||||||||||||||
| Sale of reserves-in-place | 27 | — | — | 27 | — | — | 27 | |||||||||||||||||||||
| Accretion of discount | 49,190 | 5,069 | — | 54,259 | 6,980 | — | 61,239 | |||||||||||||||||||||
| Net change in income taxes | (1,148 | ) | — | (54,339 | ) | (55,487 | ) | — | (12,554 | ) | (68,041 | ) | ||||||||||||||||
| Changes in timing and other | (23,865 | ) | (9,737 | ) | — | (33,602 | ) | (3,947 | ) | — | (37,549 | ) | ||||||||||||||||
| Net increase (decrease) | $ | 22,204 | $ | 5,454 | $ | (54,339 | ) | $ | (26,681 | ) | $ | 34,572 | $ | (12,554 | ) | $ | (4,663 | ) | ||||||||||
| Beginning of year | 491,895 | 50,692 | — | 542,587 | 69,799 | — | 612,386 | |||||||||||||||||||||
| End of year | $ | 514,099 | $ | 56,146 | $ | (54,339 | ) | $ | 515,906 | $ | 104,371 | $ | (12,554 | ) | $ | 607,723 | ||||||||||||
| (1) | The pro forma adjustments reflect the impact of the entity-level income taxation that would have been applicable to the Company as of December 31, 2025, on an undiscounted and discounted basis, based on an estimated 22.4% blended statutory U.S. federal and state tax rate. |
58
BUSINESS OF PRESIDIO PRODUCTION COMPANY
Overview
Presidio is an independent energy company headquartered in Texas and founded in 2017. We are primarily engaged in oil and gas exploration and production, with operations concentrated across the Western Anadarko Basin of Texas, Oklahoma, and Kansas. Our strategy is centered on acquiring existing producing assets and applying engineering expertise to enhance performance and extend asset life. Our management team, led by Will Ulrich and Chris Hammack, possesses extensive operational and industry experience. We leverage this experience to create sustainable value by investing in long-lived reserves, reducing emissions, improving asset integrity, and generating consistent, hedged-protected cash flow.
Our Business Model
| ● | Acquire — We utilize a disciplined, value-based framework for systematically evaluating and pursuing acquisition opportunities. We target existing long-lived, stable assets that produce predictable and stable cash flows, are value accretive, and are strategically complementary. Unlike many peers focused on new resource development, we maximize value by fully exploiting existing reserves — safely and efficiently operating wells to extend their productive lives and economic contribution. |
| ● | Optimize — A core component of our strategy is our focus on continuous optimization to increase operational efficiency. The primarily mature nature of the assets we acquire provides us with a portfolio of low-cost optimization opportunities. We increase efficiency across our operations by leveraging technology, synergies and our access to attractive proved developed producing financing. |
| ● | Produce — We focus on production to extract oil, natural gas and NGLs at competitive margins, thereby creating stable, predictable cash flows to be used for future acquisitions, dividends to our shareholders and debt reduction. |
We emphasize a disciplined approach for capital allocation, controlling costs and maintaining financial discipline to allow us to generate significant free cash flow. Our strategy is centered on acquiring existing producing assets and applying engineering expertise to enhance performance and asset life. Management places emphasis on operating cash flow in managing the business as operating cash flow considers the cash expenses incurred during the period and excludes non-cash expenditures not directly related to operations. Our culture of cost control and production optimization has resulted in substantially lower cash operating costs than our peers.
Our Properties
Our assets are located throughout Texas, Oklahoma, and Kansas, consisting of approximately 2,158 net operated and non-operated proved developed producing wells. Our average net daily production was approximately 22.6 MBoe/d, 19.4 MBoe/d, and 21.1 MBoe/d for the successor period from March 4, 2026 to June 30, 2026, and for the predecessor periods from January 1, 2026 to March 3, 2026 and for the year ended December 31, 2025, respectively. Our wells are located in the Anadarko and Arkoma Basins, which have a more predictable production profile compared to less mature basins. Our production benefits from both the diversity of our well vintage and the lack of concentration in any specific sub-area. Within our large and diversified proved developed producing base, no single well accounts for more than 1.06% of our proved developed producing PV-10.
Within our operating areas, our assets are prospective for multiple formations. Our experience in the Western Anadarko Basin and these formations allows us to generate significant free cash flow from these low declining assets in a variety of commodity price environments.
59
The following table presents our historical estimated oil, natural gas and NGL proved reserves as of December 31, 2025.
| Estimated Proved Reserves as of December 31, 2025 | ||||||||
| Proved Developed Reserves(1) | Proved Reserves(1) | |||||||
| Standardized measure (in millions)(3) | $ | 514,099.2 | ||||||
| Oil (MBbl) | 12,681.3 | 12,681.3 | ||||||
| Natural gas (MMcf) | 312,905.2 | 312,905.2 | ||||||
| NGLs (MBbl) | 25,070.8 | 25,070.8 | ||||||
| Total equivalent (MBoe)(2) | 89,903.0 | 89,903.0 | ||||||
| PV-10 (in millions)(3) | $ | 516,353.0 | $ | 516,353.0 | ||||
| (1) | Our estimated net proved reserves were determined using average first-day-of-the-month prices for the prior 12 months in accordance with SEC regulations. The unweighted arithmetic average first-day-of-the-month prices for the prior 12 months were $75.48 per barrel for oil and $2.13 per MMBtu for natural gas at December 31, 2024 and $65.34 per barrel for oil and $3.387 per MMBtu for natural gas at December 31, 2025. |
| (2) | Presented on an oil-equivalent basis using a conversion of six thousand cubic feet of natural gas to one stock tank barrel of oil. This conversion is based on energy equivalence and not on price or value equivalence. |
| (3) | For more information on how we calculate PV-10 and a reconciliation of PV-10 to standardized measure, see “Management’s Discussion and Analysis of Financial Condition and Results of Operations of the Predecessor — Non-GAAP Financial Measures — Reconciliation of PV-10 to Standardized Measure.” |
Development Plan and Capital Budget
Our business plan has historically been focused on acquiring and then exploiting the production of our assets. Funding sources for our acquisitions have included proceeds from borrowings under the RBL Facility, contributions from our equity partners, the issuance of asset-backed securities and cash flow from operating activities. We spent approximately $0.7 million in 2024 on development costs and spent approximately $3.4 million in 2025 on development costs.
During the year ended December 31, 2024, we spent approximately $1.3 million on remedial workovers and other capital projects, $2.9 million on property and equipment capital projects, and $2.2 million on acquisitions. We also divested $1.4 million of non-operated interests to the respective operators during this period. During the year ended December 31, 2025, we spent approximately $4.2 million on remedial workovers and other capital projects, $2.1 million on property and equipment capital projects, and made no acquisitions.
Our development plan and capital budget are based on management’s current expectations and assumptions about future events. While we consider these expectations and assumptions to be reasonable, they are subject to significant business, economic, competitive, regulatory and other risks, contingencies and uncertainties, most of which are difficult to predict and many of which are beyond our control. The amount and timing of these capital expenditures is largely discretionary and within our control. We could choose to defer a portion of these planned capital expenditures depending on a variety of factors, including, but not limited to, prevailing and anticipated commodity prices, the availability of necessary equipment, infrastructure, labor and capital, the receipt and timing of required regulatory permits and approvals and seasonal conditions.
Our Operations
Oil and Gas Reserves and Operating Data
Reserve data
The information with respect to our estimated proved reserves based on SEC pricing (as defined below) presented below has been prepared in accordance with the rules and regulations of the SEC.
60
Reserves presentation
The following tables provide a summary of our estimated proved reserves and related PV-10 of proved reserves as of December 31, 2025, using SEC pricing, based on evaluations prepared by Cawley, Gillespie & Associates, Inc. (“CG&A”), our independent reserve engineer. See “— Preparation of Reserve Estimates” for the definitions of proved and probable reserves and the technologies and economic data used in their estimation. Prices were adjusted for quality, energy content, transportation fees and market differentials, as applicable.
Summary reserve data
Our historical SEC reserves, PV-10 and standardized measure of proved reserves were calculated using oil and gas price parameters established by current SEC guidelines, including the use of an average effective price, calculated as prices equal to the 12-month unweighted arithmetic average of the first day of the month prices for each of the preceding 12 months as adjusted for location and quality differentials, unless prices are defined by contractual arrangements, excluding escalations based on future conditions (“SEC pricing”). These prices were adjusted for differentials on a per-property basis, which may include local basis differential, fuel costs and shrinkage. All prices are held constant throughout the lives of the properties.
See “Management’s Discussion and Analysis of Financial Condition and Results of Operations of the Predecessor” and “— Our Operations — Oil and Gas Reserves and Operating Data — Reserve data” in evaluating the material presented below.
| Presidio | ||||
| As of December 31, 2025 SEC Pricing(1) | ||||
| Proved Developed: | ||||
| Oil (MBbl) | 12,681.3 | |||
| Natural gas (MMcf) | 312,905.2 | |||
| Natural gas liquids (MBbl) | 25,070.8 | |||
| Oil equivalent (MBoe) | 89,903.0 | |||
| PV-10 (in millions)(2) | $ | 516,353.0 | ||
| Proved Undeveloped: | ||||
| Oil (MBbl) | 0.0 | |||
| Natural gas (MMcf) | 0.0 | |||
| Natural gas liquids (MBbl) | 0.0 | |||
| Oil equivalent (MBoe) | 0.0 | |||
| PV-10 (in millions)(2) | $ | 0.0 | ||
| Total Proved: | ||||
| Oil (MBbl) | 12,681.3 | |||
| Natural gas (MMcf) | 312,905.2 | |||
| Natural gas liquids (MBbl) | 25,070.8 | |||
| Oil equivalent (MBoe) | 89,903.0 | |||
| Standardized measure (in millions)(2) | $ | 514,099.2 | ||
| PV-10 (in millions)(2) | $ | 516,353.0 | ||
| (1) | Our estimated net proved reserves were determined using average first-day-of-the-month prices for the prior 12 months in accordance with SEC regulations. The unweighted arithmetic average first-day-of-the-month prices for the prior 12 months were $75.48 per barrel for oil and $2.13 per MMBtu for natural gas at December 31, 2024 and $65.34 per barrel for oil and $3.387 per MMBtu for natural gas at December 31, 2025. |
| (2) | PV-10 is a non-GAAP financial measure and represents the present value of estimated future cash inflows from proved oil and gas reserves, less future development and production costs, discounted at 10% per annum to reflect the timing of future cash flows. For more information on how we calculate PV-10 and a reconciliation of PV-10 to standardized measure, see “Management’s Discussion and Analysis of Financial Condition and Results of Operations of the Predecessor — Non-GAAP Financial Measures — Reconciliation of PV-10 to Standardized Measure.” |
61
Preparation of Reserve Estimates
Our reserve estimates as of December 31, 2025 included in this prospectus are based on evaluations prepared by the independent petroleum engineering firm of CG&A in accordance with Standards Pertaining to the Estimating and Auditing of Oil and Gas Reserves Information promulgated by the Society of Petroleum Evaluation Engineers and definitions and guidelines established by the SEC. Our independent reserve engineers were selected for their historical experience and geographic expertise in engineering similar resources.
Under SEC rules, proved reserves are reserves which, by analysis of geoscience and engineering data, can be estimated with reasonable certainty to be economically producible from a given date forward from known reservoirs under existing economic conditions, operating methods and government regulations prior to the time at which contracts providing the right to operate expire, unless evidence indicates that renewal is reasonably certain. The term “reasonable certainty” implies a high degree of confidence that the quantities of oil, natural gas or NGLs actually recovered will equal or exceed the estimate. To achieve reasonable certainty, we and the independent reserve engineers employed technologies that have been demonstrated to yield results with consistency and repeatability. The technologies and other data used in the estimation of our proved reserves include, but are not limited to, well logs, geologic maps and available downhole and production data and well-test data.
Reserve engineering is and must be recognized as a subjective process of estimating volumes of economically recoverable oil, natural gas or NGLs that cannot be measured in an exact manner. The accuracy of any reserve estimate is a function of the quality of available data and of engineering and geological interpretation. As a result, the estimates of different engineers often vary. In addition, the results of drilling, testing and production may justify revisions of such estimates. Accordingly, reserve estimates often differ from the quantities of oil, natural gas or NGLs that are ultimately recovered. Estimates of economically recoverable natural gas and of future net cash flows are based on a number of variables and assumptions, all of which may vary from actual results, including geologic interpretation, prices and future production rates and costs. See the section entitled “Risk Factors” appearing elsewhere in this prospectus.
Internal Controls
Our internal staff of petroleum engineers and geoscience professionals (the “Reserves Engineering Group”) work closely with our independent reserve engineers to ensure the integrity, accuracy and timeliness of data furnished to our independent reserve engineers in their preparation of reserve estimates. The accuracy of any reserve estimate is a function of the quality of available data and of engineering and geological interpretation. As a result, the estimates of different engineers often vary. In addition, the results of drilling, testing and production may justify revisions of such estimates. Accordingly, reserve estimates often differ from the quantities of oil, natural gas and NGLs that are ultimately recovered. See “Risk Factors — Risks Related to Presidio’s Business — Our estimated reserves are based on many assumptions that may prove to be inaccurate. Any material inaccuracies in these reserve estimates or underlying assumptions will materially affect the quantities and present value of our reserves” for more information. The Reserves Engineering Group is responsible for the internal review of reserve estimates, and the technical person employed by us at the time who was primarily responsible for overseeing the preparation of our reserve estimates included in this prospectus has more than 18 years of experience as a reserve engineer and was directly responsible for overseeing the reserves engineering group. The technical person currently primarily responsible for overseeing the preparation of our reserve estimates has more than 12 years of experience in reserve engineering. The Reserves Engineering Group reviews the estimates with our third-party petroleum consultants, CG&A, an independent petroleum engineering firm.
CG&A is a Texas Registered Engineering Firm (F-693), made up of independent registered professional engineers and geologists that have provided petroleum consulting services to the oil and gas industry for over 60 years. The lead evaluator that prepared the reserve report was W. Todd Brooker, President at CG&A.
62
Todd has been with CG&A since 1992 and graduated from the University of Texas at Austin in 1989 with a bachelor’s degree in Petroleum Engineering. Todd is a State of Texas registered professional engineer (License #83462) and a member of the Society of Petroleum Engineers. Todd meets or exceeds the education, training, and experience requirements set forth in the Standards Pertaining to the Estimating and Auditing of Oil and Gas Reserves Information promulgated by the Society of Petroleum Engineers; Todd is proficient in judiciously applying industry standard practices to engineering and geoscience evaluations as well as applying SEC and other industry reserves definitions and guidelines.
Proved Undeveloped Reserves (PUDs)
We aim to obtain proved developed producing wells through acquisitions in accordance with our growth strategy rather than through development activities. We accordingly contribute limited capital to development activities. From time to time, when acquiring packages of wells, we will acquire certain locations that are in development by the acquiree at the time of the acquisition or could be developed in the future. Presidio typically monetizes its PUD locations through farm-out arrangements that generally do not require capital investment by Presidio. In compliance with SEC rules, Presidio only books PUD locations for which the farm-out counterparty has represented that the related well is included on its drilling schedule for the next calendar year.
As of December 31, 2025, the Company did not have any proved undeveloped reserves.
The following table summarizes our changes in PUDs, for the year ended December 31, 2025 (in MBoe):
| Balance, December 31, 2024 | 114.0 | |||
| Extensions and discoveries | 0 | |||
| Revisions of previous estimates | (93.8 | ) | ||
| Transfers to proved developed | (20.2 | ) | ||
| Balance, December 31, 2025 | 0.0 |
During the year ended December 31, 2025, revisions to prior estimates reduced proved reserves by 93.8 MBoe, primarily due to completion complications that shortened the producing interval on one well. Additional revisions reflect a slight adjustment to net revenue interest based on the actual completion interval. These revisions were associated with prior-year PUD reserves converted to proved developed during the year. There were no additional or deleted PUDs during the year ended December 31, 2025.
Additionally, we converted 20.2 MBoe of PUDs into proved developed reserves in 2025. Costs incurred relating to the development of all oil and natural gas reserves were $0.3 million during the year ended December 31, 2025.
Oil, Natural Gas and NGL Production Prices and Production Costs
Production and Price History
Prior to the Arkoma Acquisition, we only had production in the Anadarko Basin. The following table sets forth information regarding our production and operating data for the periods indicated.
Production data:
| Successor | Predecessor | |||||||||||
| March 4, 2026 to | January 1, 2026 to | Six Months Ended | ||||||||||
| June 30, 2026 | March 3, 2026 | June 30, 2025 | ||||||||||
| Oil (MBbl) | 423 | 197 | 663 | |||||||||
| Natural Gas (MMcf) | 9,161 | 4,070 | 13,034 | |||||||||
| Natural gas liquids (MBbl) | 743 | 329 | 1,059 | |||||||||
| Total (MBoe) | 2,693 | 1,204 | 3,894 | |||||||||
63
| Year Ended December 31, | ||||||||
| 2025 | 2024 | |||||||
| Oil and condensate sales (MBbl) | 1,288 | 1,425 | ||||||
| Natural gas sales (MMcf) | 25,845 | 27,956 | ||||||
| Natural gas liquids sales (MBbl) | 2,098 | 2,480 | ||||||
| Total (MBoe) | 7,694 | 8,564 | ||||||
| Total (MBoe/d) | 21 | 23 | ||||||
| Total (MBoe) | 7,694 | 8,564 | ||||||
Average realized sales prices:
| Successor | Predecessor | |||||||||||
| March 4, 2026 to | January 1, 2026 to | Six Months Ended | ||||||||||
| June 30, 2026 | March 3, 2026 | June 30, 2025 | ||||||||||
| Oil excluding effects of derivatives (per Bbl) | $ | 93.32 | $ | 61.00 | $ | 64.94 | ||||||
| Natural gas excluding effects of derivatives (per Mcf) | 1.06 | 4.30 | 2.06 | |||||||||
| Natural gas liquids excluding effects of derivatives (per Bbl) | 26.66 | 18.87 | 22.73 | |||||||||
| Total ($/Boe) | $ | 25.61 | $ | 29.67 | $ | 24.12 | ||||||
| Year Ended December 31, | ||||||||
| 2025 | 2024 | |||||||
| Oil and condensate excluding effects of derivatives (per Bbl) | $ | 63.37 | $ | 74.96 | ||||
| Natural gas excluding effects of derivatives (per Mcf) | $ | 1.95 | $ | 0.95 | ||||
| Natural gas liquids excluding effects of derivatives (per Bbl) | $ | 21.86 | $ | 22.74 | ||||
| Total ($/Boe) | $ | 23.11 | $ | 22.15 | ||||
Expense per Boe:
| Successor | Predecessor | |||||||||||
| March 4, 2026 to | January 1, 2026 to | Six Months Ended | ||||||||||
| June 30, 2026 | March 3, 2026 | June 30, 2025 | ||||||||||
| Lease operating expenses | $ | 9.41 | $ | 10.20 | $ | 10.06 | ||||||
| Production taxes (% of oil, natural gas and NGL sales)(1) | $ | 1.47 | $ | 1.74 | $ | 1.34 | ||||||
| Ad valorem taxes | $ | 0.45 | $ | 0.63 | $ | 0.68 | ||||||
| Depletion, oil and gas properties | $ | 7.25 | $ | 3.55 | $ | 3.74 | ||||||
| Depreciation and amortization, other property and equipment | $ | 0.42 | $ | 0.56 | $ | 0.40 | ||||||
| Accretion of asset retirement obligation | $ | 0.56 | $ | 0.53 | $ | 0.52 | ||||||
| General and administrative(2) | $ | 3.29 | $ | 40.40 | $ | 4.54 | ||||||
| Acquisition and transaction costs | $ | 0.29 | $ | 5.81 | $ | 0.20 | ||||||
| Costs of field services revenue | $ | - | $ | 0.01 | $ | 0.03 | ||||||
| (1) | $/Boe is not a useful metric for evaluating taxes. |
| (2) | Includes share-based compensation expense related to restricted stock units for the Successor period from March 4, 2026 through June 30, 2026. Also includes share-based compensation expense associated with the final vesting and settlement of PIH’s Class B units upon the closing of the Business Combination for the Predecessor period from January 1, 2026 through March 3, 2026 and distributions to Class B unitholders following the sale of certain undeveloped properties for the six months ended June 30, 2025 (Predecessor). |
64
| Year Ended December 31, | ||||||||
| 2025 | 2024 | |||||||
| Lease operating expense | $ | 9.49 | $ | 8.25 | ||||
| Production taxes (% of oil, natural gas and NGL sales)(1) | 1.27 | % | 1.21 | % | ||||
| Ad valorem taxes | $ | 0.71 | $ | 0.61 | ||||
| Depletion, oil and gas properties | $ | 3.69 | $ | 3.99 | ||||
| Depreciation and amortization, other property and equipment | $ | 0.43 | $ | 0.35 | ||||
| Accretion of asset retirement obligations | $ | 0.54 | $ | 0.44 | ||||
| General and administrative expense(2) | $ | 3.69 | $ | 0.93 | ||||
| (1) | $/Boe is not a useful metric for evaluating taxes. |
| (2) | Includes distributions to Class B unitholders in 2025 following the sale of certain undeveloped properties. |
Operating Data
The following table sets forth information regarding our revenues, net production volumes, average realized prices and operating expenses for the Predecessor and Successor periods of 2026 and the six months ended June 30, 2025:
| Successor | Predecessor | |||||||||||
| March 4, 2026 to | January 1, 2026 to | Six Months Ended | ||||||||||
| June 30, 2026 | March 3, 2026 | June 30, 2025 | ||||||||||
| Revenues: | ||||||||||||
| Oil | $ | 39,476 | $ | 12,017 | $ | 43,062 | ||||||
| Natural gas | 9,675 | 17,497 | 26,790 | |||||||||
| Natural gas liquids | 19,806 | 6,207 | 24,080 | |||||||||
| Field services revenue | 388 | 155 | 633 | |||||||||
| Total revenues | $ | 69,345 | $ | 35,876 | $ | 94,565 | ||||||
| Average Sales Price: | ||||||||||||
| Oil ($/Bbl) | $ | 62.60 | $ | 54.90 | $ | 56.59 | ||||||
| Natural gas ($/Mcf) | $ | 3.29 | $ | 2.08 | $ | 1.59 | ||||||
| NGL ($/Bbl) | $ | 17.44 | $ | 17.71 | $ | 17.35 | ||||||
| Total ($/Boe) – before effects of realized derivatives | $ | 25.61 | $ | 29.67 | $ | 24.12 | ||||||
| Total ($/Boe) – after effects of realized derivatives | $ | 25.84 | $ | 20.85 | $ | 19.67 | ||||||
| Net Production Volumes: | ||||||||||||
| Oil (MBbl) | 423 | 197 | 663 | |||||||||
| Natural gas (MMcf) | 9,161 | 4,070 | 13,034 | |||||||||
| NGL (MBbl) | 743 | 329 | 1,059 | |||||||||
| Total (MBoe) | 2,693 | 1,204 | 3,894 | |||||||||
| Average daily total volumes (MBoe/d) | 22.6 | 19.4 | 21.5 | |||||||||
65
| Successor | Predecessor | |||||||||||
| March 4, 2026 to | January 1, 2026 to | Six Months Ended | ||||||||||
| ($ in thousands) | June 30, 2026 | March 3, 2026 | June 30, 2025 | |||||||||
| Operating Expenses: | ||||||||||||
| Lease operating expenses | $ | 25,345 | $ | 12,277 | $ | 39,199 | ||||||
| Production taxes | 3,968 | 2,098 | 5,203 | |||||||||
| Ad valorem taxes | 1,208 | 758 | 2,643 | |||||||||
| Depletion, oil and gas properties | 19,535 | 4,276 | 14,564 | |||||||||
| Depreciation and amortization, other property and equipment | 1,122 | 673 | 1,549 | |||||||||
| Accretion of asset retirement obligation | 1,518 | 643 | 2,035 | |||||||||
| General and administrative(1) | 8,864 | 48,649 | 17,701 | |||||||||
| Acquisition and transaction costs | 768 | 6,993 | 775 | |||||||||
| Cost of field services revenue | 4 | 9 | 136 | |||||||||
| Gain on sale of assets | (188 | ) | (816 | ) | (5,793 | ) | ||||||
| Total Operating Expenses | $ | 62,144 | $ | 75,560 | $ | 78,012 | ||||||
| (1) | Includes share-based compensation expense related to restricted stock units for the Successor period from March 4, 2026 through June 30, 2026. Also includes share-based compensation expense associated with the final vesting and settlement of PIH’s Class B units upon the closing of the Business Combination for the Predecessor period from January 1, 2026 through March 3, 2026 and distributions to Class B unitholders following the sale of certain undeveloped properties for the six months ended June 30, 2025 (Predecessor). |
The following table sets forth information regarding our revenues, net production volumes, average realized prices and operating expenses for the year ended December 31, 2024 and the year ended December 31, 2025:
| Year Ended December 31, 2025 | Year Ended December 31, 2024 | |||||||
| ($ in thousands) | ||||||||
| Revenues: | ||||||||
| Oil | $ | 81,640 | $ | 106,854 | ||||
| Natural gas | 50,309 | 26,478 | ||||||
| Natural gas liquids | 45,864 | 56,410 | ||||||
| Total oil, natural gas, and NGL sales | 177,813 | 189,742 | ||||||
| Field services revenue | 1,243 | 2,474 | ||||||
| Total revenues | $ | 179,056 | $ | 192,216 | ||||
| Average Sales Price: | ||||||||
| Oil ($/Bbl) | $ | 63.37 | $ | 74.96 | ||||
| Natural gas ($/Mcf) | $ | 1.95 | $ | 0.95 | ||||
| NGL ($/Bbl) | $ | 21.86 | $ | 22.74 | ||||
| Total ($/Boe) – before effects of realized derivatives | $ | 23.11 | $ | 22.15 | ||||
| Total ($/Boe) – after effects of realized derivatives | $ | 19.36 | $ | 20.40 | ||||
| Net Production Volumes: | ||||||||
| Oil (MBbl) | 1,288 | 1,425 | ||||||
| Natural gas (MMcf) | 25,845 | 27,956 | ||||||
| NGL (MBbl) | 2,098 | 2,480 | ||||||
| Total (MBoe) | 7,694 | 8,564 | ||||||
| Average daily total volumes (MBoe/d) | 21 | 23 | ||||||
66
| ($ in thousands) | Year Ended December 31, 2025 | Year Ended December 31, 2024 | ||||||
| Operating Expenses: | ||||||||
| Lease operating expense | $ | 73,016 | $ | 70,702 | ||||
| Production taxes | 9,795 | 10,347 | ||||||
| Ad valorem taxes | 5,500 | 5,236 | ||||||
| Depletion, oil and gas properties | 28,418 | 34,153 | ||||||
| Depreciation and amortization, other property and equipment | 3,279 | 3,032 | ||||||
| Accretion of asset retirement obligation | 4,134 | 3,765 | ||||||
| General and administrative(1) | 28,372 | 7,995 | ||||||
| Cost of field services revenue | 823 | 1,960 | ||||||
| Gain on sale of assets | (8,455 | ) | (85,573 | ) | ||||
| Total Operating Expenses | $ | 144,882 | $ | 51,617 | ||||
| (1) | Includes distributions to Class B unitholders in 2025 following the sale of certain undeveloped properties. |
Proved Developed Producing Wells
The following table sets forth information regarding our proved developed producing wells as of December 31, 2025:
| As of December 31, 2025 Proved Developed Producing Wells | Average Working | |||||||||||
| Gross | Net | Interest | ||||||||||
| Combined Total: | ||||||||||||
| Natural gas | 2,580 | 1,245 | 48.25 | |||||||||
| Oil | 1,147 | 632 | 55.12 | |||||||||
| Total | 3,727 | 1,877 | 50.37 | |||||||||
Developed and Undeveloped Acreage
The following table sets forth certain information regarding the total developed and undeveloped acreage in which we owned an interest as of December 31, 2025:
| Developed Acres | Undeveloped Acres | Total Acres | ||||||||||
| Gross | 888,334 | 4,184 | 892,518 | |||||||||
| Net | 699,119 | 1,608 | 700,727 | |||||||||
All of our leasehold acreage is held by production and located in the Anadarko Basin.
67
Drilling Results
The table below sets forth the results of our operated drilling activities for the periods indicated. Additionally, the table sets forth the results of non-operated drilling activities in which the company has financial exposure to the drilling and completion operations. The information should not be considered indicative of future performance, nor should it be assumed that there is necessarily any correlation among the number of productive wells drilled, quantities of reserves found or economic value. Productive wells are those that produce, or are capable of producing, commercial quantities of hydrocarbons, regardless of whether they produce a reasonable rate of return. Dry holes are those that prove to be incapable of producing hydrocarbons in sufficient quantities to justify completion.
| Year Ended December 31, 2025 | Year Ended December 31, 2024 | |||||||||||||||
| Gross | Net | Gross | Net | |||||||||||||
| Development Wells Operated: | ||||||||||||||||
| Productive | 0 | 0 | 0 | 0 | ||||||||||||
| Dry holes | 0 | 0 | 0 | 0 | ||||||||||||
| Total Development | 0 | 0 | 0 | 0 | ||||||||||||
| Development Wells Non-Operated: | ||||||||||||||||
| Productive | 1 | 0.055 | 0 | 0 | ||||||||||||
| Dry holes | 0 | 0 | 0 | 0 | ||||||||||||
| Total Development | 1 | 0.055 | 0 | 0 | ||||||||||||
| Total Wells: | ||||||||||||||||
| Productive | 1 | 0.055 | 0 | 0 | ||||||||||||
| Dry holes | 0 | 0 | 0 | 0 | ||||||||||||
| Total Development | 1 | 0.055 | 0 | 0 | ||||||||||||
We drilled no exploratory wells (productive or dry) during the year ended December 31, 2025 or the year ended December 31, 2024.
The following table sets forth information regarding our drilling activities as of December 31, 2025 and December 31, 2024, including with respect to our operated wells we have begun drilling and those which are drilled and awaiting completion.
| As of December 31, 2025 | As of December 31, 2024 | |||||||||||||||
| Gross | Net | Gross | Net | |||||||||||||
| Drilling | 0 | 0 | 0 | 0 | ||||||||||||
| Drilled and Completing | 0 | 0 | 0 | 0 | ||||||||||||
As of December 31, 2025, the Company did not drill or complete any wells. Additionally, as of December 31, 2025, the Company had elected to participate in 0 non-operated gross wells (0 net) that were in process of drilling and completion.
As of December 31, 2024, the Company did not drill or complete any wells. Additionally, as of December 31, 2024, the Company had elected to participate in 0 non-operated gross wells (0 net) that were in process of drilling and completion.
As of December 31, 2025, we were not a party to any long-term drilling rig contracts.
68
Productive Wells
As of December 31, 2025, we owned interests in the following number of productive wells:
| Oil Wells | Gas Wells | Total | ||||||||||
| Gross | 1,147 | 2,580 | 3,727 | |||||||||
| Net | 632 | 1,245 | 1,877 | |||||||||
Marketing and Customers
We market production from properties we operate for both our account and the account of the other working interest owners in these properties. We sell our production to purchasers at market prices.
For the year ended December 31, 2024 and the year ended December 31, 2025, the following companies each represented greater than 10% of our oil and gas accounts receivable balance:
| Year Ended December 31, 2024 | ||||
| Valero Marketing & Supply | 40.22 | % | ||
| ETC Texas Pipeline LTD | 13.10 | % | ||
| Total | 53.32 | % | ||
| Year Ended December 31, 2025 | ||||
| Valero Marketing & Supply | 32.66 | % | ||
| EDF, Inc. | 10.92 | % | ||
| DCP Midstream | 10.64 | % | ||
| Spire Marketing Inc. | 10.03 | % | ||
| Total | 64.25 | % | ||
Gathering and Processing Agreements
We incur gathering and processing expense under various gathering and/or processing agreements with third-party midstream providers. None of our gathering and/or processing agreements includes minimum volume commitments.
Competition
The oil and natural gas industry is intensely competitive, and we compete with other companies that have greater resources. Many of these companies not only explore for and produce natural gas, but also carry on midstream and refining operations and market petroleum and other products on a regional, national or worldwide basis. These companies may be able to pay more for productive oil and natural gas properties or to define, evaluate, bid for and purchase a greater number of properties and prospects than our financial or human resources permit. In addition, these companies may have a greater ability to continue exploration activities during periods of low natural gas market prices. Our ability to acquire additional properties and to discover reserves in the future will be dependent upon our ability to evaluate and select suitable properties and to consummate transactions in a highly competitive environment. In addition, because we have fewer financial and human resources than many companies in our industry, we may be at a disadvantage in evaluating and bidding for oil and natural gas properties.
There is also competition between oil and natural gas producers and other industries producing energy and fuel. Furthermore, competitive conditions may be substantially affected by various forms of energy legislation and/or regulation considered from time to time by the governments of the United States and the jurisdictions in which we operate. It is not possible to predict the nature of any such legislation or regulation which may ultimately be adopted or its effects upon our future operations. Such laws and regulations may substantially increase the costs of developing natural gas and may prevent or delay the commencement or continuation of a given operation. Our larger or more integrated competitors may be able to absorb the burden of existing, and any changes to, federal, state and local laws and regulations more easily than we can, which would adversely affect our competitive position.
69
Seasonality of Business
Generally, demand for natural gas, oil and NGL decreases during the spring and fall months and increases during the summer and winter months. However, certain natural gas and NGL markets utilize storage facilities and purchase some of their anticipated winter requirements during the summer, which can lessen seasonal demand fluctuations. In addition, seasonal anomalies such as mild winters or mild summers can have a significant impact on prices. These seasonal anomalies can pose challenges for meeting our objectives and can increase competition for equipment, supplies and personnel during the spring and summer months, which could lead to shortages, increased costs or delayed operations.
Title to Properties
We believe that we have satisfactory title to substantially all of our active properties in accordance with standards generally accepted in the oil and natural gas industry. Our properties are subject to customary royalty and overriding royalty interests, certain contracts relating to the exploration, development, operation and marketing of production from such properties, consents to assignment and preferential purchase rights, liens for current taxes, applicable laws and other burdens, encumbrances and irregularities in title, which we believe do not materially interfere with the use of or affect the value of such properties. Prior to acquiring producing wells, we endeavor to perform a title investigation on an appropriate portion of the properties that is thorough and is consistent with standard practice in the oil and natural gas industry. Generally, we conduct a title examination and perform curative work with respect to significant defects that we identify on properties that we operate. We believe that we have performed reasonable and protective title reviews with respect to an appropriate cross-section of our operated natural gas and oil wells.
Legislative and Regulatory Environment
Our oil, natural gas and natural gas liquids (“NGLs”) exploration, development, production and related operations and activities are subject to extensive federal, state and local laws, rules and regulations. Failure to comply with such rules and regulations can result in administrative, civil or criminal penalties, compulsory remediation and imposition of natural resource damages or other liabilities. Although the regulatory burden on the natural gas and oil industry increases our cost of doing business and, consequently, affects our profitability, we believe these obligations generally do not impact us differently or to any greater or lesser extent than they affect other operators in the oil and natural gas industry with similar operations and types, quantities and locations of production.
Regulation of Production
In many states, oil and natural gas companies are generally required to obtain permits for drilling operations, provide drilling bonds, file reports concerning operations and meet other requirements related to the exploration, development and production of natural gas, oil and NGLs. Such states also have statutes and regulations addressing conservation matters, including provisions for unitization or pooling of natural gas and oil interests, rights and properties, the surface use and restoration of properties upon which wells are drilled and disposal of water produced or used in the drilling and completion process. These regulations include the establishment of maximum rates of production from natural gas and oil wells, rules as to the spacing, plugging and abandoning of such wells, restrictions on venting or flaring natural gas and requirements regarding the ratability of production, as well as rules governing the surface use and restoration of properties upon which wells are drilled.
These laws and regulations may limit the amount of natural gas, oil and NGLs that can be produced from wells in which we own an interest and may limit the number of wells, the locations in which wells can be drilled, or the method of drilling wells. Additionally, the procedures that must be followed under these laws and regulations may result in delays in obtaining permits and approvals necessary for our operations and therefore our expected timing of drilling, completion and production may be negatively impacted. These regulations apply to us directly as the operator of our leasehold. The failure to comply with these rules and regulations can result in substantial penalties.
70
Regulation of Sales and Transportation of Liquids
Sales of condensate and NGLs are not currently regulated and are made at negotiated prices. Nevertheless, Congress has enacted price controls in the past and could reenact such controls in the future.
Our sales of NGLs are affected by the availability, terms and cost of transportation. The transportation of NGLs in common carrier pipelines is subject to rate and access regulation. The Federal Energy Regulatory Commission (“FERC”) regulates interstate oil, NGLs and other liquid pipeline transportation rates under the Interstate Commerce Act. In general, interstate liquids pipeline rates are set using an annual indexing methodology, however, a pipeline may also use a cost-of-service approach, settlement rates or market-based rates in certain circumstances.
Intrastate liquids pipeline transportation rates are subject to regulation by state regulatory commissions. The basis for intrastate liquids pipeline regulation, and the degree of regulatory oversight and scrutiny given to intrastate liquids pipeline rates, varies from state to state. Insofar as effective interstate and intrastate rates and regulations regarding access are equally applicable to all comparable shippers, we believe that the regulation of liquids transportation will not affect our operations in any way that is of material difference from those of our competitors who are similarly situated.
Regulation of Transportation and Sales of Natural Gas
Historically, the transportation and sale for resale of natural gas in interstate commerce has been regulated by agencies of the U.S. federal government, primarily FERC. In the past, the federal government has regulated the prices at which natural gas could be sold. While sales by producers of natural gas can currently be made at uncontrolled market prices, Congress could reenact price controls in the future. Deregulation of wellhead natural gas sales began with the enactment of the Natural Gas Policy Act of 1978 (the “NGPA”) and culminated in adoption of the Natural Gas Wellhead Decontrol Act which removed controls affecting wellhead sales of natural gas effective January 1, 1993. The transportation and sale for resale of natural gas in interstate commerce is regulated primarily under the Natural Gas Act of 1938 (the “NGA”) and the NGPA, and by regulations and orders promulgated by FERC. In certain limited circumstances, intrastate transportation and wholesale sales of natural gas may also be affected directly or indirectly by laws enacted by Congress and by FERC regulations.
The Energy Policy Act of 2005 (the “EP Act of 2005”) amended the NGA and NGPA to add an anti-market manipulation provision which makes it unlawful for any entity to engage in prohibited behavior to be prescribed by FERC. The EP Act of 2005 also provided FERC with the power to assess civil penalties of up to $1,000,000 per day (adjusted annually for inflation) for violations of the NGA and NGPA. As of 2025, the new adjusted maximum penalty amount is $1,584,648 per violation, per day. The civil penalty provisions are applicable to entities that engage in the sale and transportation of natural gas for resale in interstate commerce.
On January 19, 2006, FERC issued Order No. 670, implementing the anti-market manipulation provision of the EP Act of 2005, and subsequently denied rehearing. The resulting rules make it unlawful, in connection with the purchase or sale of natural gas subject to the jurisdiction of FERC, or the purchase or sale of transportation services subject to the jurisdiction of FERC, for any entity, directly or indirectly, to: (i) use or employ any device, scheme or artifice to defraud; (ii) make any untrue statement of material fact or omit to make any such statement necessary to make the statements made not misleading; or (iii) engage in any act or practice that operates as a fraud or deceit upon any person. The anti-market manipulation rule does not apply to activities that relate only to intrastate or other non-FERC jurisdictional sales or gathering, but does apply to activities of gas pipelines and storage companies that provide interstate services. FERC also interprets its authority to reach otherwise non-jurisdictional entities to the extent the activities are conducted “in connection with” gas sales, purchases or transportation subject to FERC jurisdiction, which includes the annual reporting requirements under Order 704, described below. However, in October 2022, the Fifth Circuit ruled that FERC’s jurisdiction to regulate market manipulation is limited to interstate transactions only and does not reach intrastate natural gas transactions.
71
On December 26, 2007, FERC issued Order 704, a final rule on the annual natural gas transaction reporting requirements, as amended by subsequent orders on rehearing. As a result of these orders, wholesale buyers and sellers of more than 2.2 million MMBtus of physical natural gas in the previous calendar year, including oil and natural gas producers, gatherers and marketers, are now required to report, by May 1 of each year, aggregate volumes of natural gas purchased or sold at wholesale in the prior calendar year to the extent such transactions utilize, contribute to, or may contribute to the formation of price indices. It is the responsibility of the reporting entity to determine which individual transactions should be reported based on the guidance provided by FERC. Market participants must also indicate whether they report prices to any index publishers, and if so, whether their reporting complies with FERC’s policy statement on price reporting.
Gathering service, which occurs upstream of jurisdictional transportation services, is regulated by the states onshore and in state waters. Section 1(b) of the NGA exempts natural gas gathering facilities from regulation by FERC. Although FERC has set forth a general test for determining whether facilities perform a non-jurisdictional gathering facilities function or a jurisdictional transportation function, FERC’s determinations as to the classification of facilities are done on a case-by-case basis. To the extent that FERC issues an order that reclassifies certain non-jurisdictional gathering facilities as jurisdictional transportation facilities, and depending on the scope of that decision, our costs of getting gas to point of sale locations may increase. We believe that the natural gas pipelines in our gathering systems meet the traditional tests FERC has used to establish a pipeline’s status as a gatherer not subject to regulation as a natural gas company. However, the distinction between FERC-regulated transportation services and federally unregulated gathering services could be the subject of ongoing litigation, so the classification and regulation of our gathering facilities could be subject to change based on future determinations by FERC, the courts or Congress. State regulation of natural gas gathering facilities generally includes various occupational safety, environmental and, in some circumstances, nondiscriminatory-take requirements. Although such regulation has not generally been affirmatively applied by state agencies, natural gas gathering may receive greater regulatory scrutiny in the future.
In addition, the pipelines in the gathering systems on which we rely may be subject to regulation by the U.S. Department of Transportation. The Pipeline and Hazardous Materials Safety Administration (“PHMSA”) has established a risk-based approach to determine which gathering pipelines are subject to regulation and what safety standards regulated gathering pipelines must meet. Over the past several years PHMSA has taken steps to expand the regulation of rural gathering lines and impose a number of reporting and inspection requirements on regulated pipelines, and additional requirements are expected in the future. On November 15, 2021, PHMSA released a final rule that expands the definition of regulated gathering pipelines and imposes safety measures on certain currently unregulated gathering pipelines. The final rule also imposes reporting requirements on all gathering pipelines and specifically requires operators to report safety information to PHMSA. The future adoption of laws or regulations that apply more comprehensive or stringent safety standards could increase the expenses we incur for gathering service.
The price at which we sell natural gas is not currently subject to federal rate regulation and, for the most part, is not subject to state regulation. However, with regard to our physical and financial sales of these energy commodities, we are required to observe anti-market manipulation laws and related regulations enforced by FERC under the EP Act of 2005 and by the Commodity Futures Trading Commission (the “CFTC”) under the Commodity Exchange Act (the “CEA”) as amended by the Dodd-Frank Wall Street Reform and Consumer Protection Act, and regulations promulgated thereunder. The CEA prohibits any person from manipulating or attempting to manipulate the price of any commodity in interstate commerce or futures on such commodity. The CEA also prohibits knowingly delivering or causing to be delivered false or misleading or knowingly inaccurate reports concerning market information or conditions that affect or tend to affect the price of a commodity as well as certain disruptive trading practices. Should we violate the anti-market manipulation laws and regulations, we could also be subject to related third-party damage claims by, among others, sellers, royalty owners and taxing authorities.
Intrastate natural gas transportation is also subject to regulation by state regulatory agencies. The basis for intrastate regulation of natural gas transportation and the degree of regulatory oversight and scrutiny given to intrastate natural gas pipeline rates and services varies from state to state. As such regulation within a particular state will generally affect all intrastate natural gas shippers within the state on a comparable basis, we believe that the regulation of similarly situated intrastate natural gas transportation in any states in which we operate and ship natural gas on an intrastate basis will not affect our operations in any way that is of material difference from those of our competitors. Like the regulation of interstate transportation rates, the regulation of intrastate transportation rates affects the marketing of natural gas that we produce, as well as the revenues we receive for sales of our natural gas.
72
Changes in law and to FERC, PHMSA, the CFTC, or state policies and regulations may adversely affect the availability and reliability of firm and/or interruptible transportation service on interstate and intrastate pipelines, and we cannot predict what future action FERC, PHMSA, the CFTC, or state regulatory bodies will take. We do not believe, however, that any regulatory changes will affect us in a way that materially differs from the way they will affect other oil and natural gas producers and marketers with which we compete.
Regulation of Environmental and Occupational Safety and Health Matters Generally
Our operations are subject to numerous stringent federal, regional, state and local statutes and regulations governing environmental protection, occupational safety and health, and the release, discharge or disposal of materials into the environment, some of which carry substantial administrative, civil and criminal penalties for failure to comply. Applicable U.S. federal environmental laws include, but are not limited to, the CERCLA, the CWA and the CAA. In addition, state and local laws and regulations set forth specific standards for drilling wells, the maintenance of bonding requirements in order to drill or operate wells, the spacing and location of wells, the method of drilling and casing wells, the surface use and restoration of properties upon which wells are drilled, the plugging and abandoning of wells, the prevention and cleanup of pollutants, and other matters. These laws and regulations may, among other things, require the acquisition of permits to conduct exploration, drilling, and production operations; restrict the types, quantities and concentrations of various substances that can be released into the environment in connection with drilling, production and transporting through pipelines; govern the sourcing and disposal of water used in the drilling and completion process; limit or prohibit construction or drilling activities in sensitive areas such as wilderness, wetlands, frontier and other protected areas; require investigatory or remedial actions to prevent or mitigate pollution conditions caused by our operations; impose obligations to reclaim and abandon well sites and pits; establish specific safety and health criteria addressing worker protection; and impose substantial liabilities for pollution resulting from operations or failure to comply with regulatory filings. Additionally, Congress and federal and state agencies frequently revise environmental laws and regulations, and any changes that result in delay or more stringent and costly permitting, waste handling, disposal and clean-up requirements for the oil and gas industry could have a significant impact on our operating costs. Although future environmental obligations are not expected to have a material impact on the results of our operations or financial condition, there can be no assurance that future developments, such as increasingly stringent environmental laws or enforcement thereof, will not cause us to incur material environmental liabilities or costs.
Failure to comply with these laws and regulations may result in the assessment of administrative, civil and criminal fines and penalties, loss of leases, the imposition of investigatory or remedial obligations and the issuance of orders enjoining some or all of our operations in affected areas. These laws and regulations may also restrict the rate of oil and natural gas production below the rate that would otherwise be possible. The regulatory burden on the oil and gas industry increases the cost of doing business in the industry and consequently affects profitability. It is possible that, over time, environmental regulation could evolve to place more restrictions and limitations on activities that may affect the environment, and thus, any changes in environmental laws and regulations or reinterpretation of enforcement policies that result in more stringent and costly well drilling, construction, completion or water management activities or waste handling, storage, transport, disposal, or remediation requirements could require us to make significant expenditures to attain and maintain compliance and may otherwise have a material adverse effect on our results of operations and financial position. We may be unable to pass on such increased compliance costs to our customers. Moreover, accidental releases or spills may occur in the course of our operations, and we cannot be sure that we will not incur significant costs and liabilities as a result of such releases or spills, including any third-party claims for damage to property, natural resources or persons. Although we believe that we are in substantial compliance with applicable environmental laws and regulations and that continued compliance with existing requirements will not have a material adverse impact on our business, there can be no assurance that this will continue in the future.
The following is a summary of the more significant existing environmental and occupational health and safety laws and regulations, as amended from time to time, to which our business operations are subject and for which compliance may have a material adverse impact on our capital expenditures, results of operations or financial position.
73
Hazardous Substances and Wastes
CERCLA, also known as the “Superfund” law, and comparable state laws, impose liability without regard to fault or the legality of the original conduct, on certain classes of persons with respect to the release of a “hazardous substance” into the environment. These classes of persons, or, as termed in CERCLA, potentially responsible parties, include the current and past owners or operators of a disposal site or site where the release occurred and anyone who disposed or arranged for the disposal of the hazardous substances found at such sites. Under CERCLA, such persons may be subject to joint and several, strict liability for the costs of cleaning up the hazardous substances that have been released into the environment and for damages to natural resources. It is not uncommon for neighboring landowners and other third parties to file claims for personal injury and property damage allegedly caused by hazardous substances released into the environment. We are able to control directly the operation of only those wells with respect to which we act as operator. Notwithstanding our lack of direct control over wells operated by others, the failure of an operator other than us to comply with applicable environmental regulations may, in certain circumstances, be attributed to us. We generate materials in the course of our operations that may be regulated as hazardous substances under CERCLA and other environmental laws but we are unaware of any liabilities for which we may be held responsible that would materially and adversely affect our business operations. While petroleum and crude oil fractions are generally not considered hazardous substances under CERCLA and its analogues because of the so-called “petroleum exclusion,” adulterated petroleum products containing other hazardous substances have been treated as hazardous substances in the past.
We also generate solid and hazardous wastes that may be subject to the requirements of the RCRA, and analogous state laws. RCRA regulates the generation, handling, storage, treatment, transport and disposal of nonhazardous and hazardous solid wastes. RCRA specifically excludes “drilling fluids, produced waters and other wastes associated with the development or production of crude oil, natural gas or geothermal energy” from regulation as hazardous wastes. With the approval of the EPA, individual states can administer some or all of the provisions of RCRA and some states have adopted their own, more stringent requirements. However, legislation has been proposed from time to time and various environmental groups have filed lawsuits that, if successful, could result in the reclassification of certain natural gas and oil exploration and production wastes as “hazardous wastes,” which would make such wastes subject to much more stringent handling, disposal and clean-up requirements. Any future loss of the RCRA exclusion for drilling fluids, produced waters and related wastes could result in an increase in our costs to manage and dispose of generated wastes, which could have a material adverse effect on our results of operations and financial position. In addition, in the course of our operations, we generate some amounts of ordinary industrial wastes, such as paint wastes, waste solvents, laboratory wastes and waste compressor oils that may be regulated as hazardous wastes if such wastes are determined to have hazardous characteristics. Although the costs of managing hazardous waste may be significant, we do not believe that our costs in this regard are materially more burdensome than those for similarly situated companies.
We currently own, lease or operate numerous properties that may have been used by prior owners or operators for oil and natural gas development and production activities for many years. Although we believe that we have utilized operating and waste disposal practices that were standard in the industry at the time, hazardous substances, wastes or petroleum hydrocarbons may have been released on, under or from the properties owned or leased by us, or on, under or from other locations, including off-site locations where such substances have been taken for recycling or disposal. In addition, some of our properties may have been operated by third parties or by previous owners or operators whose treatment and disposal of hazardous substances, wastes or petroleum hydrocarbons was not under our control. These properties and the substances disposed or released on, under or from them may be subject to CERCLA, RCRA and/or analogous state laws. Under such laws, we could be required to undertake response or corrective measures, which could include removal of previously disposed substances and wastes, cleanup of contaminated property or performance of remedial plugging or pit closure operations to prevent future contamination.
Water Discharges
The Federal Water Pollution Control Act, also known as the CWA, and comparable state laws impose restrictions and strict controls regarding the discharge of pollutants, including spills and leaks of oil and other natural gas wastes, into or near waters of the United States or state waters. The discharge of pollutants into regulated waters is prohibited, except in accordance with the terms of a permit issued by the EPA or an analogous state agency. The discharge of dredge and fill material into regulated waters, including wetlands, is also prohibited, unless authorized by a permit issued by the U.S. Army Corps of Engineers (the “Corps”). The scope of federal jurisdiction under the CWA over these regulated waters continues to be subject to significant uncertainty and litigation. The EPA and the Corps issued a final rule on the federal jurisdictional reach over waters of the United States in 2015, which never took effect before being replaced by the Navigable Waters Protection Rule (the “NWPR”) in December 2019. A coalition of states and cities, environmental groups, and agricultural groups challenged the NWPR, which was vacated by a federal district court in August 2021. The EPA and Corps underwent a further rulemaking process to attempt to redefine the definition of waters of the United States; however, the U.S. Supreme Court’s decision in Sackett v. EPA invalidated the prior test used by the EPA to determine whether wetlands qualify as navigable waters of the United States, and on September 8, 2023, the EPA and the Corps published a final rule to align the definition of “waters of the United States” with the U.S. Supreme Court’s decision in Sackett v. EPA. In March 2025, the EPA and the Corps announced their intention to undertake a rulemaking process to revise the 2023 rule. On November 20, 2025, the EPA and the Corps published a proposed rule to revise the definition of “waters of the United States” under the CWA to comply with the Sackett decision, which could reduce the number and size of federally jurisdictional waters. To the extent any new rules or court decisions expand the scope of the CWA’s jurisdiction, we could face increased costs and delays with respect to obtaining permits, including for dredge and fill activities in wetland areas.
74
The process for obtaining permits also has the potential to delay our operations. For example, on January 8, 2026, the Corps reissued “Nationwide Permits” that authorize certain dredge and fill activities in jurisdictional wetlands related to pipeline projects, including Nationwide Permit 12 (“NWP 12”), the general permit issued by the Corps for pipelines and utility projects. If new oil and gas pipeline projects are unable to utilize NWP 12 or identify an alternate means of CWA compliance, such projects could be significantly delayed. Additionally, spill prevention, control and countermeasure plans, also referred to as “SPCC plans,” are required by federal law in connection with on-site storage of significant quantities of oil. Compliance may require appropriate containment berms and similar structures to help prevent the contamination of navigable waters by a petroleum hydrocarbon tank spill, rupture or leak.
Safe Drinking Water Act
The SDWA grants the EPA broad authority to take action to protect public health when an underground source of drinking water is threatened with pollution that presents an imminent and substantial endangerment to humans. The SDWA also regulates saltwater disposal wells under the Underground Injection Control Program. The EP Act of 2005 amended the Underground Injection Control provisions of the SDWA to expressly exclude certain hydraulic fracturing from the definition of “underground injection,” but disposal of hydraulic fracturing fluids and produced water or their injection for enhanced oil recovery is not excluded. In 2014, the EPA issued permitting guidance governing hydraulic fracturing with diesel fuels. While we do not currently use diesel fuels in our hydraulic fracturing fluids, we may become subject to federal permitting under the SDWA if our fracturing formula changes.
Air Emissions
The CAA and comparable state laws restrict the emission of air pollutants from many sources, including compressor stations, through the issuance of permits and other requirements. These laws and regulations may require us to obtain pre-approval for the construction or modification of certain projects or facilities expected to produce or significantly increase air emissions, obtain and strictly comply with stringent air permit requirements or utilize specific equipment or technologies to control emissions of certain pollutants. The need to obtain permits has the potential to delay the development of oil and natural gas projects. Over the next several years, we may be required to incur certain capital expenditures for air pollution control equipment or other air emissions related issues. For example, in June 2016, the EPA finalized rules regarding criteria for aggregating multiple small surface sites into a single source for air-quality permitting purposes applicable to the oil and gas industry. These rules could cause small facilities, on an aggregate basis, to be deemed a major source, thereby triggering more stringent air permitting processes and requirements.
If the EPA were to adopt more stringent NAAQS for ozone, under the CAA, state implementation of the revised NAAQS could result in stricter permitting requirements, delay or prohibit our ability to obtain such permits, and result in increased expenditures for pollution control equipment, the costs of which could be significant. In addition, the EPA has adopted rules under the CAA that require the reduction of volatile organic compound and methane emissions from certain fractured and refractured natural gas wells for which well completion operations are conducted and further require that most wells use reduced emission completions, also known as “green completions.” These regulations also establish specific requirements regarding emissions from production-related wet seal and reciprocating compressors, and from pneumatic controllers and storage vessels. In addition, the regulations place requirements to detect and repair volatile organic compound and methane at certain well sites and compressor stations. On July 4, 2025, President Trump signed the One Big Beautiful Bill into law which, among other things, postpones the EPA’s imposition of the recent methane Waste Emissions Charge to 2034, lowers royalties on federal onshore oil and gas leases, and repeals a royalty imposed on waste methane produced from federal oil and gas leases. In November 2025, the EPA issued a final rule extending several compliance deadlines associated with the 2024 New Source Performance Standards (“NSPS OOOOb”) and Emissions Guidelines (“EG OOOOc”) for the oil and gas industry. On February 12, 2026, EPA finalized its rescission of EPA’s 2009 final rule under the Clean Air Act finding that GHGs endanger the public health and welfare of current and future generations and that emissions of GHGs from new motor vehicles contribute to GHG pollution that threatens the public health and welfare. On September 16, 2025, the EPA announced a proposal to end the Greenhouse Gas Reporting Program (“GHGRP”) for all sectors except petroleum and natural gas systems (excluding reporting for natural gas distribution). Reporting for petroleum and natural gas systems under the GHGRP would be deferred until 2034 under the proposal. As a result, there remains considerable uncertainty surrounding regulation of GHG and methane emissions from oil and gas operations.
75
Oil Pollution Act
The OPA establishes strict liability for owners and operators of facilities that are the source of a release of oil into waters of the U.S. The OPA and its associated regulations impose a variety of requirements on responsible parties, including owners and operators of certain facilities from which oil is released, related to the prevention of oil spills and liability for damages resulting from such spills. While liability limits apply in some circumstances, a party cannot take advantage of liability limits if the spill was caused by gross negligence or willful misconduct, resulted from violation of a federal safety, construction or operating regulation, or if the party fails to report a spill or to cooperate fully in the cleanup. Few defenses exist to the liability imposed by the OPA. The OPA imposes ongoing requirements on a responsible party, including the preparation of oil spill response plans and proof of financial responsibility to cover environmental cleanup and restoration costs that could be incurred in connection with an oil spill.
National Environmental Policy Act
Oil and natural gas exploration and production activities on federal lands are subject to NEPA. NEPA requires federal agencies to evaluate major agency actions having the potential to significantly impact the environment. The process involves the preparation of an environmental assessment and, if necessary, an environmental impact statement depending on whether the specific circumstances surrounding the proposed federal action have the potential to significantly impact the environment. The NEPA process involves public input through comments which can alter the nature of a proposed project either by limiting the scope of the project or requiring resource-specific mitigation. NEPA decisions can be appealed through the court system by process participants. This process may result in delaying the permitting and development of projects, may increase the costs of permitting and developing some facilities and could result in certain instances in the cancellation of existing leases. However, the current administration has taken actions to revise the scope of NEPA reviews and the U.S. Supreme Court has recently limited the scope of federal agencies’ obligations related to environmental review pursuant to NEPA in Seven County Infrastructure Coalition v. Eagle County. While these changes are aimed at streamlining NEPA reviews, the ultimate result of these changes is unknown at this time.
Endangered Species Act and Migratory Bird Treaty Act
The ESA restricts activities that may affect endangered or threatened species or their habitat. Similar protections are offered to migratory birds under the MBTA. To the extent that species that are listed under the ESA or similar state laws, or are protected under the MBTA, inhabit the areas where we conduct operations, our operations could be adversely impacted. Moreover, drilling activities may be delayed, restricted or precluded in protected habitat areas or during certain seasons, such as breeding and nesting seasons.
The identification or designation of previously unprotected species as threatened or endangered in areas where underlying property operations are conducted could cause us to incur increased costs arising from species protection measures or could result in limitations on our development activities that could have an adverse impact on our ability to develop and produce reserves. If we were to have a portion of our leases designated as critical or suitable habitat, it could adversely impact the value of our leases.
76
Climate Change
The threat of climate change continues to attract attention in the United States and around the world. Numerous proposals have been made and could continue to be made at the international, national, regional and state levels of government to monitor and limit existing emissions of GHGs. These efforts have included consideration of cap-and-trade programs, carbon taxes, GHG disclosure obligations and regulations that directly limit GHG emissions from certain sources. As a result, our operations are subject to a series of regulatory, political, litigation and financial risks associated with the production and processing of fossil fuels and the emission of GHGs.
If more stringent laws and regulations relating to climate change and GHGs are adopted, it could cause us to incur material expenses to comply with such laws and regulations. These requirements could adversely affect our operations and restrict or delay our ability to obtain air permits for new or modified sources.
For example, there are a number of state and regional efforts to regulate emissions of methane from new and existing sources within the oil and natural gas source category. Compliance with these rules will require enhanced record-keeping practices, the purchase of new equipment, and increased frequency of maintenance and repair activities to address emissions leakage at certain well sites and compressor stations, and also may require hiring additional personnel to support these activities or the engagement of third-party contractors to assist with and verify compliance.
In addition, Congress has from time to time considered adopting legislation to reduce emissions of GHGs, although the current U.S. presidential administration has opposed action aimed at limiting GHG emissions. At the international level, in April 2016, the U.S. joined the international community at the 21st Conference of the Parties of the United Nations Framework Convention on Climate Change in Paris, France, which resulted in an agreement intended to nationally determine their contributions and set GHG emission reduction goals every five years beginning in 2020. The U.S. withdrew from the Paris Agreement, effective on January 27, 2026. Additionally at the international level, the International Court of Justice issued an advisory opinion on July, 23, 2025, stating that all nations have certain obligations to prevent significant harm to the environment under customary duties of international law, which the International Court of Justice interpreted to include the obligation to mitigate climate change, including by the domestic regulation of fossil fuel-related industrial activities and other private actors. It remains uncertain how the International Court of Justice’s advisory opinion could be interpreted or otherwise acted on by nations or other actors, including in ways that could affect our business operations.
Separately, many U.S. state and local leaders and foreign governments have intensified or stated their intent to intensify efforts to support international climate commitments and treaties and have developed programs that are aimed at reducing GHG emissions, such as by means of cap and trade programs, carbon taxes, encouraging the use of renewable energy or alternative low-carbon fuels, or imposing new climate-related reporting requirements. Cap and trade programs, for example, typically require major sources of GHG emissions to acquire and surrender emission allowances in return for emitting those GHGs.
Any legislation or regulatory programs aimed at reducing GHG emissions, addressing climate change more generally, or requiring the disclosure of climate-related information could increase the cost of consuming, and thereby reduce demand for, the oil, natural gas or NGLs we produce or otherwise have an adverse effect on our business, financial condition and results of operations.
There are also increasing financial risks for fossil fuel producers as shareholders, bondholders and lenders currently may elect in the future to shift some or all of their investments into non-fossil fuel energy-related sectors. Certain institutional lenders who provide financing to fossil-fuel energy companies also have shifted their investment practices to those that favor “clean” power sources, such as wind and solar, making those sources more attractive, and some of them may elect not to provide funding for fossil fuel energy companies in the short or long term. Many of the largest U.S. banks have made “net zero” carbon emission commitments and have announced that they will assess financed emissions across their portfolios and take steps to quantify and reduce those emissions. There is also a risk that financial institutions will be pressured or required to adopt policies limiting funding for the fossil fuel sector. Although there has been recent political support to counteract these initiatives, these and other developments in the financial sector could lead to some lenders restricting access to capital for or divesting from certain industries or companies, including the oil and gas sector, or requiring that borrowers take additional steps to reduce their GHG emissions. Any material reduction in the capital available to us could make it more difficult to secure funding for exploration, development and production activities and have an adverse effect on our business, financial condition and results of operations.
77
Hydraulic Fracturing
Hydraulic fracturing is a common practice that is used to stimulate production of oil and/or natural gas from low permeability subsurface rock formations and is important to our business. The hydraulic fracturing process involves the injection of water, proppants and chemicals under pressure into targeted subsurface formations to fracture the hydrocarbon-bearing rock formation and stimulate production of hydrocarbons. Presently, hydraulic fracturing is primarily regulated at the state level, typically by state natural gas commissions, but the practice has become increasingly controversial in certain parts of the country, resulting in increased scrutiny and regulation. For example, the EPA has asserted federal regulatory authority pursuant to the SDWA over certain hydraulic fracturing activities involving the use of diesel fuels in fracturing fluid and published guidance for such activities.
At the state level, a growing number of states, including the states in which we conduct operations, have adopted or are considering regulations that could impose more stringent permitting, disclosure or well construction and monitoring requirements on hydraulic fracturing activities. Local governments may also adopt ordinances within their jurisdictions regulating the time, place and manner of drilling activities in general or hydraulic fracturing activities in particular.
If new or more stringent federal, state or local legal restrictions relating to the hydraulic fracturing process are adopted in areas where we operate, our fracturing activities could become subject to additional permitting and financial assurance requirements, more stringent construction specifications, increased monitoring, reporting and record-keeping obligations, plugging and abandonment requirements and attendant permitting delays or curtailment in the pursuit of exploration, development, or production activities, and perhaps even be precluded from drilling wells. Such changes could cause us to incur substantial compliance costs, and compliance or the consequences of any failure to comply by us could have a material adverse effect on our financial condition and results of operations. At this time, it is not possible to estimate the impact on our business of newly enacted or potential legislation or regulation governing hydraulic fracturing, and any of the above risks could impair our ability to manage our business and have a material adverse effect on our operations, cash flows and financial position.
Worker Health and Safety
We are subject to a number of federal and state laws and regulations, including OSHA, and comparable state statutes, whose purpose is to protect the health and safety of workers. For example, the OSHA hazard communication standard, the Emergency Planning and Community Right-to-Know Act and comparable state statutes and any implementing regulations require that we maintain, organize and/or disclose information about hazardous materials used or produced in our operations and that this information be provided to employees, state and local governmental authorities and citizens. Other OSHA standards regulate specific worker safety aspects of our operations. Failure to comply with OSHA requirements can lead to the imposition of penalties.
Related Permits and Authorizations
Many environmental laws require us to obtain permits or other authorizations from state and/or federal agencies before initiating certain drilling, construction, production, operation or other oil and natural gas activities, and to maintain these permits and compliance with their requirements for ongoing operations. These permits are generally subject to protest, appeal or litigation, which can in certain cases delay or halt projects and cease production or operation of wells, pipelines and other operations.
78
Related Insurance
We maintain insurance against some contamination risks associated with our development activities, including a coverage policy for gradual pollution events. However, this insurance is limited to activities at the well site and there can be no assurance that this insurance will continue to be commercially available or that this insurance will be available at premium levels that justify its purchase by us. The occurrence of a significant event that is not fully insured or indemnified against could have a materially adverse effect on our financial condition and operations.
Human Capital Resources
We aim to provide a safe, healthy, respectful, and fair workplace for all employees. We believe our employees’ talent and wellbeing is foundational to delivering on our corporate strategy, and that intentional human capital management strategies enable us to attract, develop, retain and reward our dedicated employees.
As of June 30, 2026, we had 142 total employees, all of whom were full-time employees. From time to time, we utilize the services of independent contractors to perform various field and other services. We are not a party to any collective bargaining agreements and have not experienced any strikes or work stoppages. In general, we believe that employee relations are satisfactory.
Employee Safety and Health
The health, safety, and well-being of our employees is a top priority. In addition to our commitment to complying with all applicable safety, health, and environmental laws and regulations, we are focused on minimizing the risk of workplace incidents and preparing for emergencies as a priority element of our culture. We work to reduce safety incidents in our business and actively seek opportunities to make safety culture and procedural improvements.
Legal Proceedings
The Company may, from time to time, be involved in litigation and claims arising out of its operations in the normal course of business. The Company is not currently a party to any material legal proceedings. In addition, the Company is not aware of any material legal proceedings contemplated to be brought against the Company.
The Company, as an owner and operator of oil and gas properties, is subject to various federal, state and local laws and regulations relating to discharge of materials into, and protection of, the environment. These laws and regulations may, among other things, impose liability on the lessee under an oil and gas lease for the cost of pollution cleanup resulting from operations and subject the lessee to liability for pollution damages. In some instances, the Company may be directed to suspend or cease operations in the affected area. The Company maintains insurance coverage that is customary in the industry, although the Company is not fully insured against all environmental risks.
The Company is not aware of any environmental claims existing as of June 30, 2026. There can be no assurance, however, that current regulatory requirements will not change, or past non-compliance with environmental issues will not be discovered on the Company’s oil and gas properties.
79
MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS OF PRESIDIO PRODUCTION COMPANY
Overview
Presidio is an independent energy company headquartered in Texas and founded in 2017. The Company is primarily engaged in oil and gas exploration and production, with operations concentrated across the Western Anadarko Basin of Texas, Oklahoma, and Kansas. The Company’s strategy is centered on acquiring existing producing assets and applying engineering expertise and AI data driven analytics to enhance performance and extend asset life. The proven business model is designed to create sustainable value by investing in long-lived reserves, reducing emissions, improving asset integrity, and generating consistent, hedge-protected cash flow. Unlike many peers focused on new resource development, Presidio maximizes value by fully exploiting existing reserves — safely and efficiently operating wells to extend their productive lives and economic contribution.
Management places emphasis on operating cash flow in managing the business as operating cash flow considers the cash expenses incurred during the period and excludes non-cash expenditures not directly related to operations.
Key Factors Affecting Performance
Presidio’s revenues, cash flows from operations and future growth depend substantially upon:
| ● | the prices and the supply and demand for oil and natural gas; |
| ● | the quantity of oil and natural gas production from its wells; |
| ● | changes in the fair value of the derivative instruments used to reduce exposure to fluctuations in the price of oil and natural gas; |
| ● | the ability to continue to identify and acquire high-quality strategic acquisition opportunities; and |
| ● | the level of operating expenses. |
In addition to the factors that affect companies in the industry generally, the Company’s operating results are subject to factors specifically impacting the areas of operation in Texas, Oklahoma, and Kansas. These factors include the potential adverse impact of weather on production and transportation activities, particularly during the winter and spring months, as well as infrastructure limitations, transportation capacity, regulatory matters and other factors that may specifically affect this region.
Market Conditions
Commodity price fluctuations can materially affect the value of oil and natural gas reserves, as well as revenues and cash flows, regardless of operating performance. Future movements in oil, natural gas, and natural gas liquids (“NGLs”) prices are inherently unpredictable, and historically such prices have been highly volatile. Management expects this volatility to continue. To mitigate a portion of its exposure to commodity price swings and basis differentials, the Company utilizes derivative instruments.
The oil and natural gas industry is subject to numerous risks and uncertainties. Actual results may differ materially due to factors including, but not limited to, fluctuations in commodity prices; shifts in supply and demand; regulatory changes; economic conditions; competitive dynamics; capital availability; weather; depletion rates of existing oil and natural gas wells; customers’ willingness to invest in new development; and geopolitical events.
Current uncertainties impacting market conditions include the ongoing war in Ukraine, conflict in the Middle East, interest rate volatility, global and regional supply chain disruptions, and the potential imposition of new tariffs. Additional pressures such as OPEC+’s decision to potentially increase production beginning in November 2025, concerns over a potential economic slowdown or recession, and instability in the financial sector have contributed to recent pricing volatility and are expected to continue influencing markets through 2026 and beyond.
80
At the local level, the Company remains dependent on the reliability and performance of infrastructure required to gather, process, and transport its crude oil, natural gas and NGLs.
Pursuant to the terms of its ABS III Notes and Citizens RBL, the Company is required to employ a hedging strategy in which we, at all times, maintain 24 months in the case of the ABS III Notes and 36 months in the case of the Citizens RBL of commodity hedges in an amount not less than 85% and 75%, respectively, of the projected production of oil, natural gas and NGLs, limiting downside risk from material change in commodity prices. Even so, the remainder of the Company’s unhedged production exposed to commodity price volatility would negatively impact the Company’s results of operations if commodity prices were to decline materially from current levels.
Presidio’s price hedging strategy and future hedging transactions will be determined at management’s discretion, subject to terms of certain agreements governing the Company’s indebtedness. The prices at which the Company hedges future production will depend on prevailing commodity prices at the time such transactions are executed, which may be significantly higher or lower than current levels. Accordingly, while the hedging strategy provides downside protection against commodity price volatility, it may also limit upside during periods of rising prices.
Prices for various quantities of oil, natural gas and NGLs that are produced significantly impact revenues and cash flows. The following table summarizes average commodity prices for the periods presented with Henry Hub on a per Mcf basis, and with Mont Belvieu and WTI on a per barrel of oil basis:
| Three Months Ended June 30, | Six Months Ended June 30, | |||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||
| WTI (per Bbl) | $ | 92.44 | $ | 63.95 | $ | 82.27 | $ | 68.12 | ||||||||
| Henry Hub (per Mcf) | $ | 2.90 | $ | 3.44 | $ | 3.98 | $ | 3.66 | ||||||||
| Mont Belvieu (per Bbl) | $ | 32.96 | $ | 26.63 | $ | 30.05 | $ | 35.29 | ||||||||
Commodity Prices
WTI Oil Pricing
The average WTI oil price was $92.44 per Bbl for the three months ended June 30, 2026 (Successor), a 45% increase from $63.95 per Bbl for the three months ended June 30, 2025 (Predecessor). Settled derivatives reduced realized oil prices by $30.69 per Bbl in the three months ended June 30, 2026 (Successor), compared to a reduction of $4.51 per Bbl in the three months ended June 30, 2025 (Predecessor).
The average WTI oil price was $82.27 per Bbl for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, a 21% increase from $68.12 per Bbl for the six months ended June 30, 2025 (Predecessor). Settled derivatives reduced realized oil prices by $22.90 per Bbl in the six months ended June 30, 2026 on a combined Successor and Predecessor basis, compared to a reduction of $8.35 per Bbl in the six months ended June 30, 2025 (Predecessor).
Henry Hub Natural Gas Pricing
The average Henry Hub natural gas price was $2.90 per Mcf for the three months ended June 30, 2026 (Successor), a 16% decrease from $3.44 per Mcf for the three months ended June 30, 2025 (Predecessor). Settled derivatives increased realized gas prices by $3.15 per Mcf in the three months ended June 30, 2026 (Successor), compared to a reduction of $0.53 per Mcf in the three months ended June 30, 2025 (Predecessor).
The average Henry Hub natural gas price was $3.98 per Mcf for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, a 9% increase from $3.66 per Mcf for the six months ended June 30, 2025 (Predecessor). Settled derivatives increased realized gas prices by $0.87 per Mcf in the six months ended June 30, 2026 on a combined Successor and Predecessor basis, compared to a reduction of $0.47 per Mcf in the six months ended June 30, 2025 (Predecessor).
81
Mont Belvieu NGLs Pricing
The average Mont Belvieu NGL price was $32.96 per Bbl for the three months ended June 30, 2026 (Successor), a 24% increase from $26.63 per Bbl for the three months ended June 30, 2025 (Predecessor). Settled derivatives reduced realized NGL prices by $9.30 per Bbl in the three months ended June 30, 2026 (Successor), compared to a reduction of $3.75 per Bbl in the three months ended June 30, 2025 (Predecessor).
The average Mont Belvieu NGL price was $30.05 per Bbl for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, a 15% decrease from $35.29 per Bbl for the six months ended June 30, 2025 (Predecessor). Settled derivatives reduced realized NGL prices by $6.74 per Bbl in the six months ended June 30, 2026 on a combined Successor and Predecessor basis, compared to a reduction of $5.38 per Bbl in the six months ended June 30, 2025 (Predecessor).
Results of Operations
The following tables set forth the results of operations for the three months ended June 30, 2026 (Successor), the period from March 4, 2026 through June 30, 2026 (Successor), the period from January 1, 2026 through March 3, 2026 (Predecessor), and the three and six months ended June 30, 2025 (Predecessor). Average sales prices are derived from accrued accounting data for the relevant period indicated. Due to normal production declines and the effects of acquisitions, the historical information presented below should not be interpreted as indicative of future results.
| Successor | Predecessor | Successor | Predecessor | |||||||||||||||||
| (dollar amounts in thousands, except for per unit amounts) | Three Months Ended June 30, 2026 | Three Months Ended June 30, 2025 | March 4, 2026 to June 30, 2026 | January 1, 2026 to March 3, 2026 | Six Months Ended June 30, 2025 | |||||||||||||||
| Net Production: | ||||||||||||||||||||
| Oil (MBbl) | 325 | 346 | 423 | 197 | 663 | |||||||||||||||
| Natural Gas (MMcf) | 7,047 | 6,688 | 9,161 | 4,070 | 13,034 | |||||||||||||||
| Natural gas liquids (MBbl) | 571 | 551 | 743 | 329 | 1,059 | |||||||||||||||
| Total Production (MBoe) | 2,071 | 2,012 | 2,693 | 1,204 | 3,894 | |||||||||||||||
| Average daily production (MBoe/d) | 22.8 | 22.1 | 22.6 | 19.4 | 21.5 | |||||||||||||||
| Average realized sales price (excluding impact of derivatives settled in cash) | ||||||||||||||||||||
| Oil (per Bbl) | $ | 94.38 | $ | 59.48 | $ | 93.32 | $ | 61.00 | $ | 64.94 | ||||||||||
| Natural gas (per Mcf) | 1.08 | 1.61 | 1.06 | 4.30 | 2.06 | |||||||||||||||
| Natural gas liquids (per Bbl) | 26.94 | 19.99 | 26.66 | 18.87 | 22.73 | |||||||||||||||
| Total (per Boe) | $ | 25.93 | $ | 21.05 | $ | 25.61 | $ | 29.67 | $ | 24.12 | ||||||||||
| Average realized sales price (including impact of derivatives settled in cash) | ||||||||||||||||||||
| Oil (per Bbl) | $ | 63.69 | $ | 54.97 | $ | 62.60 | $ | 54.90 | $ | 56.59 | ||||||||||
| Natural gas (per Mcf) (1) | 4.23 | 1.08 | 3.29 | 2.08 | 1.59 | |||||||||||||||
| Natural gas liquids (per Bbl) | 17.64 | 16.24 | 17.44 | 17.71 | 17.35 | |||||||||||||||
| Total (per Boe) | $ | 29.24 | $ | 17.50 | $ | 25.84 | $ | 20.85 | $ | 19.67 | ||||||||||
| Sales Revenue | ||||||||||||||||||||
| Oil sales | $ | 30,673 | $ | 20,580 | $ | 39,476 | $ | 12,017 | $ | 43,062 | ||||||||||
| Natural gas sales | 7,645 | 10,754 | 9,675 | 17,497 | 26,790 | |||||||||||||||
| Natural gas liquids sales | 15,381 | 11,015 | 19,806 | 6,207 | 24,080 | |||||||||||||||
| Total oil, natural gas and NGLs sales | $ | 53,699 | $ | 42,349 | $ | 68,957 | $ | 35,721 | $ | 93,932 | ||||||||||
| Field services revenue | 301 | 274 | 388 | 155 | 633 | |||||||||||||||
| Total revenue | $ | 54,000 | $ | 42,623 | $ | 69,345 | $ | 35,876 | $ | 94,565 | ||||||||||
| Gain (loss) on settled derivatives | ||||||||||||||||||||
| Oil derivatives settled | $ | (9,975 | ) | $ | (1,559 | ) | $ | (12,998 | ) | $ | (1,201 | ) | $ | (5,546 | ) | |||||
| Natural gas derivatives settled | 22,144 | (3,505 | ) | 20,462 | (9,039 | ) | (6,086 | ) | ||||||||||||
| Natural gas liquids derivatives settled | (5,308 | ) | (2,066 | ) | (6,845 | ) | (381 | ) | (5,703 | ) | ||||||||||
| Net gain (loss) on commodity derivative settlements | $ | 6,861 | $ | (7,130 | ) | $ | 619 | $ | (10,621 | ) | $ | (17,335 | ) | |||||||
| (1) | Includes a one-time realized loss of $2.2 million resulting from the modification of certain natural gas swap contracts concurrent with the Business Combination, incurred in March 2026. |
82
| Successor | Predecessor | Successor | Predecessor | |||||||||||||||||
| (dollar amounts in thousands, except for per unit amounts) | Three Months Ended June 30, 2026 | Three Months Ended June 30, 2025 | March 4, 2026 to June 30, 2026 | January 1, 2026 to March 3, 2026 | Six Months Ended June 30, 2025 | |||||||||||||||
| Costs and Expenses (per Boe) | ||||||||||||||||||||
| Lease operating expenses | $ | 9.39 | $ | 10.06 | $ | 9.41 | $ | 10.20 | $ | 10.06 | ||||||||||
| Production taxes (1) | $ | 1.42 | $ | 1.10 | $ | 1.47 | $ | 1.74 | $ | 1.34 | ||||||||||
| Ad valorem taxes | $ | 0.41 | $ | 0.68 | $ | 0.45 | $ | 0.63 | $ | 0.68 | ||||||||||
| Depletion, oil and gas properties | $ | 7.31 | $ | 3.62 | $ | 7.25 | $ | 3.55 | $ | 3.74 | ||||||||||
| Depreciation and amortization, other property and equipment | $ | 0.41 | $ | 0.38 | $ | 0.42 | $ | 0.56 | $ | 0.40 | ||||||||||
| Accretion of asset retirement obligation | $ | 0.56 | $ | 0.51 | $ | 0.56 | $ | 0.53 | $ | 0.52 | ||||||||||
| General and administrative (2) | $ | 3.46 | $ | 0.59 | $ | 3.29 | $ | 40.40 | $ | 4.54 | ||||||||||
| Acquisition and transaction costs | $ | 0.26 | $ | 0.18 | $ | 0.29 | $ | 5.81 | $ | 0.20 | ||||||||||
| Costs of field services revenue | $ | - | $ | (0.02 | ) | $ | - | $ | 0.01 | $ | 0.03 | |||||||||
| (1) | $/Boe is not a useful metric for evaluating taxes. |
| (2) | Includes share-based compensation expense related to restricted stock units for the three months ended June 30, 2026 (Successor) and the period from March 4, 2026 through June 30, 2026 (Successor). Also includes share-based compensation expense associated with the final vesting and settlement of PIH’s Class B units upon the closing of the Business Combination for the period from January 1, 2026 through March 3, 2026 (Predecessor) and distributions to Class B unitholders following the sale of certain undeveloped properties for the six months ended June 30, 2025 (Predecessor). |
Sources of Our Revenue
Our revenues are primarily generated from the sale of oil, natural gas and NGLs produced from our operated and non-operated wells. Oil is sold at the wellhead under index-based contracts, while natural gas is delivered to third-party midstream processors, who gather, process, and market the product; our reported revenues are net of related gathering, processing, and transportation costs. NGLs are extracted during processing and marketed separately, with net proceeds remitted to us.
We also provide field services through our Trail Dust subsidiary, including compression, FLIR surveys, emissions reduction equipment, tubing scanning, and line locating services, with compression and FLIR surveys representing our most significant service lines. While not material relative to upstream sales, these activities contribute incremental revenues and leverage our operating scale.
In addition, we use commodity derivative contracts to reduce exposure to volatility in oil, natural gas, and NGLs prices. The fair value of these instruments can result in realized and unrealized gains or losses that meaningfully affect reported revenues and cash flows.
Oil, Natural Gas and NGLs Sales
Total oil, natural gas, and NGL revenue for the three months ended June 30, 2026 (Successor) was $53.7 million, a 27% increase from $42.3 million for the three months ended June 30, 2025 (Predecessor). The increase was driven by a 23% increase in average realized sales price (excluding hedges) and a 3% increase in production. Pricing changes included a 59% increase in oil prices and a 35% increase in NGLs prices, offset by a 33% decrease in gas prices. The increase in production was primarily due to the effects of the EQVR Acquisition, offset by natural production declines.
Total oil, natural gas, and NGL revenue for the six months ended June 30, 2026 on a combined Successor and Predecessor basis was $104.7 million, an 11% increase from $93.9 million for the six months ended June 30, 2025 (Predecessor). The increase was driven by an 11% increase in average realized sales price (excluding hedges) and a less than 1% increase in production. Pricing changes included a 28% increase in oil prices and a 7% increase in NGLs prices, offset by a less than 1% decrease in gas prices. The increase in production was primarily due to the effects of the EQVR Acquisition, offset by natural production declines.
83
Derivative Financial Instruments
The Company recorded the following gain (loss) on derivative financial instruments in the condensed consolidated statement of operations for the periods presented:
| Successor | Predecessor | Successor | Predecessor | |||||||||||||||||
| (dollar amounts in thousands) | Three Months Ended June 30, 2026 | Three Months Ended June 30, 2025 | March 4, 2026 to June 30, 2026 | January 1, 2026 to March 3, 2026 | Six Months Ended June 30, 2025 | |||||||||||||||
| Net gain (loss) on commodity derivative settlements | $ | 6,861 | $ | (7,130 | ) | $ | 619 | $ | (10,621 | ) | $ | (17,335 | ) | |||||||
| Gain (loss) on fair value adjustments of unsettled financial instruments | 17,962 | 29,710 | (8,961 | ) | (17,284 | ) | 21,391 | |||||||||||||
| Total commodity derivative gain (loss) | $ | 24,823 | $ | 22,580 | $ | (8,342 | ) | $ | (27,905 | ) | $ | 4,056 | ||||||||
For the three months ended June 30, 2026 (Successor), the total gain on derivative financial instruments was $24.8 million, compared to a gain of $22.6 million for the three months ended June 30, 2025 (Predecessor). This included a $18.0 million gain from marking unsettled contracts to fair value, down from an $29.7 million gain in the three months ended June 30, 2025 (Predecessor). Cash gains on settled derivatives were $6.9 million for the three months ended June 30, 2026 (Successor), due to lower market prices for natural gas relative to hedge contract prices partially offset by higher crude oil and NGLs prices as compared to hedge contract prices. Cash losses on settled derivatives were $7.1 million for the three months ended June 30, 2025 (Predecessor), primarily reflecting higher market prices for crude oil, natural gas, and NGLs as compared to hedge contract prices.
For the six months ended June 30, 2026 on a combined Successor and Predecessor basis, the total loss on derivative financial instruments was $36.2 million, compared to a gain of $4.1 million for the six months ended June 30, 2025. This included a $26.2 million loss from marking unsettled contracts to fair value, down from an $21.4 million gain in the six months ended June 30, 2025 (Predecessor). Cash losses on settled derivatives were $10.0 million for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, due to higher market prices for crude oil and NGLs as compared to hedge contract prices, as well as a $2.2 million realized loss resulting from the modification of certain natural gas swap contracts concurrent with the Business Combination, partially offset by lower market prices for natural gas relative to hedge contract market prices. Cash losses on settled derivatives were $17.3 million for the six months ended June 30, 2025 (Predecessor), primarily reflecting higher market prices for crude oil, natural gas, and NGLs as compared to hedge contract prices.
These gains and losses are consistent with the Company’s risk management strategy. With scheduled debt principal payments central to the capital plan, the Company maintains hedge coverage levels designed to protect downside risk - even if that means forgoing upside during periods of rising prices.
Principal Components of Our Cost Structure
Our cost structure includes several categories that impact operating results in different ways. Lease operating expenses represent the direct costs of producing oil and natural gas, including labor, utilities, chemicals, and equipment maintenance. These expenses tend to fluctuate with production levels but also reflect the impact of fixed field costs that do not vary with volumes. We also incur production and ad valorem taxes, which are levied by state and local governments as a percentage of commodity revenues and assessed property values. These taxes generally move in line with product revenues.
Depreciation, depletion, and accretion are non-cash charges that reflect the consumption of our proved reserves, the depreciation of other property and equipment, and the passage of time on asset retirement obligations. General and administrative expenses consist of corporate overhead, employee compensation, and professional services that support the business and are largely fixed in nature. In addition, we incur costs directly associated with our field services revenues, including labor, maintenance, and other expenses necessary to support compression, reclamation, and emissions-related activities.
Some of these costs vary with commodity prices, some trend with production activity and type, and others primarily reflect fixed or discretionary expenditures.
84
Lease Operating Expenses
Lease operating expenses (“LOE”) were $19.5 million for the three months ended June 30, 2026 (Successor), compared to $20.2 million for the three months ended June 30, 2025 (Predecessor). On a per Boe basis, LOE per Boe decreased 7% to $9.39 per Boe for the three months ended June 30, 2026 (Successor), from $10.06 per Boe for the three months ended June 30, 2025 (Predecessor). The decrease in LOE per Boe was primarily driven by the addition of production from the EQVR Acquisition, partially offset by a decline in base production.
LOE were $37.6 million for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, compared to $39.2 million for the six months ended June 30, 2025. On a per Boe basis, LOE per Boe decreased 4% to $9.65 per Boe for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, from $10.06 per Boe for the six months ended June 30, 2025 (Predecessor). The decrease in LOE per Boe was primarily driven by the addition of production from the EQVR Acquisition, partially offset by a decline in base production.
Production Taxes
Production and other taxes are paid on produced oil and natural gas based on rates established by federal, state, or local taxing authorities. In general, production and other taxes paid correlate to changes in oil, natural gas and NGLs revenues. Production taxes are based on the market value of production at the wellheads.
Production taxes totaled $2.9 million ($1.42 per Boe) for the three months ended June 30, 2026 (Successor), compared to $2.2 million ($1.10 per Boe) for the three months ended June 30, 2025 (Predecessor). The increase primarily reflects higher revenues.
Production taxes totaled $6.1 million ($1.56 per Boe) for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, compared to $5.2 million ($1.34 per Boe) for the six months ended June 30, 2025 (Predecessor). The increase primarily reflects higher revenues.
Ad Valorem Taxes
The Company’s properties in Oklahoma, Texas and Kansas are also subject to ad valorem taxes in the counties where the production is located. Ad valorem taxes are based on the fair market value of mineral interests for producing wells.
Ad valorem taxes totaled $0.9 million ($0.41 per Boe) for the three months ended June 30, 2026 (Successor), compared to $1.4 million ($0.68 per Boe) for the three months ended June 30, 2025 (Predecessor).
Ad valorem taxes totaled $2.0 million ($0.50 per Boe) for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, compared to $2.6 million ($0.68 per Boe) for the six months ended June 30, 2025 (Predecessor).
Depreciation, Depletion and Amortization
Depreciation, depletion and amortization (“DD&A”) totaled $16.0 million ($7.72 per Boe) for the three months ended June 30, 2026 (Successor), compared to $8.0 million ($4.00 per Boe) for the three months ended June 30, 2025 (Predecessor). The increase was primarily attributable to higher oil and gas properties values resulting from the Business Combination.
DD&A totaled $25.6 million ($6.57 per Boe) for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, compared to $16.1 million ($4.14 per Boe) for the six months ended June 30, 2025 (Predecessor). The increase was primarily attributable to higher oil and gas properties values resulting from the Business Combination.
General and Administrative
General and administrative (“G&A”) expense totaled $7.2 million for the three months ended June 30, 2026 (Successor), compared to $1.2 million for the three months ended June 30, 2025 (Predecessor). The increase was driven by $2.2 million of compensation expense related to RSUs and $3.9 million of incremental personnel and other costs since the closing of the Business Combination.
G&A expense totaled $57.5 million for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, compared to $17.7 million for the six months ended June 30, 2025 (Predecessor). The increase was driven by $47.0 million of compensation expense recognized in connection with the accrual of a share-based compensation liability associated with the final vesting and settlement of PIH’s Class B units upon the closing of the Business Combination, $2.7 million of compensation expense related to RSUs, and $5.4 million of incremental personnel and other costs since the closing of the Business Combination, which was offset by a $15.0 million PIH Class B unit compensation payout in the prior period.
85
Acquisition and Transaction Costs
Acquisition and transaction costs totaled $0.5 million for the three months ended June 30, 2026 (Successor), compared to $0.4 million for the three months ended June 30, 2025 (Predecessor). Costs were relatively consistent between periods.
Acquisition and transaction costs totaled $7.8 million for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, compared to $0.8 million for the six months ended June 30, 2025 (Predecessor). The increase was driven primarily by $7.5 million of transaction costs recognized in the combined Successor and Predecessor periods in connection with the Business Combination.
Interest Expense
Interest expense totaled $4.3 million for the three months ended June 30, 2026 (Successor), compared to $6.1 million for the three months ended June 30, 2025 (Predecessor). The decrease reflects the repayments of the principal under the ABS facility, which requires monthly interest and amortization determined by deal-specific metrics, including production volumes, commodity pricing, and operating costs.
Interest expense totaled $9.9 million for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, compared to $12.4 million for the six months ended June 30, 2025 (Predecessor). The decrease reflects the repayments of the principal under the ABS facility, which requires monthly interest and amortization determined by deal-specific metrics, including production volumes, commodity pricing, and operating costs.
Loss on Early Extinguishment of Debt
For the three months ended June 30, 2026 (Successor) and the six months ended June 30, 2026 on a combined Successor and Predecessor basis, we recognized a loss on early extinguishment of debt totaling $4.5 million, related to the loss associated with the redemption of the ABS II Notes in connection with the June 2026 refinancing described in Note 7 - Debt to the condensed consolidated financial statements. We did not recognize any loss on early extinguishment of debt during the three or six months ended June 30, 2025 (Predecessor).
Non-GAAP Financial Measures
Adjusted EBITDA
We include in this report the supplemental non-GAAP financial performance measure Adjusted EBITDA and provide our calculation of Adjusted EBITDA and a reconciliation of Adjusted EBITDA to net income (loss), our most directly comparable financial measure calculated and presented in accordance with GAAP. We define Adjusted EBITDA as net income (loss) before (1) interest expense, net, (2) depreciation, depletion, amortization and accretion, (3) unrealized loss (gain) on derivative instruments, (4) non-cash share-based compensation, (5) non-recurring compensation expense related to our Class B Units, (6) (gain) loss on sale of assets, net, (7) loss on ARO liabilities, (8) change in fair value of earnout liability, (9) loss on early extinguishment of debt, (10) income tax expense (benefit), (11) acquisition and transaction costs, and (12) certain non-recurring costs.
Adjusted EBITDA is used as a supplemental financial performance measure by Presidio management and by external users of our financial statements, such as industry analysts, investors, lenders, rating agencies and others, to evaluate our operating performance and Presidio’s results of operation from period to period and against our peers without regard to financing methods, capital structure or historical cost basis. We exclude the items listed above from net income (loss) in arriving at Adjusted EBITDA because these items and related amounts can vary substantially from company to company within our industry depending upon accounting methods and book values of assets, capital structures and the method by which the assets were acquired. Adjusted EBITDA is not a measurement of our financial performance under GAAP and should not be considered as an alternative to, or more meaningful than, net income (loss) as determined in accordance with GAAP or as indicators of our operating performance. Certain items excluded from Adjusted EBITDA are significant components in understanding and assessing a company’s financial performance, such as a company’s cost of capital and tax burden, as well as the historic costs of depreciable assets, none of which are reflected in Adjusted EBITDA. Our presentation of Adjusted EBITDA should not be construed as an inference that our results will be unaffected by unusual items. Our computations of Adjusted EBITDA may not be identical to other similarly titled measures of other companies.
86
Adjusted Unhedged EBITDA
We also present Adjusted Unhedged EBITDA, which we define as Adjusted EBITDA further adjusted to remove realized gains and losses on derivative instruments. This measure is intended to show our operating results without the impact of our hedging program. Management believes Adjusted Unhedged EBITDA is an important metric that provides valuable insight into the Company’s underlying operational performance by removing the effects of financing decisions, non-cash charges, and hedging activities. Adjusted Unhedged EBITDA is a supplemental non-GAAP measure and may not be comparable to similarly titled measures of other companies.
Reconciliations of GAAP Financial Measures to Adjusted EBITDA
The following table presents our reconciliation of the GAAP financial measure of net income (loss) to the non-GAAP financial measure Adjusted EBITDA and Adjusted Unhedged EBITDA, as applicable, for each of the periods indicated.
| Successor | Predecessor | Successor | Predecessor | |||||||||||||||||
| (dollar amounts in thousands) | Three Months Ended June 30, 2026 | Three Months Ended June 30, 2025 | March 4, 2026 to June 30, 2026 | January 1, 2026 to March 3, 2026 | Six Months Ended June 30, 2025 | |||||||||||||||
| Net Income (Loss) (GAAP) | $ | 15,479 | $ | 24,472 | $ | (11,487 | ) | $ | (71,339 | ) | $ | 6,920 | ||||||||
| Depletion, oil and gas properties | 15,130 | 7,283 | 19,535 | 4,276 | 14,564 | |||||||||||||||
| Depreciation of other property and equipment | 859 | 759 | 1,122 | 673 | 1,549 | |||||||||||||||
| Accretion of asset retirement obligation | 1,150 | 1,027 | 1,518 | 643 | 2,035 | |||||||||||||||
| Gain from sale of assets | (158 | ) | (894 | ) | (188 | ) | (816 | ) | (5,793 | ) | ||||||||||
| Loss on ARO liabilities | - | 368 | 149 | - | 700 | |||||||||||||||
| Unrealized (gain) loss from derivative transactions | (17,962 | ) | (29,710 | ) | 8,961 | 17,284 | (21,391 | ) | ||||||||||||
| Change in fair value of earnout liability | 2,972 | - | 2,876 | - | - | |||||||||||||||
| Loss on early extinguishment of debt | 4,475 | - | 4,475 | - | - | |||||||||||||||
| Share-based compensation (1) | 2,219 | - | 2,653 | 46,982 | 15,000 | |||||||||||||||
| Acquisition and transaction costs | 544 | 353 | 768 | 6,993 | 775 | |||||||||||||||
| Interest expense | 4,286 | 6,115 | 6,001 | 3,920 | 12,434 | |||||||||||||||
| Non-recurring cost (2) | 221 | - | 2,406 | - | - | |||||||||||||||
| Income tax expense (benefit) | 3,961 | 962 | (2,993 | ) | - | 962 | ||||||||||||||
| Adjusted EBITDA | $ | 33,176 | $ | 10,735 | $ | 35,796 | $ | 8,616 | $ | 27,755 | ||||||||||
| Realized (gain) loss from derivative transactions (3) | (6,861 | ) | 7,130 | (2,803 | ) | 10,621 | 17,335 | |||||||||||||
| Adjusted Unhedged EBITDA | $ | 26,315 | $ | 17,865 | $ | 32,993 | $ | 19,237 | $ | 45,090 | ||||||||||
| (1) | Includes share-based compensation expense related to restricted stock units for the three months ended June 30, 2026 (Successor) and the period from March 4, 2026 through June 30, 2026 (Successor). Also includes share-based compensation expense associated with the final vesting and settlement of PIH’s Class B units upon the closing of the Business Combination for the period from January 1, 2026 through March 3, 2026 (Predecessor) and distributions to Class B unitholders following the sale of certain undeveloped properties for the six months ended June 30, 2025 (Predecessor). |
| (2) | Includes a one-time realized loss resulting from the modification of certain natural gas swap contracts concurrent with the Business Combination for the period from March 4, 2026 through June 30, 2026 (Successor). Includes a one-time severance fees for the three months ended June 30, 2026 (Successor) and the period from March 4, 2026 through June 30, 2026 (Successor). |
| (3) | Excludes a one-time realized loss resulting from the modification of certain natural gas swap contracts concurrent with the Business Combination for the Successor period from March 4, 2026 through June 30, 2026. There were no one-time adjustments for the three months ended June 30, 2026 (Successor). |
87
Liquidity and Capital Resources
Overview
The Company’s primary sources of liquidity are cash generated from operations and borrowings under its asset-backed securitizations (“ABS”) and credit facility. These long-term, fixed-rate, fully amortizing ABS structures are secured by certain oil and natural gas assets and provide stable borrowing costs while also reducing leverage over time through scheduled principal payments. Restricted cash is held in accounts established under the ABS debt agreements and is reserved primarily for scheduled interest and principal payments, and is therefore not available for general corporate purposes. The credit facility provides additional borrowing capacity, subject to customary conditions, and serves as a source of short-term liquidity for working capital needs. In addition, the Company may seek to raise additional capital through additional equity offerings or debt financing for the purpose of funding acquisitions and other investments.
On March 4, 2026, the Company entered into a Reserve Based Lending instrument with Citizens Bank secured by its WAB assets (“Citizens RBL”). The facility provides additional liquidity with an initial borrowing base of $65.0 million, aggregate maximum credit amounts of $500.0 million, and matures on March 4, 2030. As of June 30, 2026, the Citizens RBL had no outstanding borrowings, following the Company’s repayment in full of the $37.0 million then-outstanding balance on June 9, 2026 in connection with the refinancing described below. This RBL supplements the Company’s existing sources of liquidity and further supports management’s assessment that the Company will be able to satisfy working capital requirements, debt service obligations, and planned capital investments during the look-forward period. However, the Company’s ability to satisfy working capital requirements, debt service obligations, and planned capital investments will ultimately depend on future operating performance, which is subject to prevailing economic conditions in the oil and natural gas industry and other factors beyond management’s control.
Working Capital
The Company monitors working capital to ensure adequate levels for operations, with excess cash primarily allocated to debt paydowns, dividends, and future acquisitions. In addition to working capital management, the Company maintains a disciplined approach to operating cost control and capital allocation, with a focus on reinvesting capital into its operations and generating returns that support strategic business initiatives.
As of June 30, 2026, the Company had cash and cash equivalents of $42.3 million in addition to $11.3 million held in restricted cash required as part of its ABS securitized debt to fund interest payments. As of December 31, 2025, the Company had cash and cash equivalents of $4.1 million and restricted cash of $11.2 million.
Capital expenditures totaled $0.6 million for the three months ended June 30, 2026 (Successor), compared to $0.7 million in the three months ended June 30, 2025 (Predecessor). Capital expenditures totaled $1.3 million for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, compared to $1.3 million in the six months ended June 30, 2025 (Predecessor). Capital expenditures primarily related to operated capital workovers and non-operated asset capital projects. The Company expects to meet its capital expenditure needs for the foreseeable future through operating cash flow and existing cash and cash equivalents.
Future capital requirements will depend on several factors, including the Company’s growth trajectory, acquisition activity, and other strategic considerations.
Debt Facilities and Covenant Compliance
On June 9, 2026, the Company redeemed in full its ABS II Notes for a total of $263.3 million, and issued $350.0 million in ABS III Notes with a final scheduled payment date in 2041 and a weighted-average coupon of 6.31%. Net proceeds from the ABS III Notes were used to redeem the ABS II Notes in full, repay the outstanding balance under the Citizens RBL, fund derivative contract modifications, pay transaction costs, and for general corporate purposes.
We believe this refinancing extends our debt maturity profile, diversifies our note-holder base, and provides additional liquidity to support our capital program. As a result of the refinancing, we recognized a loss on early extinguishment of debt of $4.5 million for the three months ended June 30, 2026 (Successor) and the six months ended June 30, 2026 on a combined Successor and Predecessor basis. See Note 7 - Debt for further discussion.
88
At June 30, 2026, outstanding borrowings under the ABS III Notes totaled $348.1 million, and $2.0 million was drawn on the Trail Dust advancing term loan. The Citizens RBL was repaid in full on June 9, 2026 in connection with the refinancing described above; the facility remained open, with the full $65.0 million borrowing base available for future draws as of June 30, 2026.
At June 30, 2026, we were in compliance with all covenants under the ABS III Notes, the Citizens RBL, and the Trail Dust loan.
At December 31, 2025, outstanding borrowings under the ABS II Notes totaled $266.9 million, and $2.3 million was outstanding under the Trail Dust advancing term loan. Additionally, $3.5 million was drawn on the WAB RBL revolving credit facility, which was established during the third quarter of 2025. At December 31, 2025, we were in compliance with all covenants under the ABS II Notes, Trail Dust loan and the credit facilities.
Future Liquidity Outlook
We expect our liquidity sources will be sufficient to meet operating and financing needs, including scheduled debt service, anticipated capital expenditures, and working capital requirements, for at least the next twelve months and beyond such twelve-month period. Future liquidity will depend on commodity price realizations, production volumes, and hedge settlements. Sustained changes in commodity prices or operating costs may influence our cash flow generation and could require adjustments to our capital allocation priorities, including the pace of reinvestment, distribution levels, or financing strategy. The new Citizens RBL supplements the Company’s existing sources of liquidity and further supports management’s assessment that the Company will be able to satisfy working capital requirements, debt service obligations, and planned capital investments during the look-forward period. However, the Company’s ability to satisfy working capital requirements, debt service obligations, and planned capital investments will ultimately depend on future operating performance, which is subject to prevailing economic conditions in the oil and natural gas industry and other factors beyond management’s control.
Cash Flows
Our cash flows for the six months ended June 30, 2026 and 2025:
| Successor | Predecessor | |||||||||||
| (dollar amounts in thousands) | March 4, 2026 to June 30, 2026 | January 1, 2026 to March 3, 2026 | Six Months Ended June 30, 2025 | |||||||||
| Net cash provided by (used in) operating activities | $ | (97,916 | ) | $ | 5,202 | $ | (1,316 | ) | ||||
| Net cash provided by (used in) investing activities | (139,506 | ) | (168 | ) | 3,949 | |||||||
| Net cash provided by (used in) financing activities | 275,927 | (1,398 | ) | (84,760 | ) | |||||||
| Net change in cash, cash equivalents, and restricted cash | $ | 38,505 | $ | 3,636 | $ | (82,127 | ) | |||||
Operating Activities
Net cash used in operating activities increased $91.4 million for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, as compared to the six months ended June 30, 2025 (Predecessor), primarily due to $92.8 million paid for a derivative contract modification, $23.7 million paid for transaction expenses, partially offset by $15.0 million in incentive compensation payments to Class B unitholders and $7.3 million of higher derivative payments in the prior period.
Investing Activities
Net cash used in investing activities increased by $143.6 million for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, as compared to the six months ended June 30, 2025 (Predecessor), primarily due to $145.5 million in cash paid for acquisitions pursuant to the Business Combination, net of cash acquired, offset by more proceeds received from asset divestitures totaling $8.0 million in the first six months of 2026 compared to proceeds received from asset divestitures of $5.8 million in the same period for 2025.
89
Financing Activities
Net cash provided by financing activities increased by $359.3 million for the six months ended June 30, 2026 on a combined Successor and Predecessor basis, as compared to the six months ended June 30, 2025 (Predecessor). The increase was primarily due to $226.6 million of net proceeds from the common and preferred equity financings, net of deferred issuance costs, and $34.4 million in borrowings under the new Citizens RBL, net of debt issuance costs, in connection with the Business Combination, and $341.4 million in proceeds, net of issuance costs, from the issuance of the ABS III Notes, combined with a $60.0 million member distribution during the six months ended June 30, 2025 (Predecessor). The proceeds of the issuance of the ABS III Notes were partially offset by $262.5 million used to redeem the ABS II Notes and $37.0 million used to repay the outstanding balance under the Citizens RBL in connection with the June 2026 refinancing.
Known Contractual and Other Obligations
Contractual Obligations and Contingent Liabilities and Commitments
The Company has various contractual obligations arising in the normal course of operations and financing activities. These include commitments under the ABS III Notes and Citizens RBL, which require periodic principal and interest payments (see Note 7 of the notes to the condensed consolidated financial statements). Presidio also has contractual obligations that may result in payments upon settlement of commodity derivative contracts (see Note 4 of the notes to the condensed consolidated financial statements). Additionally, the Company maintains both short-term and long-term lease obligations, primarily related to vehicle leases and office facilities.
The Company’s other liabilities represent current and noncurrent other liabilities that are primarily comprised of environmental contingencies, asset retirement obligations and other obligations for which neither the ultimate settlement amounts nor their timings can be precisely determined in advance.
Off-balance Sheet Arrangements
The Company does not have any off-balance sheet arrangements.
Critical Accounting Estimates
This discussion and analysis of our financial and results of operations are based upon our unaudited condensed consolidated financial statements. A complete list of our significant accounting policies is described in Note B - Summary of Significant Accounting Policies in PIH’s audited financial statements as of and for the year ended December 31, 2025 in Exhibit 99.2 of the current report on Form 8-K, as amended and filed with the SEC on March 12, 2026 (“Current Report”). Refer also to “Critical Accounting Estimates” in Management’s Discussion and Analysis of Financial Condition and Results of Operations for PIH in Exhibit 99.3 of the Current Report.
There have been no changes to our significant accounting policies and critical accounting estimates as of June 30, 2026 except as follows.
Purchase Accounting
We accounted for the Business Combination and EQVR Acquisition using the acquisition method which involves the use of significant judgment. Under the acquisition method of accounting, the acquisitions are accounted for at a purchase price based on the fair value of the consideration given. The assets and liabilities acquired are measured at their fair values, and the purchase price is allocated to the assets and liabilities based upon these fair values. The most significant assumptions relate to the estimated fair values assigned to our proved oil and natural gas properties.
90
The assumptions made in performing these valuations include future net production volumes, future commodity prices and costs, future operating and development activities, projections of oil and gas reserves and a weighted average cost of capital rate. The assumptions and inputs used in determining fair value estimates involve significant management judgment and are based on industry, market and economic conditions at the time of the acquisition. While these estimates are based on assumptions considered reasonable, they are inherently uncertain and actual results may differ.
Estimated fair values ascribed to assets acquired can have a significant impact on future results of operations presented in our financial statements. A higher fair value ascribed to a property results in higher DD&A expense, which results in lower net earnings. Fair values are based on estimates of future commodity prices, reserve quantities, development costs and operating costs. In the event that future commodity prices or reserve quantities are lower than those used as inputs to determine estimates of acquisition date fair values, the likelihood increases that certain costs may be determined to not be recoverable. See Note 3 - Business Combinations of our condensed consolidated financial statements for further discussion of business combinations.
Earnout Shares
The fair value of the Earnout Shares liability was determined using Monte Carlo simulations that require significant unobservable inputs. The assumptions used could have a material impact on the valuation of these liabilities, and include our best estimate of expected volatility and expected holding periods. Changes in the estimated fair values of these liabilities may have material impacts on our results of operations in any given period, as any increases in these liabilities have a corresponding negative impact on our U.S. GAAP results of operations in the period in which the changes occur.
Income Taxes
Deferred tax assets and liabilities are recognized using enacted tax rates for the estimated future tax effects of temporary differences between the book and tax basis of recorded assets and liabilities. Deferred tax assets are reduced by a valuation allowance if it is more likely than not that some portion of the deferred tax asset will not be realized. All available evidence, both positive and negative, must be considered in determining the need for a valuation allowance.
The Company evaluates all tax positions taken on the state and federal tax filings to determine if the position is more likely than not to be sustained upon examination. For positions that meet the more likely than not to be sustained criteria, an evaluation of the largest amount of benefit, determined on a cumulative probability basis that is more likely than not to be realized upon ultimate settlement is determined. A previously recognized tax position is reversed when it is subsequently determined that a tax position no longer meets the more likely than not threshold to be sustained. The evaluation of the sustainability of a tax position and the probable amount that is more likely than not is based on judgment, historical experience and on various other assumptions that we believe are reasonable under the circumstances. The results of these estimates, which are not readily apparent from other sources, form the basis for establishing unrecognized tax benefits. Actual results could differ from those estimates upon the subsequent resolution of identified matters.
New Accounting Pronouncements
The effects of new accounting pronouncements are discussed in Note 2 - Basis of Presentation and Summary of Significant Accounting Policies of the condensed consolidated financial statements.
91
MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS OF THE PREDECESSOR
Overview
PIH is an independent energy company headquartered in Texas and founded in 2017. The Company is primarily engaged in oil and gas exploration and production, with operations concentrated across the Western Anadarko Basin of Texas, Oklahoma, and Kansas. The Company’s strategy is centered on acquiring existing producing assets and applying engineering expertise to enhance performance and extend asset life. The proven business model is designed to create sustainable value by investing in long-lived reserves, reducing emissions, improving asset integrity, and generating consistent, hedge-protected cash flow. Unlike many peers focused on new resource development, PIH maximizes value by fully exploiting existing reserves — safely and efficiently operating wells to extend their productive lives and economic contribution.
Management places emphasis on operating cash flow in managing the business as operating cash flow considers the cash expenses incurred during the period and excludes non-cash expenditures not directly related to operations.
Key Factors Affecting Performance
PIH’s revenues, cash flows from operations and future growth depend substantially upon:
| ● | the prices and the supply and demand for oil and natural gas; |
| ● | the quantity of oil and natural gas production from its wells; |
| ● | changes in the fair value of the derivative instruments used to reduce exposure to fluctuations in the price of oil and natural gas; |
| ● | the ability to continue to identify and acquire high-quality strategic acquisition opportunities; and |
| ● | the level of operating expenses. |
In addition to the factors that affect companies in the industry generally, the Company’s operating results are subject to factors specifically impacting the areas of operation in Texas, Oklahoma, and Kansas. These factors include the potential adverse impact of weather on production and transportation activities, particularly during the winter and spring months, as well as infrastructure limitations, transportation capacity, regulatory matters and other factors that may specifically affect this region.
Market Conditions
Commodity price fluctuations can materially affect the value of oil and natural gas reserves, as well as revenues and cash flows, regardless of operating performance. Future movements in oil, natural gas, and natural gas liquids prices are inherently unpredictable, and historically such prices have been highly volatile. Management expects this volatility to continue. To mitigate a portion of its exposure to commodity price swings and basis differentials, the Company utilizes derivative instruments.
92
The oil and natural gas industry is subject to numerous risks and uncertainties. Actual results may differ materially due to factors including, but not limited to, fluctuations in commodity prices; shifts in supply and demand; regulatory changes; economic conditions; competitive dynamics; capital availability; weather; depletion rates of existing oil and natural gas wells; customers’ willingness to invest in new development; and geopolitical events.
Current uncertainties impacting market conditions include the ongoing war in Ukraine, conflict in the Middle East, interest rate volatility, global and regional supply chain disruptions, and the potential imposition of new tariffs. Additional pressures such as OPEC+’s decision to increase production beginning in November 2025, concerns over a potential economic slowdown or recession, and instability in the financial sector have contributed to recent pricing volatility and are expected to continue influencing markets beyond 2025.
At the local level, the Company remains dependent on the reliability and performance of infrastructure required to gather, process, and transport its crude oil, natural gas and NGLs.
Pursuant to the terms of its ABS II Notes, the Company is required to employ a hedging strategy in which we, at all times, maintain 24 months of commodity hedges in an amount not less than 85% of the projected production of oil, natural gas and NGLs, limiting downside risk from material change in commodity prices. Even so, the remainder of the Company’s unhedged production exposed to commodity price volatility would negatively impact the Company’s results of operations if commodity prices were to decline materially from current levels.
PIH’s price hedging strategy and future hedging transactions will be determined at management’s discretion, subject to terms of certain agreements governing the Company’s indebtedness. The prices at which the Company hedges future production will depend on prevailing commodity prices at the time such transactions are executed, which may be significantly higher or lower than current levels. Accordingly, while the hedging strategy provides downside protection against commodity price volatility, it may also limit upside during periods of rising prices.
Prices for various quantities of oil, natural gas and NGLs that are produced significantly impact revenues and cash flows. The following table summarizes average commodity prices for the periods presented with Henry Hub on a per Mcf basis, and with Mont Belvieu and WTI on a per barrel of oil basis:
| Year ended December 31, | ||||||||
| 2025 | 2024 | |||||||
| Henry Hub (per Mcf) | $ | 3.43 | $ | 2.19 | ||||
| Mont Belvieu (per Boe) | $ | 26.76 | $ | 32.68 | ||||
| WTI (per Bbl) | $ | 64.87 | $ | 76.63 | ||||
Commodity Prices
WTI oil pricing
For the year ended December 31, 2025, the average WTI price was $64.87 per barrel, down 15% from the average of $76.63 per barrel for the year ended December 31, 2024. Settled derivatives reduced realized oil prices by $6.48 per barrel and $15.52 per barrel for the years ended December 31, 2025 and 2024, respectively.
93
Henry Hub natural gas pricing
The average Henry Hub natural gas price was $3.43 per Mcf for the year ended December 31, 2025, up 56% from $2.19 per Mcf for the year ended December 31, 2024. Settled derivatives reduced realized gas prices by $0.46 per Mcf and increased realized gas prices by $0.09 per Mcf for the years ended December 31, 2025 and 2024, respectively.
Mont Belvieu NGLs pricing
The average Mont Belvieu NGL price was $26.76 per Boe for the year ended December 31, 2025, an 18% decrease from $32.68 per Boe for the year ended December 31, 2024. Settled derivatives reduced realized NGL prices by $4.19 per Boe and increased realized NGL prices by $1.79 per Boe for the years ended December 31, 2025 and 2024, respectively.
Results of Operations
The following tables set forth the results of operations for the years ended December 31, 2025 and 2024. Average sales prices are derived from accrued accounting data for the relevant period indicated. Due to normal production declines and the effects of acquisitions, the historical information presented below should not be interpreted as indicative of future results.
| For the Years Ended December 31, | ||||||||
| (dollar amounts in thousands, except for per unit amounts) | 2025 | 2024 | ||||||
| Net Production: | ||||||||
| Oil (MBbl) | 1,288 | 1,425 | ||||||
| Natural Gas (MMcf) | 25,845 | 27,956 | ||||||
| NGLs (MBbl) | 2,098 | 2,480 | ||||||
| Total Production (MBoe) | 7,694 | 8,565 | ||||||
| Average daily production (MBoe/d) | 21 | 23 | ||||||
| Average realized sales price (excluding impact of derivatives settled in cash) | ||||||||
| Oil (per Bbl) | $ | 63.37 | $ | 74.96 | ||||
| Natural gas (per Mcf) | 1.95 | 0.95 | ||||||
| NGLs (per Bbl) | 21.86 | 22.74 | ||||||
| Total (per Boe) | $ | 23.11 | $ | 22.15 | ||||
| Average realized sales price (including impact of derivatives settled in cash) | ||||||||
| Oil (per Bbl) | $ | 56.89 | $ | 59.44 | ||||
| Natural gas (per Mcf) | 1.49 | 1.04 | ||||||
| NGLs (per Bbl) | 17.67 | 24.53 | ||||||
| Total (per Boe) | $ | 19.36 | $ | 20.40 | ||||
| Sales Revenue | ||||||||
| Oil sales | $ | 81,640 | $ | 106,854 | ||||
| Natural gas sales | 50,309 | 26,478 | ||||||
| NGLs sales | 45,864 | 56,410 | ||||||
| Total oil, natural gas and NGLs sales | 177,813 | 189,742 | ||||||
| Field services revenue | 1,243 | 2,474 | ||||||
| Total revenue | $ | 179,056 | $ | 192,216 | ||||
| Gain (loss) on settled derivatives | ||||||||
| Oil derivatives settled | $ | (8,348 | ) | $ | (22,131 | ) | ||
| Natural gas derivatives settled | (11,709 | ) | 2,690 | |||||
| NGLs derivatives settled | (8,783 | ) | 4,428 | |||||
| Net gain (loss) on commodity derivative settlements | $ | (28,840 | ) | $ | (15,013 | ) | ||
94
| For the Years Ended December 31, | ||||||||
| (dollar amounts in thousands, except for per unit amounts) | 2025 | 2024 | ||||||
| Costs and Expenses (per Boe) | ||||||||
| Lease operating expenses | $ | 9.49 | $ | 8.25 | ||||
| Production taxes(1) | $ | 1.27 | $ | 1.21 | ||||
| Ad valorem taxes | $ | 0.71 | $ | 0.61 | ||||
| Depletion, oil and natural gas properties | $ | 3.69 | $ | 3.99 | ||||
| Depreciation and amortization, other property and equipment | $ | 0.43 | $ | 0.35 | ||||
| Accretion of asset retirement obligation | $ | 0.54 | $ | 0.44 | ||||
| General and administrative(2) | $ | 3.69 | $ | 0.93 | ||||
| (1) | $/Boe is not a useful metric for evaluating taxes. |
| (2) | Includes distributions to Class B unitholders in 2025 following the sale of certain undeveloped properties. |
Sources of Our Revenue
Our revenues are primarily generated from the sale of oil, natural gas and NGLs produced from our operated and non-operated wells. Oil is sold at the wellhead under index-based contracts, while natural gas is delivered to third-party midstream processors, who gather, process, and market the product; our reported revenues are net of related gathering, processing, and transportation costs. NGLs are extracted during processing and marketed separately, with net proceeds remitted to us.
We also provide field services, including compression, construction and reclamation activities, and emissions-related services. While not material relative to upstream sales, these activities contribute incremental revenues and leverage our operating scale.
In addition, we use commodity derivative contracts to reduce exposure to volatility in oil, natural gas, and NGLs prices. The fair value of these instruments can result in realized and unrealized gains or losses that meaningfully affect reported revenues and cash flows.
Oil, Natural Gas and NGLs Sales
Total oil, natural gas and NGL revenues for the year ended December 31, 2025 were $177.8 million, a 6% decline from $189.7 million for the year ended December 31, 2024. The decline was primarily attributable to lower production volumes across all commodities and a 15% decrease in realized oil prices, partially offset by a 106% increase in realized natural gas prices. Oil, natural gas and NGL production decreased 9%, 7% and 15%, respectively, due to normal production decline, midstream outages, and elevated line pressure.
Derivative Financial Instruments
The Company recorded the following gain (loss) on derivative financial instruments in the Consolidated Statement of Operations for the periods presented:
| For the years ended December 31, | ||||||||
| 2025 | 2024 | |||||||
| (in thousands) | ||||||||
| Realized net loss on commodity derivatives(1) | $ | (28,840 | ) | $ | (15,013 | ) | ||
| Unrealized net gain on commodity derivatives (2) | 76,001 | 2,549 | ||||||
| Total commodity derivative gain (loss) | $ | 47,161 | $ | (12,465 | ) | |||
| (1) | Represents the cash settlement of hedges that settled during the period. |
| (2) | Represents the change in fair value of commodity derivatives net of removing the carrying value of hedges that settled during the period. |
For the year ended December 31, 2025, the total net gain on commodity derivatives was $47.2 million, as compared to a net loss of $12.5 million for the year ended December 31, 2024. This included unrealized gains on unsettled contracts of $76.0 million for the year ended December 31, 2025, as compared to a net gain of $2.5 million for the year ended December 31, 2024. This gain was partially offset by realized cash settlement losses of $28.8 million for the year ended December 31, 2025, as compared to $15.0 million for the year ended December 31, 2024.
95
These gains and losses are consistent with the Company’s risk management strategy. With scheduled debt principal payments central to the capital plan, the Company maintains hedge coverage levels designed to protect downside risk — even if that means forgoing upside during periods of rising prices.
Principal Components of Our Cost Structure
Our cost structure includes several categories that impact operating results in different ways. Lease operating expenses represent the direct costs of producing oil and natural gas, including labor, utilities, chemicals, and equipment maintenance. These expenses tend to fluctuate with production levels but also reflect the impact of fixed field costs that do not vary with volumes. We also incur production and ad valorem taxes, which are levied by state and local governments as a percentage of commodity revenues and assessed property values. These taxes generally move in line with product revenues.
Depreciation, depletion, and accretion are non-cash charges that reflect the consumption of our proved reserves, the depreciation of other property and equipment, and the passage of time on asset retirement obligations. General and administrative expenses consist of corporate overhead, employee compensation, and professional services that support the business and are largely fixed in nature. In addition, we incur costs directly associated with our field services revenues, including labor, maintenance, and other expenses necessary to support compression, reclamation, and emissions-related activities.
Some of these costs vary with commodity prices, some trend with production activity and type, and others primarily reflect fixed or discretionary expenditures.
Lease Operating Expenses
Lease operating expenses (“LOE”) were $73.0 million for the year ended December 31, 2025, as compared to $70.7 million for 2024. On a per Boe basis, LOE per Boe increased 15% to $9.49 per Boe for the year ended December 31, 2025, from $8.25 per Boe for 2024. The increase in LOE per Boe in 2025 is primarily due to lower production volumes over which fixed costs can be spread, and increased workover expense resulting from increased maintenance and optimization projects undertaken during 2025.
Production Taxes
Production and other taxes are paid on produced oil and natural gas based on rates established by federal, state, or local taxing authorities. In general, production and other taxes paid correlate to changes in oil, natural gas and NGL revenues. Production taxes are based on the sales value of production at the wellheads. For the year ended December 31, 2025, production taxes declined to $9.8 million ($1.27 per Boe) from $10.3 million ($1.21 per Boe) for 2024, primarily due to lower revenues.
Ad Valorem Taxes
PIH’s properties in Oklahoma, Texas and Kansas are also subject to ad valorem taxes in the counties where the production is located. Ad valorem taxes are based on the fair market value of mineral interests for producing wells.
For the year ended December 31, 2025, ad valorem taxes increased to $5.5 million ($0.71 per Boe) from $5.2 million ($0.61 per Boe) for 2024. The increase was primarily attributable to changes in assessed property valuations and local ad valorem tax rates.
Depreciation, Depletion and Amortization
Depreciation, depletion and amortization (“DD&A”) for the year ended December 31, 2025 was $31.7 million, or $4.12 per Boe, compared to $37.2 million, or $4.34 per Boe, for 2024. DD&A per Boe decreased due to a lower depletion rate, primarily due to net upward revisions from higher SEC gas prices.
96
General and Administrative
General and administrative (“G&A”) expense for the year ended December 31, 2025 was $28.4 million, as compared to $8.0 million for 2024. The increase was primarily due to a $15.0 million Class B unit compensation payout triggered by distribution hurdles achieved during the period, as well as increased acquisition and transaction costs. There was no Class B unit compensation payout for 2024.
Interest Expense
Interest expense for the year ended December 31, 2025 was $24.5 million, as compared to $27.2 million for 2024. The decrease reflects lower average debt outstanding during 2025 as a result of principal repayments made on the Company’s ABS facility throughout the year.
Non-GAAP Financial Measures
Adjusted EBITDA
We present the supplemental non-GAAP financial performance measure Adjusted EBITDA and provide our calculation of Adjusted EBITDA and a reconciliation of Adjusted EBITDA to net income, our most directly comparable financial measure calculated and presented in accordance with GAAP. We define Adjusted EBITDA as net income before (1) interest expense, net, (2) depreciation, depletion, amortization and accretion, (3) unrealized loss (gain) on derivative instruments, (4) non-recurring compensation expense related to our Class B Units, (5) (gain) loss on sale of assets, net, and (6) certain other non-cash or non-recurring charges, as detailed in the reconciliation table below.
Adjusted EBITDA is used as a supplemental financial performance measure by PIH management and by external users of our financial statements, such as industry analysts, investors, lenders, rating agencies and others, to evaluate our operating performance and PIH’s results of operation from period to period and against our peers without regard to financing methods, capital structure or historical cost basis. We exclude the items listed above from net income in arriving at Adjusted EBITDA because these items and related amounts can vary substantially from company to company within our industry depending upon accounting methods and book values of assets, capital structures and the method by which the assets were acquired. Adjusted EBITDA is not a measurement of our financial performance under GAAP and should not be considered as an alternative to, or more meaningful than, net income as determined in accordance with GAAP or as indicators of our operating performance. Certain items excluded from Adjusted EBITDA are significant components in understanding and assessing a company’s financial performance, such as a company’s cost of capital and tax burden, as well as the historic costs of depreciable assets, none of which are reflected in Adjusted EBITDA. Our presentation of Adjusted EBITDA should not be construed as an inference that our results will be unaffected by unusual items. Our computations of Adjusted EBITDA may not be identical to other similarly titled measures of other companies.
Adjusted Unhedged EBITDA
We also present Adjusted Unhedged EBITDA, which we define as Adjusted EBITDA further adjusted to remove realized gains and losses on derivative instruments. This measure is intended to show our operating results without the impact of our hedging program. Adjusted Unhedged EBITDA is a supplemental non-GAAP measure and may not be comparable to similarly titled measures of other companies.
97
Reconciliations of GAAP Financial Measures to Adjusted EBITDA
The following table presents our reconciliation of the GAAP financial measure of net income to the non-GAAP financial measure Adjusted EBITDA, as applicable, for each of the periods indicated.
| Year ended December 31, | ||||||||
| 2025 | 2024 | |||||||
| (in thousands) | ||||||||
| Net Income (GAAP) | $ | 55,875 | $ | 100,898 | ||||
| Depletion of oil and natural gas properties | 28,418 | 34,153 | ||||||
| Depreciation of other property and equipment | 3,279 | 3,032 | ||||||
| Accretion of asset retirement obligation | 4,134 | 3,765 | ||||||
| Gain from sale of assets | (8,455 | ) | (85,573 | ) | ||||
| Loss on ARO liabilities | 813 | 939 | ||||||
| Loss on loan extinguishment | — | — | ||||||
| Unrealized gain from derivative transactions | (76,001 | ) | (2,549 | ) | ||||
| Acquisition and transaction costs | 4,156 | 2,985 | ||||||
| Interest expense | 24,491 | 27,153 | ||||||
| Non-recurring compensation expense(1) | 15,000 | — | ||||||
| Income tax expense | 992 | 233 | ||||||
| Credit loss expense | 1,433 | — | ||||||
| Adjusted EBITDA | 54,135 | 85,036 | ||||||
| Realized (gain) loss from derivative transactions | 28,840 | 15,013 | ||||||
| Adjusted Unhedged EBITDA | $ | 82,975 | $ | 100,049 | ||||
| (1) | Includes distributions to Class B unitholders in 2025 following the sale of certain undeveloped properties. |
98
Reconciliation of PV-10 to Standardized Measure
Certain of our oil and natural gas reserve disclosures included in this prospectus are presented on a PV-10 basis. PV-10 is a non-GAAP financial measure and represents the estimated present value of the future cash flows less future development and production costs from our proved reserves before income taxes discounted using a 10% discount rate. PV-10 of proved reserves generally differs from the standardized measure of discounted future net cash flows from production of proved oil and natural gas reserves because it does not include the effects of future income taxes, as is required in computing the standardized measure. However, our PV-10 for proved reserves using SEC pricing and the standardized measure of proved reserves are substantially equivalent because we were not subject to entity level taxation. Accordingly, no provision for federal or state income taxes has been provided in the standardized measure because taxable income is passed through to our unitholders.
We believe that the presentation of a pre-tax PV-10 value provides relevant and useful information because it is widely used by investors and analysts as a basis for comparing the relative size and value of our proved reserves to other oil and natural gas companies. Because many factors that are unique to each individual company may impact the amount and timing of future income taxes, the use of PV-10 value provides greater comparability when evaluating oil and natural gas companies. The PV-10 value is not a measure of financial or operating performance under GAAP, nor is it intended to represent the current market value of proved oil and gas reserves. However, the definition of PV-10 value as defined above may differ significantly from the definitions used by other companies to compute similar measures. As a result, the PV-10 value as defined may not be comparable to similar measures provided by other companies.
Investors should be cautioned that neither PV-10 nor standardized measure of proved reserves represents an estimate of the fair market value of our proved reserves. We and others in the industry use PV-10 as a measure to compare the relative size and value of estimated reserves held by companies without regard to the specific tax characteristics of such entities.
Liquidity and Capital Resources
Overview
PIH’s primary sources of liquidity are cash generated from operations and borrowings under its asset-backed securitizations (ABS) and credit facilities. These long-term, fixed-rate, fully amortizing ABS structures are secured by certain oil and natural gas assets providing stable borrowing costs and gradual leverage reduction over time through scheduled principal payments. Restricted cash, held in accounts established under the ABS debt agreements, is reserved primarily for scheduled interest and principal payments and not available for general corporate purposes. Credit facilities are used to supplement liquidity, subject to customary conditions, and primarily address the Company’s short-term working capital needs.
99
Debt Facilities and Covenant Compliance
As of December 31, 2025, outstanding borrowings under the ABS II Notes totaled $266.9 million, and $2.3 million was outstanding under the Trail Dust advancing term loan. Additionally, $3.5 million was drawn on the WAB RBL which was established during the third quarter of 2025. As of December 31, 2025, we were in compliance with all covenants under the ABS II Notes, the Trail Dust Loan and the WAB RBL, and we expect to remain in compliance for at least the next twelve months.
Future Liquidity Outlook
We expect our liquidity sources will be sufficient to meet operating and financing needs, including scheduled debt service, anticipated capital expenditures, and working capital requirements, for at least the next twelve months. Future liquidity will depend on commodity price realizations, production volumes, and hedge settlements. Sustained changes in commodity prices or operating costs may influence our cash flow generation and could require adjustments to our capital allocation priorities, including the pace of reinvestment, distribution levels, or financing strategy.
Working Capital
The Company monitors working capital to ensure adequate levels for operations, with excess cash primarily allocated to equity distributions. In addition to working capital management, the Company maintains a disciplined approach to operating cost control and capital allocation, with a focus on reinvesting capital into its operations and generating returns that support strategic business initiatives.
As of December 31, 2025, PIH had cash and cash equivalents of $4.1 million in addition to $11.2 million held in restricted cash required as part of its ABS securitized debt to fund interest payments. As of December 31, 2024, PIH had cash and cash equivalents of $88.8 million and restricted cash of $13.5 million. The decrease in cash from December 31, 2024 to December 31, 2025 was primarily due to distributions to Class A and B unitholders following the sale of certain undeveloped properties.
Capital expenditures totaled $4.2 million for the year ended December 31, 2025, compared to $3.5 million for 2024. The increase was primarily driven by higher spending on operated capital workovers, partially offset by lower leasehold additions, as the prior year included the acquisition of additional working interests. PIH expects to meet its capital expenditure needs for the foreseeable future through operating cash flow and existing cash and cash equivalents.
Future capital requirements will depend on several factors, including the Company’s growth trajectory, acquisition activity, and other strategic considerations.
On July 2, 2025, the Company, through Presidio WAB LLC as borrower and Presidio Investment Holdings LLC as guarantor, entered into a Reserve Based Lending instrument with SouthState Bank (“WAB RBL”). The facility provides additional liquidity with an initial borrowing base of $7.5 million, subject to periodic redeterminations, and matures on July 2, 2028. Subsequent to year-end, the borrowing base was increased to $10.0 million through April 1, 2026, at which point it will revert to $7.5 million or be reset in connection with the next scheduled redetermination. This RBL supplements the Company’s existing sources of liquidity and further supports management’s assessment that the Company will be able to satisfy working capital requirements, debt service obligations, and planned capital investments during the look-forward period. However, the Company’s ability to satisfy working capital requirements, debt service obligations, and planned capital investments will ultimately depend on future operating performance, which is subject to prevailing economic conditions in the oil and natural gas industry and other factors beyond management’s control.
Although we cannot provide any assurance that cash flows from operations or other sources of needed capital will be available to us at acceptable terms, or at all, and noting that our ability to access capital markets at economic terms in the future will be affected by general economic conditions, the domestic and global oil and financial markets, our operational and financial performance, prevailing commodity prices and other macroeconomic factors outside of our control, we believe that based on our current expectations and projections, we have sufficient liquidity to fund future operations and to meet obligations as they become due for at least the next twelve months and for the foreseeable future.
100
Cash Flows
Our Cash Flows for the Years Ended December 31, 2025 and December 31, 2024:
| Year Ended December 31, | ||||||||
| 2025 | 2024 | |||||||
| (in thousands) | ||||||||
| Net cash provided by operating activities | $ | 13,100 | $ | 53,573 | ||||
| Net cash provided by investing activities | 1,518 | 80,438 | ||||||
| Net cash used in financing activities | (101,564 | ) | (54,552 | ) | ||||
| Net change in cash, cash equivalents, and restricted cash | $ | (86,946 | ) | $ | 79,459 | |||
Operating activities
Net cash provided by operating activities for the year ended December 31, 2025, decreased $40.5 million as compared to 2024, primarily driven by a $45.0 million decline in net income. Non-cash adjustments were relatively flat year over year, as a $73.5 million increase in unrealized derivative gains was largely offset by a $77.1 million reduction in gains on asset sales.
Investing activities
Net cash provided by investing activities decreased by $78.9 million for the year ended December 31, 2025, as compared to 2024. This is primarily due to proceeds received from asset divestitures totaling $8.5 million for 2025 compared to proceeds received from asset divestitures of $87.0 million for 2024.
Financing activities
Net cash used in financing activities increased by $47.0 million for the year ended December 31, 2025, as compared to 2024, primarily as a result of $60.0 million paid in member distributions in the first quarter of 2025. The distribution was partially offset by reduced ABS principal repayments.
Known Contractual and Other Obligations
Contractual Obligations and Contingent Liabilities and Commitments
The Company has various contractual obligations arising in the normal course of operations and financing activities. These include commitments under the ABS II Notes, which require periodic principal and interest payments (see Note G to the Audited Consolidated Financial Statements of Presidio Investment Holdings LLC). PIH also has contractual obligations that may result in payments upon settlement of commodity derivative contracts (see Note D to the Audited Consolidated Financial Statements of Presidio Investment Holdings LLC). Additionally, the Company maintains both short-term and long-term lease obligations, primarily related to vehicle leases and office facilities (see Note I to the Audited Consolidated Financial Statements of Presidio Investment Holdings LLC).
The Company’s other liabilities represent current and noncurrent other liabilities that are primarily comprised of environmental contingencies, asset retirement obligations and other obligations for which neither the ultimate settlement amounts nor their timings can be precisely determined in advance. See Note C and Note J of Notes to the Audited Consolidated Financial Statements of Presidio Investment Holdings LLC.
101
Off-Balance Sheet Arrangements
The Company does not have any off-balance sheet arrangements.
Critical Accounting Estimates
The Company’s most significant accounting estimates are interconnected and primarily relate to its oil and natural gas properties. Central to these estimates are proved reserve quantities, which are inherently uncertain and require significant judgment regarding future commodity prices, operating and development costs, and recovery factors. These reserve estimates directly affect the application of the successful efforts method of accounting, as they drive the calculation of depletion under the unit-of-production method, and they also influence impairment assessments, since downward revisions or adverse pricing may reduce expected cash flows below carrying values. Accordingly, fluctuations in commodity prices or reserve estimates can have a material impact on depletion expense, potential impairment charges, and ultimately the Company’s reported financial results. These estimates are described in more detail in the following sections.
Successful Efforts Method of Accounting for Oil and Natural Gas Properties
The Company utilizes the successful efforts method of accounting for its oil and natural gas properties. Under this method, costs of acquiring properties, drilling successful exploration wells, development costs, and workover costs result in additions to proved properties that are capitalized. The costs of exploratory wells are initially capitalized pending a determination of whether proved reserves have been found. At the completion of drilling activities, the costs of exploratory wells remain capitalized if the determination is made that proved reserves have been found. If no proved reserves have been found, the costs of each of the related exploratory wells are charged to expense. In some cases, a determination of proved reserves cannot be made at the completion of drilling, requiring additional testing and evaluation of the wells. The costs of such exploratory wells are expensed if a determination of proved reserves has not been made within a twelve-month period after drilling is complete. Exploration costs such as geological, geophysical and seismic costs are expensed as incurred.
The capitalized costs of proved properties are depleted using the unit-of-production method based on proved developed or total proved reserves as applicable. Costs of significant non-producing properties, wells in the process of being drilled and prepaid development costs are excluded from depletion until proved reserves are established or, if unsuccessful, impairment is determined.
Producing property is considered impaired when the carrying cost of property exceeds its net future cash flow. When a property is impaired, the carrying value is reduced to the future net cash flow and an impairment charge of the difference between cost and future net cash flow is recorded. Non-producing properties are considered impaired when the Company considers it likely that the associated leasehold will expire without plans to renew or extend the lease.
Applying the unit-of-production method for depletion and assessing the recoverability of our oil and natural gas properties for impairments requires the use of estimates as it relates to oil and natural gas reserves, as described more fully below.
Proved Reserve Estimates
Estimates of the Company’s proved reserves included in this prospectus are prepared in accordance with GAAP and SEC guidelines. The accuracy of a proved reserve estimate is a function of:
| ● | the quality and quantity of available data; |
| ● | the interpretation of that data; |
| ● | the accuracy of various mandated economic assumptions; and |
| ● | the judgment of the persons preparing the estimate. |
102
The Company’s proved reserve information as of December 31, 2025 and 2024, was prepared by independent petroleum engineers. Because these estimates depend on many assumptions, all of which may substantially differ from future actual results, proved reserve estimates will be different from the quantities of oil and gas that are ultimately recovered. In addition, results of drilling, testing and production after the date of an estimate may justify, positively or negatively, material revisions to the estimate of proved reserves.
It should not be assumed that the standardized measure as of December 31, 2025 and 2024, is the current market value of the Company’s estimated proved reserves. In accordance with SEC requirements, the Company based the standardized measure on a twelve-month average of commodity prices on the first day of each month in each respective year and prevailing costs on the date of the estimate. Actual future prices and costs may be materially higher or lower than the prices and costs utilized in the estimate. See Note N of Notes to the Audited Consolidated Financial Statements of Presidio Investment Holdings LLC for additional information.
The Company’s estimates of proved reserves impact depletion expense. If the estimates of proved reserves decline, the rate at which the Company records depletion expense will increase, reducing future net income. Such a decline may result from lower commodity prices, which may make it uneconomical to drill for and produce higher cost fields. In addition, a decline in proved reserve estimates may impact the outcome of the Company’s assessment of its proved properties for impairment.
Impairment of Long-Lived Assets
The carrying value of proved oil and natural gas properties, saltwater disposal wells and related facilities, and other property and equipment is periodically evaluated for impairment whenever events or changes in circumstances indicate that the carrying amount of an asset may not be recoverable. When it is determined that the estimated future net cash flows of an asset will not be sufficient to recover its carrying amount, an impairment loss must be recorded to reduce the carrying amount to its estimated fair value. All of the oil and natural gas properties owned by the Company are geographically oriented in a single basin; therefore, the Company evaluates impairment of oil and natural gas properties on an aggregated basis. No impairment was recorded during the years ended December 31, 2025 or 2024. See Note B of Notes to the Audited Consolidated Financial Statements of Presidio Investment Holdings LLC for additional information.
New Accounting Pronouncements
The effects of new accounting pronouncements are discussed in Note B of Notes to the Audited Consolidated Financial Statements of Presidio Investment Holdings LLC.
Quantitative and Qualitative Disclosures about Market Risk
The Company is exposed to various financial risks, including market risk, credit risk, liquidity risk, capital risk, and collateral risk. To manage these risks, the Company continuously monitors the unpredictability of financial markets and seeks to minimize potential adverse effects on its financial performance.
The Company’s principal financial liabilities consist of borrowings, leases, and trade and other payables, which are primarily used to finance and provide financial guarantees for its operations. The Company’s principal financial assets include cash and cash equivalents, as well as trade and other receivables derived from its operations.
Additionally, the Company also enters into derivative financial instruments, which are recorded as assets or liabilities depending on market dynamics. The Company leverages its internal resources to design and manage its derivative-related risk management activities, but also engages with third party providers to assist with the execution of derivative transactions and provide commodity trading and risk management applications.
Market Risk
Market risk refers to the possibility that the fair value of future cash flows of a financial instrument will fluctuate due to changes in market prices. Market risk is comprised of two main types of risk: interest rate risk and commodity price risk. Financial instruments affected by market risk include borrowings and derivative financial instruments.
103
To manage market price risks resulting from changes in commodity prices and foreign exchange rates, the Company uses both derivative and non-derivative financial instruments. These instruments help mitigate the potential negative effects on the Company’s assets, liabilities, or future expected cash flows.
Interest Rate Risk
The Company is subject to market risk exposure related to changes in interest rates. The Company’s borrowings primarily consist of fixed-rate amortizing notes and variable-rate credit facilities, as illustrated below.
| Successor | Predecessor | |||||||||||||||
| March 31, 2026 | December 31, 2025 | |||||||||||||||
| Borrowings | Interest Rate(1) | Borrowings | Interest Rate(1) | |||||||||||||
| ABS II Notes | $ | 256,787 | 7.8% – 8.4 | % | $ | 266,892 | 7.8% – 8.4 | % | ||||||||
| WAB RBL | $ | — | — | $ | 3,500 | 7.3 | % | |||||||||
| Citizens RBL | $ | 37,000 | 7.3% – 9.3 | % | — | — | ||||||||||
| Trail Dust Loan | $ | 2,114 | 7.3 | % | $ | 2,266 | 7.3 | % | ||||||||
| (1) | The interest rate on the ABS II Notes and other notes payable represents the weighted average fixed rate of the notes, while the interest rates presented for the Trail Dust Loan, WAB RBL and Citizens RBL represent the floating rate as of March 31, 2026 and December 31, 2025, respectively. |
The ABS II Notes are fixed-rate instruments and therefore not exposed to market interest rate fluctuations, whereas the Trail Dust Loan, WAB RBL and Citizens RBL credit facilities bear interest at floating rates. A hypothetical 100 basis point change in interest rates to the credit facilities would result in an annual change to interest expense as illustrated below:
| Successor | Predecessor | |||||||
| March 31, 2026 | December 31, 2025 | |||||||
| +100 Basis Points | $ | 391 | $ | 58 | ||||
| -100 Basis Points | $ | (391 | ) | $ | (58 | ) | ||
The Company strives to maintain a prudent balance of floating and fixed-rate borrowing exposure, particularly during uncertain market conditions. As part of its risk mitigation strategy, the Company may enter into swap arrangements to adjust its exposure to floating or fixed interest rates, depending on changes in the composition of borrowings in its portfolio. Consequently, the total principal hedged through the use of derivative financial instruments may vary from period to period. For additional information regarding the ABS II Notes, WAB RBL, Citizens RBL and Trail Dust Loan, refer to Note G — Long-Term Debt.
Commodity Price Risk
The Company’s revenues are primarily derived from the sale of oil, natural gas and NGLs, which exposes the Company to commodity price risk. Prices for these commodities can be volatile and may fluctuate due to changes in supply and demand, weather conditions, economic conditions, and government actions. Prolonged changes in commodity prices could materially affect our revenues, cash flows and the value of our reserves.
To mitigate the risk of fluctuations in commodity prices, the Company enters into derivative financial instruments, primarily fixed-price swaps. Under the terms of our ABS debt agreements, we are required to hedge a significant portion of our forecasted production volumes, including at least 85% of oil production for five years, 85% of natural gas production for eight years, and 85% of NGLs production for four. The new Citizens Bank credit facility (see Note 7) also includes certain hedging requirements in which we, at all times, maintain 36 months of commodity hedges in an amount not less than 75% of the projected production of oil, natural gas and NGLs. These hedges reduce, but do not eliminate, exposure to commodity price volatility and may also limit the benefits we receive from price increases.
104
By removing price volatility from a substantial portion of our expected production through 2032, we have mitigated, but not eliminated, the potential effects of changing prices on our operating cash flows. For additional information regarding derivative financial instruments, refer to Note D — Derivative Activities.
Credit and Counterparty Risk
The Company is exposed to credit and counterparty risk from the sale of its oil, natural gas and NGLs production. Accounts receivable, oil and natural gas represent amounts due from purchasers of these commodities, and their collectability depends on the financial condition of each customer. The Company evaluates the financial condition of customers before extending credit and generally does not require collateral. As of March 31, 2026 and December 31,2025, four customers each accounted for more than 10% of the Company’s commodity revenues, and a similar concentration existed in receivable balances at period-end. No other customer accounted for more than 10% of total accounts receivable, oil and natural gas in either period.
The Company is also exposed to credit risk from joint interest owners, which are entities that own a working interest in the properties operated by the Company. Accounts receivable, joint interest owners are classified within current assets in the condensed consolidated balance sheets. The Company has the ability to withhold future revenue distributions to recover amounts due.
The Company believes these receivable balances are collectible. For additional information, refer to Note B — Summary of Significant Accounting Policies.
Collateral Risk
As of March 31, 2026 and December 31, 2025, the Company has pledged substantially all of its upstream oil and natural gas properties, along with certain midstream assets, to secure borrowings under its debt instruments. The fair value of the collateral is based on reserve estimates prepared by an independent petroleum engineering firm, which utilize estimated future cash flows discounted at 10% and commodity futures pricing. These pledged assets secure repayment obligations under the Company’s ABS II Notes, WAB RBL, Citizens RBL and Trail Dust Loan.
For additional information regarding acquisitions and borrowings, refer to Note G — Long-Term Debt.
105
PRESIDIO’S EXECUTIVE OFFICER AND DIRECTOR COMPENSATION
Throughout this section, unless otherwise noted, “we,” “us,” “our,” the “Company,” “our board of directors,” “Presidio” and similar terms refer to Presidio Investment Holdings LLC before the Business Combination and Presidio Production Company after the Business Combination.
Overview
This section provides an overview of our executive compensation programs for the executive officers who are named in the “Summary Compensation Table” below, including a narrative description of the material factors necessary to understand the information disclosed therein.
This discussion may contain forward-looking statements that are based on our current plans, considerations, expectations and determinations regarding future compensation programs. Compensation programs that Presidio adopts in the future could vary significantly from the Company’s historical practices and currently planned programs summarized in this discussion.
We have opted to comply with the executive compensation disclosure rules applicable to “emerging growth companies” as defined in Section 2(a) of the Securities Act, as modified by the JOBS Act. As an “emerging growth company” as defined in the JOBS Act, we are not required to include a Compensation Discussion and Analysis section and have elected to comply with the scaled disclosure requirements applicable to emerging growth companies.
Such scaled disclosure obligations, in the context of an S-1 registration statement, limit compensation disclosure (among other things) for our principal executive officer(s) and two most highly compensated executive officers (other than the principal executive officer(s)) whose total compensation for 2025 exceeded $100,000, who were serving as executive officers as of December 31, 2025 and who continued with Presidio after the Closing. We refer to these individuals as “named executive officers.” For the fiscal year ended December 31, 2025, our named executive officers and their positions were as follows:
| ● | William A. Ulrich, Co-Chief Executive Officer |
| ● | Christopher L. Hammack, Co-Chief Executive Officer |
| ● | John Brawley, Executive Vice President and Chief Financial Officer |
| ● | Brett J. Barnes, Executive Vice President and General Counsel |
We expect that Presidio’s executive compensation program will evolve to reflect its status as a newly publicly-traded company, while still supporting Presidio’s overall business and compensation objectives. In connection with the Business Combination, certain aspects of our executive compensation program have been implemented with respect to our named executive officers (among others), including, as further discussed below, the establishment of a stock-based equity compensation program and the implementation of restated employment agreements.
2024 & 2025 Summary Compensation Table
The following table sets forth information concerning the compensation of Presidio’s named executive officers for the fiscal years ended December 31, 2024 and 2025.
| Name and Principal Position | Year | Salary | Non-Equity Incentive Plan Compensation (1) | All Other Compensation (2) | Total | |||||||||||||
| William A. Ulrich | 2024 | $ | 350,000 | $ | 262,031 | $ | 76,652 | $ | 688,683 | |||||||||
| Co-CEO | 2025 | $ | 350,000 | $ | — | $ | 73,121 | $ | 423,121 | |||||||||
| Christopher L. Hammack | 2024 | $ | 350,000 | $ | 262,031 | $ | 93,053 | $ | 705,084 | |||||||||
| Co-CEO | 2025 | $ | 350,000 | $ | — | $ | 93,653 | $ | 443,653 | |||||||||
| John Brawley(3) | 2025 | $ | 173,077 | $ | — | $ | 12,419 | $ | 185,496 | |||||||||
| Executive VP & CFO | ||||||||||||||||||
| Brett J. Barnes(4) | 2024 | $ | 250,000 | $ | 200,000 | $ | 75,726 | $ | 525,726 | |||||||||
| Executive VP & GC | 2025 | $ | 278,846 | $ | — | $ | 58,888 | $ | 337,734 | |||||||||
| (1) | Amounts reflect annual discretionary cash performance-based bonuses earned during the years ended December 31, 2024 and 2025. For additional information regarding the discretionary bonuses, please see “— Narrative Disclosure to Summary Compensation Table — Cash Bonuses” below. |
106
| (2) | For 2024, amounts reflect (i) 401k matching contributions in the amounts of $23,000 for Messrs. Ulrich and Barnes and $20,079 for Mr. Hammack, (ii) payment of medical, vision, dental and short-term disability premiums in the amounts of $17,540, $10,994 and $17,540 for Messrs. Ulrich, Hammack and Barnes, respectively, (iii) amounts attributable for use of company vehicles of $34,912, $51,062 and $33,986 for Messrs. Ulrich, Hammack and Barnes, respectively and (iv) payment of city club dues in the amount of $9,718 for Mr. Hammack. For 2025, amounts reflect (i) 401k matching contributions in the amounts of $23,500, $21,072, $20,436 and $0 for Messrs. Ulrich, Hammack, Barnes and Brawley, respectively, (ii) payment of medical, vision, dental and short-term disability premiums in the amounts of $20,313, $12,674, $20,313 and $11,719 for Messrs. Ulrich, Hammack, Barnes and Brawley, respectively, (iii) amounts attributable for use of company vehicles of $28,109, $45,019, $16,940 and $0 for Messrs. Ulrich, Hammack, Barnes and Brawley, respectively and (iv) payment of city club dues in the amount of $13,688 for Mr. Hammack. |
| (3) | Mr. Brawley began his employment with Presidio on May 19, 2025, with an annual base salary of $300,000. |
| (4) | Mr. Barnes received a promotion on May 19, 2025, which increased his annual salary from $250,000 to $300,000. |
Narrative Disclosure to Summary Compensation Table
For the year ended December 31, 2025, the compensation program for our named executive officers consisted of base salary and incentive compensation in the form of annual bonuses, and in the case of Mr. Brawley, an equity incentive award in addition to base salary and annual bonus compensation. The Presidio Board has historically determined the compensation for our named executive officers.
Base Salaries
Base salaries are intended to provide a level of compensation sufficient to attract and retain an effective management team, when considered in combination with the other components of the executive compensation program. Base salaries are reviewed periodically by the Presidio Board, typically in connection with our annual performance review process, and adjusted from time to time to reflect the named executive officer’s responsibilities, performance and experience.
Cash Bonuses
Historically, cash bonuses have been provided on a discretionary basis to our named executive officers based on certain key performance indicators as determined by the Presidio Board. Bonus compensation is designed to hold our named executive officers accountable, reward the named executive officers based on actual business results and help create a “pay for performance” culture.
Equity Incentive Awards
While the Company maintains an equity compensation program, under which “Class B Units” (as further described below) were issued to Mr. Brawley in 2025 (the “2025 Grant”) and to Messrs. Ulrich, Hammack and Barnes in 2018 (the “2018 Grants”), our named executive officers have not received any such equity compensation awards other than the 2025 Grant and the 2018 Grants.
A Class B Unit represents an actual equity interest in the Company that, in the case of the 2018 Grants, is intended to qualify as “profits interests” for U.S. federal income tax purposes and designed to gain value only after those persons who hold Class A Units in the Company have received aggregate distributions equal to the distribution threshold. The distribution threshold for the 2018 Grants was set at $0 pursuant to the “profits interest” rules, and for the sake of consistency, a distribution threshold of $0 was implemented for the 2025 Grant. Given that a $0 distribution threshold was utilized for the 2018 Grants and 2025 Grant, we believe it is more appropriate to value the 2018 Grants reported in the “Stock Awards” column in the “Outstanding Equity Awards at 2025 Fiscal Year-End” table below. For details regarding the vesting conditions of these equity awards, see the “Outstanding Equity Awards at 2025 Fiscal Year-End” table below.
107
Outstanding Equity Awards at 2025 Fiscal Year-End
The following table presents information regarding the outstanding Class B Units held by each of the named executive officers as of December 31, 2025. None of the named executive officers held any other equity awards as of that date.
| Option Awards | Stock Awards | |||||||||||||||||||||||||||||||
| Name | Grant Date (1) | Vesting Commencement Date | Number of Securities Underlying Unexercised Options (#) Exercisable | Number of Securities Underlying Unexercised Options (#) Unexercisable | Equity Incentive Plan Awards: Number of Securities Underlying Unexercised Unearned Options (#) | Option Exercise Price ($) | Option Expiration Date | Number of Shares or Units of Stock That Have Not Vested | Market Value of Shares or Units of Stock That Have Not Vested (2) | |||||||||||||||||||||||
| William A. Ulrich | 03/29/2018 | 03/29/2018 | 50 | $ | 1,708,450 | |||||||||||||||||||||||||||
| Christopher L. Hammack | 03/29/2018 | 03/29/2018 | 50 | $ | 1,708,450 | |||||||||||||||||||||||||||
| John Brawley | 07/28/2025 | 05/19/2025 | 50 | $ | 1,708,450 | |||||||||||||||||||||||||||
| Brett J. Barnes | 03/29/2018 | 03/29/2018 | 20 | $ | 683,380 | |||||||||||||||||||||||||||
| (1) | The 2018 Grants consist of awards of (i) 250 Class B Units to each of Messrs. Ulrich and Hammack and (ii) 100 Class B Units to Mr. Barnes. The 2018 Grants vest at the rate of 20% on each of the first four anniversaries of the vesting commencement date, with the remaining unvested 20% becoming vested in the event of a change in control, subject to the named executive officer’s continued employment through such vesting date or such change in control, as applicable. The 2025 Grant consists of an award of 50 Class B Units to Mr. Brawley. The 2025 Grant vests at the rate of 20% on each of the first four anniversaries of the vesting commencement date, with the remaining unvested 20% becoming vested in the event of a change in control, subject to the named executive officer’s continued employment through such vesting date or such change in control, as applicable. Full vesting occurs in the event of a change of control. |
| (2) | As of December 31, 2024, the Company’s equity was not publicly traded and, therefore, there was no ascertainable public market value for the equity on such date. The market value reported in this table is based upon a valuation analysis of Presidio’s equity as of December 31, 2025. |
Employment Agreements
We have entered into written employment agreements setting forth the terms and conditions of employment for each of our named executive officers, as described below.
William A. Ulrich
Mr. Ulrich is party to an employment agreement with the Presidio Employer Company and Presidio that became effective at the time of the closing of the Business Combination, pursuant to which he will continue to be employed as Co-Chief Executive Officer and will serve as Chairman of the Board of Directors of the Presidio Employer Company (the “Employer Board”). Under the terms of the agreement, Mr. Ulrich’s base salary will initially be set at $550,000, which base salary will be subject to annual review by the Board of Directors of the Employer Board or a committee thereof and may be increased (but not decreased) in connection with such review. Under the terms of the agreement, Mr. Ulrich will be eligible to earn an annual bonus with a target annual bonus opportunity of 100% of his base salary, subject to upward adjustment, as determined by the Employer Board. The ability to earn this annual bonus will be based on pre-established performance goals that will be determined in the Employer Board’s discretion and in consultation with Mr. Ulrich at the beginning of each year. However, Mr. Ulrich’s annual bonus payment for the 2026 calendar year will not be less than 100% of his base salary.
In addition, pursuant to the terms of the agreement, Mr. Ulrich was provided with a grant of 515,625 Restricted Stock Units (“RSUs”) under the Incentive Plan in connection with the Closing. This grant of 515,625 RSUs will become vested in three equal installments on each of the first three anniversary dates of the grant date, pending Mr. Ulrich’s continued service until such anniversary date. Thereafter, beginning in calendar year 2027, Mr. Ulrich will be eligible to receive an annual equity award grant pursuant to the Incentive Plan with (i) a target grant date fair market value of 375% of his base salary and (ii) such other terms and conditions that are substantially similar to the terms and conditions of the annual equity awards that are issued to similarly situated executives.
108
Mr. Ulrich is eligible to receive severance benefits under his employment agreement in the event of his termination of employment under certain circumstances. In the event of Mr. Ulrich’s Qualifying Termination outside of the 24-month period immediately following a Change in Control (as defined in the Incentive Plan) (such 24-month period, the “Protection Period”), Mr. Ulrich is entitled to the following severance benefits: (i) a lump-sum cash payment in the amount equal to two times the sum of (x) his annual base salary as in effect immediately prior to his termination and (y) his average annual bonus for the three-year period immediately preceding his termination, (ii) payment of any earned and unpaid annual bonus with respect to the year preceding the year in which the termination occurred, payable at the same time annual bonuses are paid to executives of the Company in respect of such year (the “Ulrich Prior Year Bonus”), (iii) payment of his pro-rated target annual bonus with respect to the year in which the termination occurred (which pro-rated amount is based on the portion of the year that Mr. Ulrich remained employed during the year in which the termination occurred (the “Ulrich Pro Rata Bonus”)), (iv) reimbursement for amounts paid to continue the health insurance coverages for Mr. Ulrich and his dependents under COBRA over a period of 18 months, payable monthly in accordance with the Company’s standard payroll practices (the “Ulrich COBRA Benefit”), (v) all of his outstanding time-vesting equity incentive awards (if any) will vest as of the termination date and (vi) all of his outstanding performance-vesting equity incentive awards (if any) will remain outstanding following his termination and will be eligible to vest based on actual performance for the applicable performance period as if he had remained employed.
In the event of Mr. Ulrich’s Qualifying Termination during the Protection Period, Mr. Ulrich is entitled to the following severance benefits: (i) a lump-sum cash payment in the amount equal to three times the sum of (x) his annual base salary as in effect immediately prior to his termination and (y) his average annual bonus for the three-year period immediately preceding his termination, (ii) the Ulrich Prior Year Bonus, (iii) the Ulrich Pro Rata Bonus, (iv) the Ulrich COBRA Benefit, (v) all of his outstanding time-vesting equity incentive awards (if any) will vest as of the termination date and (vi) the performance conditions applicable to all of his outstanding performance-vesting equity incentive awards (if any) will be deemed achieved at the greater of target and actual level of achievement as of the date of termination.
In the event of the termination of Mr. Ulrich’s employment due to death or due to his involuntary termination as a result of his disability, Mr. Ulrich is entitled to the following severance benefits: (i) the Ulrich Prior Year Bonus, (ii) all of his outstanding time-vesting equity incentive awards (if any) will vest as of the termination date and (iii) all of his outstanding performance-vesting equity incentive awards (if any) will remain outstanding following his termination and will be eligible to vest based on actual performance for the applicable performance period as if he had remained employed.
Christopher L. Hammack
Mr. Hammack is party to an employment agreement with the Presidio Employer Company and Presidio that became effective at the time of the closing of the Business Combination, pursuant to which he will continue to be employed as Co-Chief Executive Officer and will serve as a director on the Employer Board. Under the terms of the agreement, Mr. Hammack’s base salary will initially be set at $550,000, which base salary will be subject to annual review by the Employer Board or a committee thereof and may be increased (but not decreased) in connection with such review. Under the terms of the agreement, Mr. Hammack will be eligible to earn an annual bonus with a target annual bonus opportunity of 100% of his base salary, subject to upward adjustment, as determined by the Employer Board. The ability to earn this annual bonus will be based on pre-established performance goals that will be determined in the Employer Board’s discretion and in consultation with Mr. Hammack at the beginning of each year. However, Mr. Hammack’s annual bonus payment for the 2026 calendar year will not be less than 100% of his base salary.
In addition, pursuant to the terms of the agreement, Mr. Hammack was provided with a grant of 515,625 RSUs under the Incentive Plan in connection with the Closing. This grant of 515,625 RSUs will become vested in three equal installments on each of the first three anniversary dates of the grant date, pending Mr. Hammack’s continued service until such anniversary date. Thereafter, beginning in calendar year 2027, Mr. Hammack will be eligible to receive an annual equity award grant pursuant to the Incentive Plan with (i) a target grant date fair market value of 375% of his base salary and (ii) such other terms and conditions that are substantially similar to the terms and conditions of the annual equity awards that are issued to similarly situated executives.
109
Mr. Hammack is eligible to receive severance benefits under his employment agreement in the event of his termination of employment under certain circumstances. In the event of Mr. Hammack’s Qualifying Termination outside of the Protection Period, Mr. Hammack is entitled to the following severance benefits: (i) a lump-sum cash payment in the amount equal to two times the sum of (x) his annual base salary as in effect immediately prior to his termination and (y) his average annual bonus for the three-year period immediately preceding his termination, (ii) payment of any earned and unpaid annual bonus with respect to the year preceding the year in which the termination occurred, payable at the same time annual bonuses are paid to executives of the Company in respect of such year (the “Hammack Prior Year Bonus”), (iii) payment of his pro-rated target annual bonus with respect to the year in which the termination occurred (which pro-rated amount is based on the portion of the year that Mr. Hammack remained employed during the year in which the termination occurred) (the “Hammack Pro Rata Bonus”), (iv) reimbursement for amounts paid to continue the health insurance coverages for Mr. Hammack and his dependents under COBRA over a period of 18 months, payable monthly in accordance with the Company’s standard payroll practices (the “Hammack COBRA Benefit”), (v) all of his outstanding time-vesting equity incentive awards (if any) will vest as of the termination date and (vi) all of his outstanding performance-vesting equity incentive awards (if any) will remain outstanding following his termination and will be eligible to vest based on actual performance for the applicable performance period as if he had remained employed.
In the event of Mr. Hammack’s Qualifying Termination during the Protection Period, Mr. Hammack is entitled to the following severance benefits: (i) a lump-sum cash payment in the amount equal to three times the sum of (x) his annual base salary as in effect immediately prior to his termination and (y) his average annual bonus for the three-year period immediately preceding his termination, (ii) the Hammack Prior Year Bonus, (iii) the Hammack Pro Rata Bonus, (iv) the Hammack COBRA Benefit, (v) all of his outstanding time-vesting equity incentive awards (if any) will vest as of the termination date and (vi) the performance conditions applicable to all of his outstanding performance-vesting equity incentive awards (if any) will be deemed achieved at the greater of target and actual level of achievement as of the date of termination.
In the event of the termination of Mr. Hammack’s employment due to death or due to his involuntary termination as a result of his disability, Mr. Hammack is entitled to the following severance benefits: (i) the Hammack Prior Year Bonus, (ii) all of his outstanding time-vesting equity incentive awards (if any) will vest as of the termination date and (iii) all of his outstanding performance-vesting equity incentive awards (if any) will remain outstanding following his termination and will be eligible to vest based on actual performance for the applicable performance period as if he had remained employed.
John Brawley
Mr. Brawley is party to an employment agreement with Presidio Employer Company and Presidio that became effective at the time of the closing of the Business Combination, pursuant to which he will continue to be employed as Executive Vice President and Chief Financial Officer. Under the terms of the agreement, Mr. Brawley’s base salary will be $440,000, which base salary will be subject to annual review by the Employer Board or a committee thereof and may be increased (but not decreased) in connection with such review. Under the terms of the agreement, Mr. Brawley will be eligible to earn an annual bonus with a target annual bonus opportunity of 80% of his base salary, subject to upward adjustment, as determined by the Employer Board. The ability to earn this annual bonus will be based on pre-established performance goals that will be determined in the Employer Board’s discretion and in consultation with the Chief Executive Officer(s) of the Presidio Employer Company at the beginning of each year. However, Mr. Brawley’s annual bonus payment for the 2026 calendar year will not be less than 80% of his base salary.
In addition, pursuant to the terms of the agreement, Mr. Brawley was provided with a grant of 264,000 RSUs under the Incentive Plan in connection with the Closing. This grant of 264,000 RSUs will become vested in three equal installments on each of the first three anniversary dates of the grant date, pending Mr. Brawley’s continued service until such anniversary date. Thereafter, beginning in calendar year 2027, Mr. Brawley will be eligible to receive an annual equity award grant pursuant to the Incentive Plan with (i) a target grant date fair market value of 300% of his base salary and (ii) such other terms and conditions that are substantially similar to the terms and conditions of the annual equity awards that are issued to similarly situated executives.
110
Mr. Brawley is eligible to receive severance benefits under his employment agreement in the event of his termination of employment under certain circumstances. In the event of Mr. Brawley’s Qualifying Termination outside of the Protection Period, Mr. Brawley is entitled to the following severance benefits: (i) a lump-sum cash payment in the amount equal to one times the sum of (x) his annual base salary as in effect immediately prior to his termination and (y) his average annual bonus for the three-year period immediately preceding the termination, (ii) payment of any earned and unpaid annual bonus with respect to the year preceding the year in which the termination occurred, payable at the same time annual bonuses are paid to executives of the Company in respect of such year (the “Brawley Prior Year Bonus”), (iii) payment of his pro-rated target annual bonus with respect to the year in which the termination occurred (which pro-rated amount is based on the portion of the year that Mr. Brawley remained employed during the year in which the termination occurred) (the “Brawley Pro Rata Bonus”), (iv) reimbursement for amounts paid to continue the health insurance coverages for Mr. Brawley and his dependents under COBRA over a period of 18 months, payable monthly in accordance with the Company’s standard payroll practices (the “Brawley COBRA Benefit”), (v) all of his outstanding time-vesting equity incentive awards that were scheduled to vest during the 12-month period following the termination date (if any) will vest as of the termination date and (vi) all of his outstanding performance-vesting equity incentive awards (if any) will remain outstanding following his termination and will be eligible to vest based on actual performance for the applicable performance period as if he had remained employed.
In the event of Mr. Brawley’s Qualifying Termination during the Protection Period, Mr. Brawley is entitled to the following severance benefits: (i) a lump-sum cash payment in the amount equal to two times the sum of (x) his annual base salary as in effect immediately prior to his termination and (y) his average annual bonus for the three-year period immediately preceding his termination, (ii) the Brawley Prior Year Bonus, (iii) the Brawley Pro Rata Bonus, (iv) the Brawley COBRA Benefit, (v) all of his outstanding time-vesting equity incentive awards (if any) will vest as of the termination date and (vi) the performance conditions applicable to all of his outstanding performance-vesting equity incentive awards (if any) will be deemed achieved at the greater of target and actual level of achievement as of the date of termination.
In the event of the termination of Mr. Brawley’s employment due to death or due to his involuntary termination as a result of his disability, Mr. Brawley is entitled to the following severance benefits: (i) the Brawley Prior Year Bonus, (ii) all of his outstanding time-vesting equity incentive awards (if any) will vest as of the termination date and (iii) all of his outstanding performance-vesting equity incentive awards (if any) will remain outstanding following his termination and will be eligible to vest based on actual performance for the applicable performance period as if he had remained employed.
Brett J. Barnes
Mr. Barnes is party to an employment agreement with the Presidio Employer Company and Presidio that became effective at the time of the closing of the Business Combination, pursuant to which he will continue to be employed as Executive Vice President and General Counsel. Under the terms of the agreement, Mr. Barnes’s base salary will initially be set at $400,000, which base salary will be subject to annual review by the Employer Board or a committee thereof and may be increased (but not decreased) in connection with such review. Under the terms of the agreement, Mr. Barnes will be eligible to earn an annual bonus with a target annual bonus opportunity of 80% of his base salary, subject to upward adjustment, as determined by the Employer Board. The ability to earn this annual bonus will be based on pre-established performance goals that will be determined in the Employer Board’s discretion and in consultation with the Chief Executive Officer(s) of the Presidio Employer Company at the beginning of each year. However, Mr. Barnes’ annual bonus payment for the 2026 calendar year will not be less than 80% of his base salary.
111
In addition, pursuant to the terms of the agreement, Mr. Barnes was provided with a grant of 240,000 RSUs under the Incentive Plan in connection with the Closing. This grant of 240,000 RSUs will become vested in three equal installments on each of the first three anniversary dates of the grant date, pending Mr. Barnes’ continued service until such anniversary date. Thereafter, beginning in calendar year 2027, Mr. Barnes will be eligible to receive an annual equity award grant pursuant to the Incentive Plan with (i) a target grant date fair market value of 300% of his base salary and (ii) such other terms and conditions that are substantially similar to the terms and conditions of the annual equity awards that are issued to similarly situated executives.
Mr. Barnes is eligible to receive severance benefits under his employment agreement in the event of his termination of employment under certain circumstances. In the event of Mr. Barnes’ Qualifying Termination outside of the Protection Period, Mr. Barnes is entitled to the following severance benefits: (i) a lump-sum cash payment in the amount equal to one times the sum of (x) his annual base salary as in effect immediately prior to his termination and (y) his average annual bonus for the three-year period immediately preceding his termination, (ii) payment of any earned and unpaid annual bonus with respect to the year preceding the year in which the termination occurred, payable at the same time annual bonuses are paid to executives of the Company in respect of such year (the “Barnes Prior Year Bonus”), (iii) payment of his pro-rated target annual bonus with respect to the year in which the termination occurred (which pro-rated amount is based on the portion of the year that Mr. Barnes remained employed during the year in which the termination occurred) (the “Barnes Pro Rata Bonus”), (iv) reimbursement for amounts paid to continue the health insurance coverages for Mr. Barnes and his dependents under COBRA over a period of 18 months, payable monthly in accordance with the Company’s standard payroll practices (the “Barnes COBRA Benefit”), (v) all of his outstanding time-vesting equity incentive awards that were scheduled to vest during the 12-month period following the termination date (if any) will vest as of the termination date and (vi) all of his outstanding performance-vesting equity incentive awards (if any) will remain outstanding following his termination and will be eligible to vest based on actual performance for the applicable performance period as if he had remained employed.
In the event of Mr. Barnes’ Qualifying Termination during the Protection Period, Mr. Barnes is entitled to the following severance benefits: (i) a lump-sum cash payment in the amount equal to two times the sum of (x) his annual base salary as in effect immediately prior to his termination and (y) his average annual bonus for the three-year period immediately preceding his termination, (ii) the Barnes Prior Year Bonus, (iii) the Barnes Pro Rata Bonus, (iv) the Barnes COBRA Benefit, (v) all of his outstanding time-vesting equity incentive awards (if any) will vest as of the termination date and (vi) the performance conditions applicable to all of his outstanding performance-vesting equity incentive awards (if any) will be deemed achieved at the greater of target and actual level of achievement as of the date of termination.
In the event of the termination of Mr. Barnes’ employment due to death or due to his involuntary termination as a result of his disability, Mr. Barnes is entitled to the following severance benefits: (i) the Barnes Prior Year Bonus, (ii) all of his outstanding time-vesting equity incentive awards (if any) will vest as of the termination date and (iii) all of his outstanding performance-vesting equity incentive awards (if any) will remain outstanding following his termination and will be eligible to vest based on actual performance for the applicable performance period as if he had remained employed.
Each employment agreement conditions the payment of the severance benefits associated with a Qualifying Termination on the named executive officer’s delivery and non-revocation of a release of claims in favor of the Company and various affiliated parties therewith. In addition, each employment agreement contains restrictive covenants that apply to the executive during the executive’s employment and for certain periods following such executive’s termination of employment. The executives are bound by perpetual confidentiality and non-disparagement restrictions, as well as post-employment non-competition, employee non-solicitation and customer non-solicitation restrictions. For Messrs. Ulrich and Hammack, the post-employment non-competition and non-solicitation restricted period is the 24-month period following each executive’s respective termination of employment. For Messrs. Brawley and Barnes, the restricted period is the 12-month period following each executive’s respective termination of employment.
Benefits and Perquisites
The Company’s executives, including the named executive officers, are eligible to participate in the benefit plans that are available to substantially all of our employees, including a defined contribution savings plan (our “401(k) Plan”), medical, dental and life insurance plans and short-term and long-term disability plans. With respect to our 401(k) Plan, eligible employees have the opportunity to save for retirement on a tax advantaged basis up to certain limits under the Code. We make employer contributions under the 401(k) Plan, known as safe-harbor matching contributions, equal to 100% of the first 6% of a participant’s eligible compensation, as defined, that a participant contributes to the 401(k) Plan.
Executive Compensation Policies
We maintain (i) an executive compensation program, including an equity incentive plan and employment agreements (as further described below) and (ii) related compensation policies and practices, including an insider trading policy and a compensation clawback policy, that are designed to align compensation with our business objectives and the creation of stockholder value, while enabling Presidio to attract, retain, incentivize and reward individuals who contribute to our long-term success. Decisions on the executive compensation program are made by the Presidio Compensation Committee.
112
Presidio 2026 Equity Incentive Plan
The Incentive Plan was adopted in connection with the Business Combination and became effective upon the Closing. The Incentive Plan authorizes Presidio’s Committee (for purposes of this summary, the term “Committee” will refer to either such duly appointed committee or the board of directors of Presidio) to provide incentive compensation in the form of stock options, stock appreciation rights (“SARs”), restricted stock, Restricted Stock Units (“RSUs”), other stock awards and cash awards.
General
The purpose of the Incentive Plan is to advance the interests of Presidio and its stockholders by providing an incentive program that will enable Presidio to attract, retain and motivate officers, employees, consultants and non-employee directors and to provide them with an equity interest in the performance of Presidio. These incentives are provided through the grant of stock options, SARs, restricted stock, RSUs, other stock awards and cash awards.
Authorized Shares
Subject to the adjustment provisions in the Incentive Plan, the initial maximum aggregate number of shares authorized for issuance under the Incentive Plan is equal to 4,640,654, and such shares will consist of authorized but unissued shares or treasury shares. We refer to the aggregate number of shares available for awards under the Incentive Plan as the “share reserve.” The aggregate number of shares that may be issued pursuant to awards will increase annually on January 1 of each calendar year (commencing with the first January 1 following the Closing Date and ending on and including the January 1 immediately following the ninth anniversary of the Closing Date), with such annual increase equal to 5% of the total number of shares issued and outstanding on the last day of the preceding fiscal year. The share reserve is subject to adjustment by the Committee in the event of certain changes in our corporate structure, as described below.
Share Counting
Each share made subject to an award will reduce the number of shares remaining available for grant under the Incentive Plan by one share. Shares will not be treated as having been issued under the Incentive Plan and will therefore not reduce the number of shares available for issuance to the extent such shares are (i) tendered in payment of a stock option (including, for the avoidance of doubt, shares tendered by a participant or withheld by us as payment of the exercise price of a stock option), (ii) delivered or withheld in satisfaction of tax withholding obligations, (iii) subject to an award that expires or is exchanged, surrendered, forfeited or is cancelled, or are shares not issued with respect to an award that is terminated without issuance of the full number of shares to which the award related, or (iv) subject to an award under the Incentive Plan settled in cash (in whole or in part). The payment of dividend equivalents in cash in conjunction with any outstanding award will not reduce the share reserve. No share may again be optioned, granted or awarded if such action would cause an incentive stock option to fail to qualify as an incentive stock option under Section 422 of the Code.
Adjustments for Capital Structure Changes
In the event of any change in shares of Presidio Class A Common Stock through merger, consolidation, reorganization, recapitalization, reclassification, stock dividend, extraordinary cash dividend, stock split, reverse stock split, spin-off, combination of shares, or other corporate event or transaction or other change affecting the common stock, or if Presidio makes a distribution to its stockholders in a form other than common stock (excluding regular cash dividends), the Committee will make appropriate and equitable adjustments to (i) the number and kind of shares authorized under the Incentive Plan, (ii) the number and kind of shares subject to outstanding awards, (iii) the exercise, base or purchase price or other value determinations of outstanding awards, and/or (iv) any other terms of an award that are affected by the event. Any such adjustments will, to the extent necessary to avoid additional taxes, be made in a manner consistent with the requirements of Section 409A of the Code and, in the case of incentive stock options, to the extent practicable, in a manner consistent with the requirements of Section 424(a) of the Code.
113
Nonemployee Director Award Limits
The aggregate grant date fair value (determined as of the date of grant) of all awards granted under the Incentive Plan to any non-employee director during each calendar year, taken together with any cash compensation paid to such non-employee director for service as a non-employee director during such calendar year, will not exceed $500,000. The independent members of the board of directors of Presidio may make exceptions to this limit for a non-executive chair of the board or for an initial award granted to a non-employee director following his or her appointment to the board, provided, that, the non-employee director receiving such additional compensation may not participate in the decision to award such compensation.
Administration
The Incentive Plan generally will be administered by the Committee, although the board of directors of Presidio retains the right to administer the Incentive Plan directly. The Committee may delegate to one or more of Presidio’s officers the authority to grant and determine the terms and conditions of awards granted under the Incentive Plan, subject to the requirements of Section 157(c) of the Delaware General Corporation Law (or any successor provision) and award guidelines established by the Committee. In no event will such delegation of authority be permitted with respect to awards granted to any member of the board of directors of Presidio or any eligible person who is subject to Rule 16b-3 of the Exchange Act. Subject to the provisions of the Incentive Plan, the Committee has the power and discretion necessary or appropriate to administer the Incentive Plan, with such powers including, but not limited to, the power to (i) determine the eligible persons to whom awards are granted, (ii) prescribe the restrictions, terms, and conditions of all awards, (iii) interpret the Incentive Plan and the terms of the awards, (iv) adopt rules for the administration, interpretation and application of the Incentive Plan as are consistent therewith, and interpret, amend or revoke any such rules, (v) make determinations regarding a participant’s termination of employment or service for purposes of an award, (vi) correct any defect(s) or omission(s) or reconcile any ambiguity(ies) or inconsistency(ies) in the Incentive Plan or award thereunder, (vii) make all determinations it deems advisable for administration of the Incentive Plan, (viii) decide all disputes arising in connection with the Incentive Plan and to otherwise supervise the administration of the Plan, (ix) amend the terms of an award in any manner that is not inconsistent with the Incentive Plan, (x) accelerate the vesting, or to the extent applicable, the exercisability of any award at any time and (xi) adopt such procedures, modifications or subplans as are necessary or appropriate to permit participation in the Incentive Plan by eligible persons who are foreign nationals or employed outside of the United States. The Committee’s determinations under the Incentive Plan need not be uniform and may be made by the Committee selectively among participants and eligible persons, whether or not such persons are similarly situated. All interpretations and actions of the Committee will be final and binding on all persons having an interest in the Incentive Plan or any award.
All awards granted under the Incentive Plan will be evidenced by a written or digitally signed agreement between Presidio and the participant specifying the terms and conditions of the award, consistent with the requirements of the Incentive Plan.
Prohibition of Option and SAR Repricing
The Incentive Plan expressly provides that, subject to the adjustment provisions in the Incentive Plan and other than in connection with a change in control (as defined in the Incentive Plan), without the prior approval of Presidio’s stockholders, neither the Committee nor the board of directors of Presidio may take any of the following actions with respect to underwater options or SARs: (i) the cancellation of such outstanding options or SARs in exchange for cash or the grant of a new award with a lower exercise price or base price, (ii) the amendment of such outstanding options or SARs to reduce the exercise price or base price or (iii) any action with respect to a stock option or SAR that would be treated as a “repricing” under the then applicable rules, regulations or listing requirements of the stock exchange on which shares of Presidio Class A Common Stock are listed.
Eligibility
Awards may be granted to officers, employees, non-employee directors or any natural person who is a consultant or other personal service provider of Presidio or of any of its subsidiaries. In its determination of eligible participants, the Committee may consider any and all factors it considers relevant or appropriate, and designation of a participant in any year does not require the Committee to designate that person to receive an award in any other year. Incentive stock options may be granted only to employees who, as of the time of grant, are employees of Presidio or any subsidiary corporation of Presidio. Awards granted under the Incentive Plan are nontransferable except in limited circumstances. Following the Closing, Presidio is expected to have approximately 4 officers, 125 employees and 5 non-employee directors who are natural persons, who may be eligible to receive awards under the Incentive Plan.
114
Stock Options
The Committee may grant non-statutory stock options, incentive stock options within the meaning of Section 422 of the Code, or any combination of these. Unless otherwise determined by the Committee, and subject to certain limitations set forth in the Incentive Plan, the exercise price of each option may not be less than the fair market value of a share of Presidio Class A Common Stock on the date of grant, provided that an incentive stock option granted to a person who at the time of grant owns stock possessing more than 10% of the total combined voting power of all classes of stock of Presidio or any subsidiary corporation of Presidio must have an exercise price not less than 110% of the fair market value of a share of Presidio Class A Common Stock on the date of the grant.
The Incentive Plan provides that the option exercise price may be paid (i) in cash or cash equivalent acceptable to the Committee or (ii) to the extent permitted by the Committee, (A) by means of a broker-assisted cashless exercise; (B) by tender to Presidio of shares of Presidio Class A Common Stock owned by the participant having a fair market value not less than the exercise price; (C) by reducing the number of shares of Presidio Class A Common Stock otherwise deliverable upon exercise; (D) by such other consideration as approved by the Committee; or (E) by any combination of these.
The Committee will determine the requirements for vesting and exercisability of a stock option, which may be based on the continued employment or service of the participant with Presidio for a specified time period or upon the attainment of specific performance goals. A stock option may be terminated prior to the end of the term upon termination of employment or service, as determined by the Committee. The maximum term of any stock option granted under the Incentive Plan is ten years, provided that an incentive stock option granted to a person who at the time of grant owns stock possessing more than 10% of the total combined voting power of all classes of stock of Presidio or any subsidiary corporation of Presidio must have a term not exceeding five years.
Stock Appreciation Rights
The Committee may grant SARs under the Incentive Plan. A SAR may be granted on a basis that allows for the exercise of the right by the participant, or that provides for the automatic exercise or payment of the right upon a specified date or event. The base price of each SAR may not be less than the fair market value of a share of Presidio Class A Common Stock on the date of grant.
The Committee will determine the requirements for vesting and exercisability of the SARs, which may be based on the continued employment or service of the participant with Presidio for a specified time period or upon the attainment of specific performance goals. The SARs may be terminated prior to the end of the term (with a maximum term of ten years) upon termination of employment or service, as determined by the Committee.
Upon the exercise of any SAR, the participant is entitled to receive an amount equal to the excess of the fair market value of the underlying shares of Presidio Class A Common Stock as to which the right is exercised over the aggregate base price for such shares. At the Committee’s discretion, payment of this amount upon the exercise of a SAR may be made in cash, shares of Presidio Class A Common Stock, or in a combination of shares of Presidio Class A Common Stock and cash as set forth in the applicable award agreement. The maximum term of any SAR granted under the Incentive Plan is ten years.
Restricted Stock Awards
A restricted stock award is a grant of a specified number of shares of Presidio Class A Common Stock to a participant, for which restrictions will lapse upon the terms that the Committee determines at the time of grant. The Committee will determine the requirements for the lapse of the restrictions for the restricted stock awards, which may be based on the service of the participant for a specified time period or the attainment of one or more performance goals. Participants holding restricted stock awards will have the rights of a stockholder, including the right to vote the shares and to receive all dividends and other distributions with respect thereto, unless the Committee determines otherwise. A participant holding such restricted stock award will have the right to receive dividends on such restricted stock award during such restricted period; provided that the Committee may determine and set forth in a participant’s award agreement the terms of such dividends. Any shares granted under a restricted stock award are nontransferable, except in limited circumstances.
Restricted Stock Units
The Committee may grant RSUs under the Incentive Plan, which represent rights to receive, upon vesting and settlement of the RSUs, shares of Presidio Class A Common Stock or, if determined by the Committee in the award agreement, a cash payment equal to the fair market value thereof, or a combination thereof, at the discretion of the Committee. The Committee will determine the requirements for vesting and payment of the RSUs, which may be based on the service of the participant for a specified time period or the attainment of one or more performance goals. Participants have no rights as a stockholder with respect to RSUs until shares of Presidio Class A Common Stock are issued in settlement of such awards. A participant holding RSUs granted pursuant to the Incentive Plan will have the right to receive dividend equivalent rights with respect to the shares of Presidio Class A Common Stock subject to such RSUs; provided that the Committee may determine and set forth in a participant’s award agreement the terms of such dividend equivalent rights. Unless otherwise provided by the Committee, a participant will forfeit any RSUs which have not vested prior to the participant’s termination of service.
115
Performance Awards
The Committee will be authorized to grant performance-based awards that are earned subject to the achievement of set performance goals or criteria. The Committee may adjust performance goals, or the manner of measurement thereof, as it deems appropriate.
Stock Awards
The Committee may grant an award of, or an award that is valued by reference to, Presidio Class A Common Stock in such amounts and subject to such terms and conditions as the Committee determines. A stock award may be granted for past employment or service, in lieu of bonus or other cash compensation, as directors’ compensation or any other valid purpose as determined by the Committee. Such awards may be subject to vesting conditions based on continued performance of service or subject to the attainment of one or more performance goals, with the possibility that awards may be made with no vesting requirements. The Committee may, in connection with any stock award, require the payment of a specified purchase price. Upon the issuance of shares of Presidio Class A Common Stock under a stock award, the participant will have all rights of a stockholder with respect to shares of Presidio Class A Common Stock, including the right to vote and receive dividends and other distributions with respect thereto (which are subject to the same vesting terms as the stock award).
Cash Awards
The Committee may grant a cash award in such amounts and subject to such terms and conditions as the Committee determines. A cash award may be granted for past employment or service, in lieu of bonus or other cash compensation, as directors’ compensation or any other valid purpose as determined by the Committee. The terms and conditions of such cash awards will be determined by the Committee, and such awards may be granted with or without vesting requirements.
Change in Control
If there is a change in control, all outstanding awards will either be (i) continued or assumed by the surviving company or its parent (including conversion into the right to receive securities, cash or a combination of both) or (ii) substituted by the surviving company or its parent for awards (including conversion into the right to receive securities, cash or a combination of both), with substantially similar terms to the outstanding awards (with appropriate adjustments to the type of consideration payable upon settlement, and with appropriate adjustments of performance conditions or deemed achievement of such conditions (A) for any completed performance period, based on actual performance, or (B) for any partial or future performance period, at the greater of the target level or actual performance, unless otherwise provided in an award agreement or an employment agreement).
Only to the extent that outstanding awards are not continued, assumed or substituted upon the occurrence of a change in control, the Committee may, but is not obligated to, make adjustments to the terms and conditions of outstanding awards, including without limitation (i) acceleration of exercisability, vesting and/or payment immediately prior to, upon or following such event, (ii) upon written notice, providing that any outstanding stock option and SARs must be exercised during a period of time immediately prior to such event or other period (contingent upon the consummation of such event), and at the end of such period, such stock options and SARs will terminate to the extent not so exercised, and (iii) cancellation of all or any portion of outstanding awards for fair value (in the form of cash, shares, other property or any combination of such consideration), less any applicable exercise or base price in the case of stock options and SARs or similar awards, which may equal zero if applicable.
Notwithstanding the foregoing, if a participant’s employment or service is terminated upon or within 24 months following a change in control by Presidio without cause (as defined in the Incentive Plan) or upon such other circumstances set forth in the applicable award agreement, the unvested portion (if any) of all outstanding awards held by the participant will immediately vest (and, to the extent applicable, become exercisable) and be paid in full upon such termination, with any performance conditions deemed achieved (i) for any completed performance period, based on actual performance, or (ii) for any partial or future performance period, at the greater of the target level or actual performance, unless otherwise provided in an award agreement or employment agreement.
116
Substitution or Assumption of Awards in Connection with an Acquisition
The Committee may grant awards under the Incentive Plan in connection with the acquisition, whether by purchase, merger, consolidation or other corporate transaction, of the business or assets of any corporation or other entity, in substitution for awards previously granted by such corporation or other entity or otherwise. The Committee may also assume any previously granted awards of an employee, director or consultant of another corporation who becomes eligible by reason of a corporate transaction. The terms of the substituted or assumed awards may vary from the terms and conditions otherwise required by the Incentive Plan if the Committee deems it necessary. The substituted or assumed awards will not reduce the total number of shares available for awards under the Incentive Plan, to the extent permitted by applicable law and the listing requirements of the stock exchange on which shares of Presidio Class A Common Stock are listed.
Amendment, Suspension or Termination
The Incentive Plan will continue in effect until its termination by the Committee, provided that no awards may be granted under the Incentive Plan following the tenth anniversary of the Incentive Plan’s effective date, which effective date is March 4, 2026. No amendment, modification suspension or termination of the Incentive Plan may materially and adversely affect any outstanding award without the consent of the participant, provided that, the board of directors of Presidio has broad authority to amend the Incentive Plan or any award thereunder without the consent of a participant to the extent it deems necessary or desirable in its discretion to comply with any applicable law, regulation or rule, including, but not limited to, Sections 409A and 457A of the Code. Certain amendments or modifications of the Incentive Plan may also be subject to the approval of Presidio’s stockholders as required by the SEC and NYSE rules or applicable law.
Termination of Service for Cause
Under the Incentive Plan, unless an award agreement or employment agreement provides otherwise, if a participant’s employment or service is terminated for cause, or if after termination, the Committee determines that the participant engaged in an act that falls within the definition of Cause, or if after termination the participant engages in conduct that violates any continuing obligation of the participant with respect to Presidio or any of its subsidiaries, Presidio may cancel and/or forfeit any or all of that participant’s outstanding awards. In addition, if the Committee makes the determination above, Presidio may suspend the participant’s right to exercise any stock option or SAR, receive any payment or vest in any award pending a determination of whether the act falls within the definition of cause. If a participant voluntarily terminates employment or service in anticipation of an involuntary termination for cause, that will be deemed a termination for cause.
Right of Recapture
Awards granted under the Incentive Plan may be subject to recoupment in accordance with Section 954 of the Dodd-Frank Wall Street Reform and Consumer Protection Act (regarding recoupment of erroneously awarded compensation). Presidio has the right to recoup any gain realized by the participant from the exercise, vesting or payment of any award if, within one year (or such longer time specified in an award agreement or other agreement with a participant) after such exercise, vesting or payment, the Committee determines the participant is subject to recoupment pursuant to a compensation recovery, clawback or similar policy.
Director Compensation
Presidio intends to develop a director compensation program that is designed to align compensation with Presidio’s business objectives and the creation of stockholder value, while enabling Presidio to attract, retain, incentivize, and reward directors who contribute to the long-term success of Presidio. None of the directors that served on the Presidio Board received compensation during the fiscal year ended December 31, 2025 for services rendered to the Company.
117
MANAGEMENT OF PRESIDIO
The following table provides information regarding the current executive officers and members of the Presidio Board:
| Name | Age | Position(s) | ||
| William Ulrich | 42 | Chairman, Co-Chief Executive Officer and Director | ||
| Chris Hammack | 50 | Co-Chief Executive Officer and Director | ||
| John Brawley | 43 | Executive Vice President and Chief Financial Officer | ||
| Brett Barnes | 45 | Executive Vice President and General Counsel | ||
| Daniel C. Herz | 48 | Director | ||
| Jerry Schretter | 61 | Director | ||
| Jeffrey Serota | 59 | Director | ||
| Jerry Silvey | 33 | Director | ||
| Tyson Taylor | 44 | Director | ||
| James E. Vallee | 55 | Director | ||
| Ray N. Walker, Jr. | 68 | Director |
Executive Officers
William A. Ulrich serves as Chairman of the Presidio Board and Co-Chief Executive Officer. Prior to the Closing, Mr. Ulrich had served as Co-Chief Executive Officer of PIH since co-founding the company in January 2017. Mr. Ulrich has 20 years of experience within the energy and finance sectors and is focused on deploying technology to drive behavior change in the energy industry. From 2009 to 2016, Mr. Ulrich served in senior corporate development roles at Atlas Energy (NYSE: ATLS), Atlas Pipeline Partners L.P. (NYSE: APL) and Atlas Resource Partners L.P. (NYSE: ARP). From 2005 to 2009, Mr. Ulrich was an investment banker at UBS Investment Bank. Mr. Ulrich also currently serves as a trustee for the Monuments Men and Women Foundation, a 501(c)(3) not-for-profit organization created to honor and raise awareness about the service of Monuments of Men and Women of WWII. Mr. Ulrich graduated from Harvard College with an AB in Economics.
Christopher L. Hammack serves as Co-Chief Executive Officer and a member of the Presidio Board. Prior to the Closing, Mr. Hammack had served as Co-Chief Executive Officer of PIH since co-founding the company in January 2017. Mr. Hammack has over 27 years of experience in the energy industry and is passionate about driving innovation in field operations. In his role at PIH, Mr. Hammack focuses on field operations, personnel training and driving operational efficiency. Prior to co-founding PIH, from 2014 to 2017, Mr. Hammack was the Chief Executive Officer of Trinity River Energy LLC, a private exploration and production company formed in 2014 through a merger of assets held by Legend Production Holdings and KKR Natural Resources Funds. Earlier in his career, Mr. Hammack held senior roles at Atlas Resources Partners (NYSE: ARP), Range Resources Corporation (NYSE: RRC) and Stroud Energy Ltd. Mr. Hammack holds a Bachelor of Science in Petroleum Engineering from Texas A&M University.
John Brawley serves as Executive Vice President and Chief Financial Officer. Prior to the Closing, Mr. Brawley had served as Executive Vice President and Chief Financial Officer of PIH since May 2025. Since joining PIH, Mr. Brawley has been responsible for PIH’s capital markets and reporting functions. He has more than 19 years of experience in the energy and finance industries. From September 2018 to March 2025, Mr. Brawley served as Executive Vice President and Chief Financial Officer of Maverick Natural Resources, LLC, a private oil and natural gas company with a focus on assets in Texas and Oklahoma. From November 2014 to June 2018, he served in various roles at SandRidge Energy, Inc. (NYSE: SD) relating to capital markets, M&A and finance, including as Senior Vice President of Capital Markets and M&A and Treasurer. Earlier in his career, Mr. Brawley’s experience includes various roles with public and private companies, as well as private capital funds. Mr. Brawley received a Bachelor’s degree in Economics and Biological Sciences from Rice University and a Master of Business Administration from the Jesse H. Jones Graduate School of Management at Rice University.
118
Brett Barnes serves as Executive Vice President and General Counsel. Prior to the Closing, Mr. Barnes had served as Executive Vice President and General Counsel of PIH since May 2025 after serving as General Counsel and Vice President of Land from April 2018 to May 2025 and as Vice President of Land, Legal and Regulatory from February 2017 to March 2018. Over the past eight years, Mr. Barnes has been responsible for PIH’s legal and land functions as well as its risk management and mitigation strategies. Mr. Barnes has more than 19 years of experience in the energy industry ranging from large public companies to private companies. Prior to joining PIH, he served as Vice President of Land and HSE/Regulatory at Trinity River Energy LLC from 2015 to 2017, and previously held various legal and land leadership roles at Forestar Group Inc. (NYSE: FOR) and EOG Resources, Inc. (NYSE: EOG). Mr. Barnes earned his Juris Doctor from The University of Texas School of Law and his Bachelor of Business Administration in Finance from Texas A&M University. He is a member of the State Bar of Texas and serves on the boards of the Texas Alliance of Energy Producers and ADAM Energy Fort Worth.
Directors
Daniel C. Herz serves as an independent member of the Presidio Board and as the chair of the Compensation Committee and a member of the Audit Committee. Since 2021, Mr. Herz has been the Founder, President and Chief Executive Officer of WhiteHawk Energy, LLC, a mineral and royalty interests company focused on oil and natural gas assets. In his capacity as Founder and CEO, Mr. Herz is responsible for the strategic direction, growth initiatives and overall operational leadership of the company. Prior to WhiteHawk, Mr. Herz served as Founder, President and Chief Executive Officer of Falcon Minerals Corporation (NASDAQ: FLMN), a publicly traded minerals and royalties company, from August 2018 until June 2021, and served on its Board of Directors from May 2020 until June 2021. From April 2015 until October 2018, Mr. Herz served as President of Atlas Energy Group, LLC (formerly NYSE: ATLS). In addition, beginning in April 2015, Mr. Herz served as a director and Chief Executive Officer of Atlas Resource Partners, L.P., which filed a voluntary petition for reorganization under Chapter 11 of the U.S. Bankruptcy Code in August 2016. Mr. Herz led the company through a consensual reorganization and continued to serve as director and Chief Executive Officer following the company’s emergence from bankruptcy and its subsequent renaming as Titan Energy, Inc., until August 2018. He also served in executive roles in corporate development and strategy for Atlas Energy and its affiliates, including senior vice president positions with Atlas Energy, L.P. and Atlas Pipeline Partners, GP, LLC, overseeing the company’s sales to Chevron Corporation and Targa Resources Corporation, respectively. Mr. Herz began his professional career in investment banking in 1999, where he focused on energy sector corporate finance and mergers and acquisitions. We believe Mr. Herz is well qualified to serve as a director due to his extensive executive leadership experience, deep operational and financial expertise in energy and natural resources industries, and his board experience with a publicly traded company.
Jerry Schretter serves as an independent member of the Presidio Board and as the chair of the Audit Committee. Since 2024, Mr. Schretter has been a Senior Advisor at Cripps Leadership Advisors, an Energy Executive Search firm based in London and Houston. In this capacity, Mr. Schretter leverages his client network of over thirty-five years to identify executive placement opportunities globally at the board and senior executive level. From 2019 to 2024, Mr. Schretter served as a Vice Chairman and Co-Head of Americas Energy in Investment Banking at Bank of America. In this capacity, Mr. Schretter was responsible for strategic and financing advisory and managing some of the bank’s most important clients. Prior to Bank of America, Mr. Schretter worked in senior investment banking roles covering the energy sector at Citi, UBS, Deutsche Bank and Morgan Stanley. We believe Mr. Schretter is well qualified to serve as a director based on his extensive leadership and advisory experience in investment banking, his strategic insights into energy and financial markets, and his experience advising corporate management teams and boards on governance and transactional matters.
119
Jeffrey S. Serota serves as an independent member of the Presidio Board and as the chair of the Nominating and Corporate Governance Committee and a member of the Compensation Committee. Since 2016, Mr. Serota has served as Vice Chairman and Chief Investment Officer at Corbel Capital Partners, a multi-strategy investment firm with over $1 billion in assets under management. Prior to that, Mr. Serota served on various boards of public and private companies, prior to that Mr. Serota was a Senior Partner at Ares Management. Mr. Serota has more than thirty years of experience as a principal investor and operating executive, including serving as Chairman of three publicly traded companies. Mr. Serota brings to the Board substantial experience in private equity, strategic investing, and corporate governance. His background leading investment platforms, overseeing public-company strategy, and evaluating complex capital-allocation decisions strengthens the Board’s oversight of financial strategy, investment discipline, and long-term value creation. Mr. Serota has extensive experience as a public company director and chairman, including companies in the energy industry. He has served on the boards of directors of several companies that were publicly traded at the time of his service, including Great Elm Group, Inc. (NASDAQ: GEG), where he served as Chairman of the Board; Goodrich Petroleum Corporation (formerly NYSE: GDP); SandRidge Energy, Inc. (NYSE: SD), where he served as Chairman of the Board; EXCO Resources, Inc. (formerly NYSE: XCO); and CIFC Corp. (formerly NASDAQ: CIFC), where he also served as Chairman of the Board. In addition, Mr. Serota previously served on the Supervisory Board of LyondellBasell Industries N.V. (NYSE: LYB) and on the board of Douglas Dynamics, Inc (NYSE: PLOW). We believe Mr. Serota is well qualified to serve as a director based on his extensive public company board experience, prior service as chairman of publicly traded companies, and his investment, governance and operational expertise.
Jerry Silvey serves as a member of the Presidio Board. Prior to the completion of the Business Combination, Mr. Silvey served as Chief Executive Officer of EQV and served on the EQV Board. Mr. Silvey is currently the Chief Executive Officer and Chairman of the EQV Group, which he founded in 2022. Mr. Silvey is also currently Chief Executive Officer of EQV Ventures Acquisition Corp. II, an affiliate of the EQV Group, where he also serves as director. From 2016 to 2022, Mr. Silvey served as a senior investment professional in the Energy & Infrastructure group at Magnetar Capital LLC, where he was responsible for the execution and management of over $2 billion of highly structured direct investments across the energy asset spectrum. Previously, Mr. Silvey was a member of the energy global investment banking group at the Royal Bank of Canada specializing in the acquisition, divestment and restructuring of upstream oil and gas assets. Mr. Silvey holds a Bachelor of Business Administration in Energy Finance from Southern Methodist University. We believe Mr. Silvey is well qualified to serve as a director due to his experience executing and managing complex, large-scale energy investments and his investment banking and transactional experience across the energy sector.
Tyson Taylor serves as a member of the Presidio Board. Prior to the completion of the Business Combination, Mr. Taylor served as President and Chief Financial Officer of EQV and served on the EQV Board. Mr. Taylor is currently the President and a director of the EQV Group, a position he has held since 2022. Mr. Taylor is also currently President and Chief Financial Officer of EQV Ventures Acquisition Corp. II, an affiliate of the EQV Group, where he also serves as director. From 2015 to 2022, Mr. Taylor served as Counsel to Magnetar Capital LLC, where he operated as lead counsel for the Energy & Infrastructure group, managing all legal aspects of the funds, including transaction execution, fund compliance and fund management. Previously, Mr. Taylor was the General Counsel and Corporate Secretary at Star Peak Corp II, a blank check company that completed its business combination with Benson Hill, Inc. (NYSE: BHIL) in September 2021, and Secretary and General Counsel at Star Peak Energy Transition Corporation, a blank check company that completed a business combination with Stem, Inc. (NYSE: STEM) in April 2021. Mr. Taylor was an attorney with Kirkland & Ellis LLP from 2013 to 2015 and Simpson Thacher & Bartlett LLP from 2010 to 2013. He holds a Masters in Finance from the London Business School, a Juris Doctorate from the University of Pennsylvania Carey Law School and a Bachelor of Arts in Economics from Brigham Young University. We believe Mr. Taylor is well qualified to serve as a director based on his combined finance and legal expertise, his experience leading transaction execution, governance, and compliance for investment funds and public-company business combinations, and his executive roles overseeing strategy and capital markets activities.
James E. Vallee serves as an independent member of the Presidio Board and as a member of the Compensation Committee and the Nominating and Corporate Governance Committee. Since 2020, Mr. Vallee has been a founding partner and managing director of Valhil Capital and Valhil Advisors, private investment and strategic advisory firms focused on long-term principal investments in the energy, infrastructure and related sectors. He is also co-founder and Chairman of Deltawave Energy, co-founder of HoneycombQ, and publisher of Astrolight Media, through which he engages with boards and senior executives on corporate governance, capital allocation, and long-term strategic growth initiatives. Prior to founding Valhil, Mr. Vallee spent more than two decades as a partner and senior attorney at leading global law firms in Houston, including Paul Hastings, Jones Day, and Winston & Strawn. His practice focused on mergers and acquisitions, capital markets transactions, and strategic joint ventures in the energy industry. During his legal career, Mr. Vallee represented public and private companies, private equity firms, and financial institutions and regularly advised public company boards and management teams on significant energy and industrial transactions, governance matters, and conflicts oversight. We believe Mr. Vallee is well qualified to serve as a director based on his extensive experience in energy transactions and capital markets, his deep familiarity with public-company governance and conflicts matters, and his strategic perspective on the energy sector.
120
Ray N. Walker, Jr. serves as an independent member of the Presidio Board and as a member of the Audit Committee and the Nominating and Corporate Governance Committee. Mr. Walker has more than 50 years of experience in the oil and gas industry, with a background in operations, asset development, and executive leadership. Mr. Walker most recently served as Chief Operating Officer of Encino Energy, from 2018 until its acquisition by EOG Resources, Inc. in 2025, where he was responsible for overseeing the company’s operations and development activities. From 2012 to 2018, Mr. Walker served as Executive Vice President and Chief Operating Officer of Range Resources Corporation. Since August of 2025, Mr. Walker has served as a member of the Board of Directors of MPLX GP LLC (the general partner of MPLX LP, NYSE: MPLX) and is a member of the Audit Committee and the Conflicts Committee. Mr. Walker also currently serves on the Board of Directors of Solaris Energy Infrastructure, Inc. (NYSE: SEI), where he serves as Chair of the Compensation Committee. He has also previously served as an energy advisor to the Federal Reserve Bank of Cleveland. We believe Mr. Walker’s extensive operational experience in the energy industry, his executive experience overseeing operations in public and private companies, and his service on public and private company boards qualify him to serve as a director.
Composition of the Presidio Board
The business and affairs of Presidio are managed by or under the direction of the Presidio Board, which consists of 9 members. The Certificate of Incorporation provides that, subject to the rights of the holders of Preferred Stock, the number of directors on the Presidio Board shall be fixed exclusively by resolution adopted by the Presidio Board. For as long as any shares of the Series A Preferred Stock remain outstanding, the holders of record of the Series A Preferred Stock, voting as a separate class from the Presidio Common Stock, have the exclusive right to elect the Series A Preferred Director, and under certain circumstances two Preferred Stock Directors. On the Closing Date, holders of a majority of the outstanding shares of Series A Preferred Stock delivered a limited waiver related to their right to elect a Series A Director. The Certificate of Incorporation and the Bylaws provide that the Presidio Board shall be divided into three classes, as nearly equal in number as possible, with the directors in each class serving for a three-year term, and one class being elected each year by the stockholders.
When considering whether directors have the experience, qualifications, attributes or skills, taken as a whole, to enable the Presidio Board to satisfy its oversight responsibilities effectively in light of Presidio’s business and structure, the Presidio Board focuses primarily on each person’s background and experience as reflected in the information discussed in each of the directors’ individual biographies set forth above. We believe that the directors provide an appropriate mix of experience and skills relevant to the size and nature of Presidio’s business.
In connection with the Closing, the Registration Rights Parties, EQV, EQVR Intermediate, Prometheus Holdings and Presidio entered into a Registration and Stockholders’ Rights Agreement pursuant to which the Sponsor or its permitted transferees will have the right to designate two directors so long as they own, in the aggregate, greater than 20% of Presidio’s common equity or one director so long as they own, in the aggregate, greater than 10% of Presidio’s common equity. For a description of the terms of the Registration and Stockholders’ Rights Agreement, see “Certain Relationships and Related Person Transactions — Registration and Stockholders’ Rights Agreement.”
In accordance with the Certificate of Incorporation and the Bylaws, the Presidio Board is divided into three classes with staggered three year terms. At each annual meeting of stockholders after the initial classification, the successors to the directors whose terms will then expire will be elected to serve from the time of election and qualification until the third annual meeting following their election. The directors will be divided among the three classes as follows:
| ● | the Class I directors will be Jerry Schretter, James E. Vallee and Ray N. Walker, Jr. and their terms will expire at the annual meeting of stockholders to be held in 2027; |
| ● | the Class II directors will be Christopher L. Hammack, Jeffrey Serota and Tyson Taylor and their terms will expire at the annual meeting of stockholders to be held in 2028; and |
| ● | the Class III directors will be Daniel C. Herz, Jerry Silvey and William A. Ulrich, and their terms will expire at the annual meeting of stockholders to be held in 2029. |
Any increase or decrease in the number of directors will be distributed among the three classes so that, as nearly as possible, each class will consist of one-third of the directors. This classification of the Presidio Board may have the effect of delaying or preventing changes in control of Presidio. See “Description of Securities — Anti-Takeover Provisions.”
121
Director Independence
The Presidio Board has determined that each of Daniel C. Herz, Jerry Schretter, Jeffrey Serota, James E. Vallee and Ray N. Walker, Jr. qualify as an “independent director,” as defined under the NYSE rules. In making these determinations, the Presidio Board considered the current and prior relationships that each director has with Presidio and all other facts and circumstances the Presidio Board deemed relevant in determining his or her independence, including the beneficial ownership of Presidio Common Stock by each director, and the transactions involving them described in the section titled “Certain Relationships and Related Person Transactions.”
Committees of the Presidio Board
The Presidio Board directs the management of Presidio’s business and affairs, as provided by Delaware law, and conducts its business through meetings of the Presidio Board and its standing committees. The Presidio Board has three standing committees. In addition, from time to time, special committees may be established under the direction of the Presidio Board when necessary to address specific issues. Copies of the charters for each committee are available on Presidio’s website.
Audit Committee
Our audit committee is responsible for, among other things:
| ● | appointing, approving the fees of, retaining and overseeing our independent registered public accounting firm; |
| ● | discussing with our independent registered public accounting firm their independence from management; |
| ● | discussing with our independent registered public accounting firm any audit problems or difficulties and management’s response; |
| ● | approving all audit and permissible non-audit services to be performed by our independent registered public accounting firm; |
| ● | overseeing the financial reporting process and discussing with management and our independent registered public accounting firm the interim and annual financial statements that we file with the SEC; |
| ● | reviewing our policies on risk assessment and risk management; |
| ● | reviewing related person transactions; and |
| ● | establishing procedures for the confidential, anonymous submission of complaints regarding questionable accounting, internal controls or auditing matters. |
Our audit committee consists of Daniel C. Herz, Jerry Schretter and Ray N. Walker, Jr., with Jerry Schretter serving as Chairperson. The Presidio Board has affirmatively determined that Daniel C. Herz, Jerry Schretter and Ray N. Walker, Jr. each meet the definition of “independent director” for purposes of serving on the audit committee under the NYSE rules and the independence standards under Rule 10A-3 of the Exchange Act and the NYSE rules. Each member of our audit committee meets the financial literacy requirements of the NYSE rules. In addition, the Presidio Board has determined that Jerry Schretter qualifies as an “audit committee financial expert,” as such term is defined in Item 407(d)(5) of Regulation S-K. The Presidio Board has adopted a written charter for the audit committee, which is available on our principal corporate website at https://bypresidio.com/. The information on any of our websites is deemed not to be incorporated in this prospectus or to be a part of this prospectus.
Nominating and Corporate Governance Committee
Our nominating and corporate governance committee is responsible for, among other things:
| ● | identifying individuals qualified to become members of the Presidio Board, consistent with criteria approved by the Presidio Board as set forth in our corporate governance guidelines; |
| ● | annually reviewing the committee structure of the Presidio Board and recommending to the Presidio Board the directors to serve as members of each committee; and |
| ● | developing and recommending to the Presidio Board a set of corporate governance guidelines. |
Our nominating and corporate governance committee consists of Jeffrey Serota, James E. Vallee and Ray N. Walker, Jr. with Jeffrey Serota serving as Chairperson. The Presidio Board has affirmatively determined that Jeffrey Serota, James E. Vallee and Ray N. Walker, Jr. each meet the definition of “independent director” for the purposes of the independence standards under the NYSE rules. The Presidio Board has adopted a written charter for the nominating and corporate governance committee, which is available on our principal corporate website at https://bypresidio.com/. The information on any of our websites is deemed not to be incorporated in this prospectus or to be a part of this prospectus.
122
Compensation Committee
Our compensation committee is responsible for, among other things:
| ● | reviewing and approving, or recommending that the Presidio Board approve, the compensation of our Chief Executive Officer and other executive officers; |
| ● | making recommendations to the Presidio Board regarding director compensation; and |
| ● | reviewing and approving incentive compensation and equity-based plans and arrangements and making grants of cash-based and equity-based awards under such plans. |
Our compensation committee consists of Daniel C. Herz, Jeffrey Serota and James E. Vallee with Daniel C. Herz serving as Chairperson. The Presidio Board has affirmatively determined that Daniel C. Herz, Jeffrey Serota and James E. Vallee each meet the definition of “independent director” for the purposes of the independence standards under the NYSE rules. The Presidio Board has adopted a written charter for the compensation committee, which is available on our principal corporate website at https://bypresidio.com/. The information on any of our websites is deemed not to be incorporated in this prospectus or to be a part of this prospectus.
Risk Oversight
The Presidio Board is responsible for overseeing the risk management process. The Presidio Board focuses on Presidio’s general risk management policies and strategy and the most significant risks facing Presidio and will oversee the implementation of risk mitigation strategies by management. The Presidio Board will also be apprised of particular risk management matters in connection with its general oversight and approval of corporate matters and significant transactions.
Compensation Committee Interlocks and Insider Participation
None of the expected members of the Presidio Compensation Committee has ever been an executive officer or employee of Presidio. None of Presidio’s expected executive officers currently serves, or has served during the last completed fiscal year, on the Presidio Board or compensation committee (or other committee performing equivalent functions) of any entity that has one or more executive officers expected to serve on the Presidio Board or Compensation Committee.
Code of Business Conduct and Ethics
Presidio has adopted a written code of business conduct and ethics that applies to its directors, officers and employees, including its principal executive officer, principal financial officer, principal accounting officer or controller, or persons performing similar functions. A copy of the code is posted on its website, https://bypresidio.com/. In addition, Presidio intends to post on its website all disclosures that are required by law or the NYSE rules concerning any amendments to, or waivers from, any provision of the code. The information on any of Presidio’s websites is deemed not to be incorporated in this prospectus or to be part of this prospectus.
123
CERTAIN RELATIONSHIPS AND RELATED PERSON TRANSACTIONS
Registration and Stockholders’ Rights Agreement
In connection with the closing of the Business Combination, we entered into the Registration and Stockholders’ Rights Agreement with the Sponsor, certain equityholders of PIH, certain PIPE investors and other parties thereto. In connection with the Closing, EQVR Intermediate, the Sponsor, certain holders of PIH equity and certain members of Presidio’s management, EQV, Prometheus Holdings and Presidio entered into the Registration and Stockholders’ Rights Agreement.
Pursuant to the Registration and Stockholders’ Rights Agreement, the Sponsor (or its permitted transferees) has the right to designate two directors for appointment or election to Presidio’s board so long as they own in the aggregate greater than 20% of Presidio’s common equity and one director so long as they own in the aggregate greater than 10% of Presidio’s common equity. Additionally, pursuant to the terms of the Registration and Stockholders’ Rights Agreement, the Registration Rights Parties, and each of their permitted transferees, were granted certain customary registration rights, including demand and piggyback rights. In addition, certain of the Registration Rights Parties agreed, subject to the terms provided therein, that each such party will not transfer any of its registrable securities under the Registration and Stockholders’ Rights Agreement for a period ending 180 days after the Closing.
Warrant Agreement Assignment, Assumption and Amendment
On the Closing Date of the Business Combination, Presidio entered into the Warrant Agreement Amendment and Assignment, by and among Presidio, EQV and Continental. The Warrant Agreement Amendment and Assignment assigned the existing Warrant Agreement, dated August 6, 2024, by and between EQV and Continental to the Company, and the Company agreed to perform all applicable obligations under such agreement.
Pursuant to the Warrant Agreement Amendment and Assignment, EQV assigned all its rights, title and interest in the Existing Warrant Agreement to the Company and all references to warrants of EQV as contemplated under the Existing Warrant Agreement were replaced with references to Presidio Warrants, which are exercisable for shares of Presidio Class A Common Stock on the same terms that were in effect prior to the Closing under the terms of the Existing Warrant Agreement, except as described in the Warrant Agreement Amendment and Assignment.
Sponsor Arrangements
Founder Shares
In connection with EQV’s initial public offering, the Sponsor purchased Class B ordinary shares of EQV (the “Founder Shares”) for an aggregate purchase price of $25,000 and 400,000 private placement units at a purchase price of $10.00 per unit for an aggregate purchase price of $4,000,000. In connection with the Business Combination, such securities converted into shares of Presidio Class A Common Stock and Private Placement Warrants. The Sponsor holds shares of Presidio Class A Common Stock, a portion of which are subject to vesting and transfer restrictions as described below.
Earn-Out Shares and Time-Based Vesting Shares
Concurrently with the execution of the Business Combination Agreement, on August 5, 2025, EQV, the Sponsor, Presidio, Prometheus Holdings, PIH and certain members of EQV’s board of directors and/or management (the “Insiders”) entered into the Sponsor Letter Agreement, pursuant to which (a) each of the Sponsor and the Insiders agreed to vote in favor of the Business Combination Agreement and the Business Combination, (b) each of the Sponsor and the Insiders agreed to be bound by certain restrictions on transfer with respect to their equity interests in EQV prior to Closing, (c) the Sponsor agreed to be bound by certain lock-up provisions during the post-Closing lock-up periods described therein with respect to its equity interests in EQV, (d) the Sponsor agreed to subject certain of its Class B Shares to vesting (or forfeiture) on the basis of achieving certain trading price thresholds during the first five years following the Closing pursuant to an earnout program, (e) the Sponsor agreed to subject certain of its Class B Shares to time vesting during the first three years following the Closing pursuant to a dividend reinvestment program and (f) the Sponsor and the Insiders agreed to waive any adjustment to the conversion ratio set forth in the respective governing documents of any of EQV, Presidio, EQV Merger Sub, Prometheus Holdings, and Presidio Merger Sub or any other anti-dilution or similar protection with respect to any equity interests in EQV, as more fully set forth in the Sponsor Letter Agreement.
124
Pursuant to the Sponsor Letter Agreement, following the closing of the Business Combination and the conversion of the EQV Class B Shares and EQV private placement units into shares of Presidio Class A Common Stock and Private Placement Warrants, 1,851,161 shares of Presidio Class A Common Stock held by the Sponsor, which constitute the Earn-Out Shares, are subject to vesting based on the achievement of specified stock price targets and an additional 3,702,323 shares of Presidio Class A Common Stock held by the Sponsor, which constitute the DRIP Shares, are subject to time-based vesting over a three-year period following the closing of the Business Combination. The Earn-Out Shares are subject to forfeiture, and vest in two equal 50% increments if, over any 20 trading days within any 30 consecutive trading-day period during the five years following the Closing, the trading share price of the Presidio Class A Common Stock is greater than or equal to $12.50 per share and $15.00 per share, respectively (or if Presidio consummates a sale that would value such shares at the aforementioned thresholds). The DRIP Shares will vest in three tranches, with one-third of such shares vesting on the date that is 12 months following the Closing, one-half of the remainder of such shares vesting on the date that is 24 months following the Closing and the remaining of such shares vesting on the date that is 36 months following the Closing.
Sponsor and the Insiders also agreed to be bound by certain “lock-up” provisions. Pursuant to the terms and conditions of the Sponsor Letter Agreement, 1,851,161 of the Sponsor’s equity interests in EQV, which constitute the Lock-Up Shares, will be restricted from transfer for a period ending on the earlier of the date (i) that is 12 months following the Closing Date and (ii) upon which Presidio completes a liquidation, merger, share exchange or other similar transaction following the Closing Date that results in all the equityholders of Presidio having the right to exchange their shares of Presidio Class A Common Stock for cash, securities or other property, subject to customary exceptions and potential early-release 150 days after the Closing based on the stock price sustaining specified price thresholds for 20 trading days within any 30 consecutive trading-day period.
Prometheus Holdings LLC Agreement
Presidio is organized in an “Up-C” structure, such that Presidio and the subsidiaries of Presidio hold and operate substantially all of the assets and business of PIH, with Presidio being a publicly listed holding company that holds equity interests in PIH. On the Closing Date, Prometheus Holdings’ existing limited liability company agreement was amended and restated (the “Prometheus Holdings LLC Agreement”) to, among other things, provide its equityholders with the right to redeem their units of Prometheus Holdings for Presidio Class A Common Stock or, at the Company’s option, cash, in each case, subject to certain restrictions set forth therein. Pursuant to the Prometheus Holdings LLC Agreement, holders of Prometheus Holdings Common Units (together with the corresponding shares of Presidio Class B Common Stock) have the right, subject to the terms and conditions set forth therein, to exchange such units for shares of Presidio Class A Common Stock on a one-for-one basis (subject to customary adjustments), or, at our election, for cash.
Series A Preferred Stock and Series A Preferred Investor Warrants
Concurrently with the execution of the Business Combination Agreement, on August 5, 2025, EQV, the Company and PIH entered into the Series A Securities Purchase Agreement with the Series A Preferred Investors, pursuant to which the Series A Preferred Investors purchased in a private placement from the Company an aggregate of 125,000 shares of Series A Preferred Stock and 937,500 Series A Preferred Investor Warrants for a cash purchase price of $123,750,000 (net of all applicable original issue discounts). The Series A Preferred Stock has the rights, preferences, and privileges set forth in the Series A Preferred Certificate of Designation, and certain holders of shares of Series A Preferred Stock have certain rights pursuant to the Series A Preferred Stockholders’ Agreement.
125
At the Closing, each Series A Preferred Investor received shares of Series A Preferred Stock and Series A Preferred Investor Warrants to purchase a specified number of shares of Presidio Class A Common Stock, as set forth in the Series A Securities Purchase Agreement. In addition, the Company entered into the Series A Preferred Stockholders’ Agreement with certain Series A Preferred Investors at the Closing. The Series A Preferred Investor Warrants have an exercise price of $0.01, subject to adjustment as provided therein, and may be exercised for cash or on a cashless basis. The Series A Preferred Investor Warrants will become exercisable in two tranches, with 50% exercisable six months following the Closing and 50% exercisable 12 months following the Closing, and have a term of exercise equal to five years from the applicable exercise date, as provided further in the Series A Preferred Investor Warrants. The Company shall use commercially reasonable efforts to file a resale registration statement within 45 days following the Closing to register the Presidio Class A Common Stock underlying the Series A Preferred Investor Warrants, subject to certain conditions.
The Series A Securities Purchase Agreement contains customary representations and warranties by EQV, PIH, and the Series A Preferred Investors, including with respect to organization, authority, enforceability, compliance with laws, absence of conflicts, and the validity of the Series A Preferred Stock and Series A Preferred Investor Warrants. In addition, subject to certain conditions, so long as any shares of Series A Preferred Stock remain outstanding, the Series A Preferred Certificate of Designation will provide holders of a majority of the then issued and outstanding shares of Series A Preferred Stock the right to elect one Series A Director (as defined therein) and, in certain circumstances, two additional Preferred Stock Directors (as defined therein).
Series B Preferred Stock
In connection with the Business Combination, on February 23, 2026, EQV, Presidio and PIH entered the Series B Preferred Securities Purchase Agreement with the Series B Preferred Investor, pursuant to which, immediately prior to or substantially concurrently with the Closing, the Series B Preferred Investor purchased in a private placement from Presidio an aggregate of 27,173 shares of Series B Preferred Stock, with each share of Series B Preferred Stock convertible into 100 shares of Presidio Class A Common Stock and entitled to participate in dividends declared on shares of Presidio Class A Common Stock on an as-converted basis, for an aggregate cash purchase price of $25,000,000. The Series B Preferred Stock has the rights, preferences, and privileges set forth in Series B Preferred Certificate of Designation.
The Series B Securities Purchase Agreement contains customary representations and warranties by EQV, Presidio, PIH, and the Series B Preferred Investor, including with respect to organization, authority, enforceability, compliance with laws, absence of conflicts, and the validity of the Series B Preferred Stock issued. Presidio shall use commercially reasonable efforts to register the Presidio Class A Common Stock issuable upon conversion of the Series B Preferred Stock on a resale registration statement within 45 days following the Closing.
PIPE Subscription Agreements
Concurrently with the execution of the Business Combination Agreement, on August 5, 2025, EQV and the Company entered into subscription agreements with the PIPE Investors pursuant to which, among other things, the PIPE Investors subscribed for and purchased an aggregate of 8,750,000 shares of Presidio Class A Common Stock to be issued by the Company following the Domestication for a purchase price of $10.00 per share, on the terms and subject to the conditions set forth therein. Each Subscription Agreement contains customary representations and warranties of EQV and the Company, on the one hand, and the PIPE Investor, on the other hand. At the Closing, the Company issued an aggregate of 8,750,000 shares of Presidio Class A Common Stock to the PIPE Investors.
Private Placement Warrants
Concurrently with the SPAC IPO, the Sponsor purchased 400,000 Private Placement Units for an aggregate purchase price of $4,000,000, consisting of 400,000 EQV Class A Shares and 133,333 EQV private placement warrants. Following the Closing, the EQV Class A Shares converted to Presidio Class A Common Stock and the EQV private placement warrants converted to Private Placement Warrants and after giving effect to the Non-Redemption Agreement, the Sponsor owned 282,314 shares of Presidio Class A Common Stock and 133,332 Private Placement Warrants.
Director and Officer Indemnification Agreements
We have entered into indemnification agreements with each of our directors and executive officers. These agreements provide for indemnification and advancement of expenses to the fullest extent permitted by Delaware law and our Certificate of Incorporation and Bylaws.
Statement of Policy Regarding Transactions with Related Persons
Presidio has adopted a formal written policy providing that Presidio’s officers, directors, nominees for election as directors, beneficial owners of more than 5% of any class of Presidio’s capital stock, any member of the immediate family of any of the foregoing persons and any firm, corporation or other entity in which any of the foregoing persons is employed or is a general partner or principal or in a similar position or in which such person has a 5% or greater beneficial ownership interest, are not permitted to enter into a related party transaction with Presidio without the approval of Presidio’s audit committee, subject to certain exceptions.
126
DESCRIPTION OF SECURITIES
Unless the context requires otherwise, for the purposes of this section, references to “we,” “us” and “our” refer to Presidio Production Company.
General
The following summary sets forth the material terms of our securities. The following summary is not intended to be a complete summary of the rights, powers and preferences of such securities, and is qualified by reference to the Certificate of Incorporation, the Bylaws, the agreements governing the Presidio Warrants and the Series A Preferred Investor Warrants and the forms of the Presidio Warrants and the Series A Preferred Investor Warrants. We urge you to read the Certificate of Incorporation, the Bylaws, the agreements governing the Presidio Warrants and the Series A Preferred Investor Warrants and the forms of the Presidio Warrants and the Series A Preferred Investor Warrants in their entirety for a complete description of the rights, powers and preferences of our securities.
Certain provisions of the Certificate of Incorporation and the Bylaws summarized below may be deemed to have an anti-takeover effect and may delay or prevent a tender offer or takeover attempt that a stockholder might consider in its best interest, including those attempts that might result in a premium over the market price for the shares of common stock.
The Certificate of Incorporation authorizes capital stock consisting of:
| ● | shares of Presidio Class A Common Stock, par value $0.0001 per share; |
| ● | shares of Presidio Class B Common Stock, par value $0.0001 per share; and |
| ● | shares of Preferred Stock, par value $0.0001 per share. |
Common Stock
Class A Common Stock
Holders of Presidio Class A Common Stock are entitled to one vote for each share held of record on all matters submitted to a vote of stockholders and on which the holders of Presidio Class A Common Stock are entitled to vote.
Holders of Presidio Class A Common Stock are entitled to receive dividends when and if declared by our board of directors out of funds legally available therefor, subject to any statutory or contractual restrictions on the payment of dividends and to any restrictions on the payment of dividends imposed by the terms of any outstanding preferred stock.
Upon our dissolution or liquidation, after payment in full of all amounts required to be paid to creditors and to the holders of preferred stock having liquidation preferences, if any, the holders of Presidio Class A Common Stock will be entitled to receive pro rata our remaining assets available for distribution.
Holders of Presidio Class A Common Stock do not have preemptive, subscription, redemption or conversion rights. There are no redemption or sinking fund provisions applicable to the Presidio Class A Common Stock.
Holders of Presidio Class A Common Stock vote together with holders of Presidio Class B Common Stock, as a single class on all matters presented to our stockholders for their vote or approval, except for certain amendments to the Certificate of Incorporation or as otherwise required by applicable law or the Certificate of Incorporation. Any amendment to the Certificate of Incorporation that gives holders of Presidio Class B Common Stock (i) any rights to receive dividends (subject to certain exceptions) or any other kind of distribution, (ii) any right to convert into or be exchanged for shares of Presidio Class A Common Stock, or (iii) any other economic rights (except for payments in cash in lieu of receipt of fractional stock) shall, in addition to the vote of the holders of shares of any class or series of our capital stock required by law, also require the affirmative vote of the holders of a majority of the voting power of the outstanding shares of Presidio Class A Common Stock voting separately as a class.
Class B Common Stock
Shares of Presidio Class B Common Stock are issued to, and held by, holders of Prometheus Holdings Common Units (other than Presidio) to maintain a one-to-one ratio between (i) the number of Prometheus Holdings Common Units held by such holders and (ii) the number of shares of Presidio Class B Common Stock issued to such holders. Shares of Presidio Class B Common Stock will be issued in the future only to the extent necessary to maintain a one-to-one ratio between the number of Prometheus Holdings Common Units held by the Prometheus Holdings Unitholders and the number of shares of Presidio Class B Common Stock issued to the Prometheus Holdings Unitholders. Shares of Presidio Class B Common Stock are transferable only together with an equal number of Prometheus Holdings Common Units. Only permitted transferees of Prometheus Holdings Common Units held by the Prometheus Holdings Unitholders will be permitted transferees of Presidio Class B Common Stock. See “Certain Relationships and Related Person Transactions — Prometheus Holdings LLC Agreement.”
127
Each share of the Presidio Class B Common Stock entitles its holders to one vote per share on all matters presented to our stockholders generally.
Holders of shares of the Presidio Class B Common Stock will vote together with holders of the Presidio Class A Common Stock as a single class on all matters presented to our stockholders for their vote or approval, except for certain amendments to the Certificate of Incorporation relating to the terms, number of shares, powers, designations, preferences or relative, participating or other special rights, or to qualifications, limitations or restrictions thereof, of one or more outstanding series of Preferred Stock if the holders of such affected series are entitled, either separately or together with the holders of one or more other such series, to vote thereon or as otherwise required by applicable law or the Certificate of Incorporation.
Except in certain limited circumstances, holders of the Presidio Class B Common Stock do not have any right to receive dividends or to receive a distribution upon dissolution or liquidation. Additionally, holders of shares of the Presidio Class B Common Stock do not have preemptive, subscription, redemption or conversion rights. There will be no redemption or sinking fund provisions applicable to the Presidio Class B Common Stock. Upon the redemption or exchange of an Prometheus Holdings Common Unit (together with a share of Presidio Class B Common Stock) for Presidio Class A Common Stock, the shares of Presidio Class B Common Stock will be automatically transferred to Presidio for no consideration and will be canceled and no longer outstanding. Such shares of Presidio Class B Common Stock may not be reissued. Any amendment of the Certificate of Incorporation that gives holders of the Presidio Class B Common Stock (i) any rights to receive dividends or any other kind of distribution, (ii) any right to convert into or be exchanged for Presidio Class A Common Stock or (iii) any other economic rights will require, in addition to stockholder approval, the affirmative vote of holders of the Presidio Class A Common Stock voting separately as a class.
The Prometheus Holdings Unitholders currently own, in the aggregate, 1,673,757 shares of the Presidio Class B Common Stock.
Preferred Stock
The total authorized shares of preferred stock is 50,000,000 shares. We currently have 153,801 shares of preferred stock outstanding, 126,628 of which are shares of Series A Preferred Stock and 27,173 of which are shares of Series B Preferred Stock.
Under the terms of the Certificate of Incorporation, our board of directors is authorized to direct us to issue shares of preferred stock in one or more series without stockholder approval. Our board of directors has the discretion to determine the rights, preferences, privileges and restrictions, including voting rights, dividend rights, conversion rights, redemption privileges and liquidation preferences, of each series of preferred stock.
The purpose of authorizing our board of directors to issue preferred stock and determine its rights and preferences is to eliminate delays associated with a stockholder vote on specific issuances. The issuance of preferred stock, such as the Series A Preferred Stock and the Series B Preferred Stock, while providing flexibility in connection with possible acquisitions, future financings and other corporate purposes, could have the effect of making it more difficult for a third party to acquire, or could discourage a third party from seeking to acquire, a majority of our outstanding voting stock. Additionally, the issuance of preferred stock may adversely affect the holders of the Presidio Class A Common Stock by restricting dividends on the Presidio Class A Common Stock, diluting the voting power of the Presidio Class A Common Stock or subordinating the liquidation rights of the Presidio Class A Common Stock. As a result of these or other factors, the issuance of preferred stock could have an adverse impact on the market price of the Presidio Class A Common Stock.
128
Series A Preferred Stock
In connection with the Series A Preferred Financing, the board of directors of Presidio has adopted the Series A Preferred Certificate of Designation.
Dividends
From and including the original issuance date of March 4, 2026 to, but excluding, the third anniversary of the Closing on March 4, 2029 (the “Step Up Date”), the Series A Preferred Stock will accrue cumulative quarterly dividends on the then-current investment amount at a rate of 12.0% per annum. On and after the Step Up Date, the dividend rate will increase on a quarterly basis by 0.25% per annum until the rate reaches 16.0% per annum. Prior to the fifth anniversary of the Closing on March 4, 2031, dividends will be payable in cash at a rate of at least 8.0% per annum, with the remainder payable, at Presidio’s option, in cash or in kind in additional shares of Series A Preferred Stock. After the fifth anniversary of the Closing, all dividends will be payable in cash until all shares of Series A Preferred Stock have been redeemed. Dividends will be payable quarterly in arrears on February 28, May 31, August 31 and November 30 of each year and will accrue on a daily basis. The dividend rate will increase by 2.0% per annum if Presidio fails to pay a required cash dividend before the Step Up Date or upon the occurrence and during the continuance of certain trigger events, and will remain at such increased rate until the relevant event is cured.
Liquidation preference
Upon any liquidation, dissolution or winding up of Presidio, the holders of Series A Preferred Stock will be entitled to receive out of the available proceeds, before any distribution is made to holders of common stock or any other junior securities, an amount per share equal to the greater of (i) 125% of the subscription amount for such share or (ii) the amount required to achieve a 12.0% internal rate of return on such subscription amount, in each case including accrued and unpaid dividends, subject to certain additional adjustments. If, upon any such liquidation, dissolution or winding up of Presidio, the assets of Presidio available for distribution are insufficient to pay the full amount due to the holders of the Series A Preferred Stock, the holders will share ratably in any distribution of assets in proportion to the respective amounts that would otherwise be payable.
Voting, consent and approval rights
Except as otherwise required by law or as provided in the Series A Preferred Certificate of Designation, holders of the Series A Preferred Stock will not have voting, consent or approval rights. However, for so long as any shares of Series A Preferred Stock remain outstanding, the holders of record of the Series A Preferred Stock, voting as a separate class from the Presidio Common Stock, will be entitled to elect one director of Presidio (the “Series A Preferred Director”). Additionally, each holder of Series A Preferred Stock will have one vote per share on any matter on which such holders are entitled to vote separately as a class.
In addition, certain actions by Presidio will require the consent of the holders of at least a majority of the outstanding shares of Series A Preferred Stock, including (i) any amendments to the Series A Preferred Certificate of Designation or Presidio’s governing documents that materially adversely affect the rights, preferences or privileges of the Series A Preferred Stock (a “Material Adverse Amendment”), (ii) the issuance of equity securities ranking senior to or on parity with the Series A Preferred Stock, (iii) exceeding certain specified annual limits for cash or cash capitalized general and administrative expenses or cash capital expenditures, (iv) incurrence of certain indebtedness above specified thresholds, (v) entering into any agreements that would restrict the payment of dividends to the holders of Series A Preferred Stock or the redemption of Series A Preferred Stock to a materially more restrictive extent than as provided in the Series A Preferred Certificate of Designation, or (vi) taking any action that would constitute a mandatory redemption event without paying the redemption price in full. Upon the occurrence and continuance of certain events, including the occurrence and continuation of an event of default under certain debt documents or the failure of Presidio to make certain required payments or redemptions pursuant to the Series A Preferred Certificate of Designation, the holders of the Series A Preferred Stock (together with any other series having similar rights) will have the right to elect two Preferred Stock Directors.
129
Protective provisions
The Series A Preferred Certificate of Designation contains additional covenants, including requirements to use available excess cash for partial redemptions under certain leverage, coverage or production conditions, limitations on indebtedness during specified adverse circumstances, and requirements to maintain certain minimum hedge positions.
Redemption
The Series A Preferred Stock are redeemable at the option of Presidio, in whole or in part, at any time at a price equal to the liquidation preference discussed above. Presidio will be required to redeem all outstanding shares of Series A Preferred Stock within 120 days after the occurrence of certain mandatory redemption events, including (i) a liquidation, dissolution or winding up of Presidio, (ii) the sale or transfer of greater than 55% of the properties or assets of Presidio and its subsidiaries on a consolidated basis, (iii) a change of control or (iv) a material change in Presidio’s investment strategy or a Material Adverse Amendment without preferred holder consent. Redemptions are subject to applicable law governing distributions to stockholders.
Transfer restrictions
Certain holders of the Series A Preferred Stock who are party to the Series A Securities Purchase Agreement will at all times own in the aggregate not less than 51% of the shares of Series A Preferred Stock and a corresponding majority of the voting rights of the class. Such holders will not be permitted, without Presidio’s prior written consent, conditioned or delayed, to sell, assign, transfer, or otherwise dispose of any shares of Series A Preferred Stock, or any interest therein, to any direct or indirect competitors of Presidio or any of its subsidiaries in the proved developed producing oil and gas sector or to any person listed on Presidio’s restricted transferees list, as attached to the Series A Preferred Certificate of Designation.
Series B Preferred Stock
In connection with the Series B Preferred Financing, the board of directors of Presidio has adopted the Series B Preferred Certificate of Designation.
Dividends
From and after the original issuance date of any shares of Series B Preferred Stock, the holders of the Series B Preferred Stock will be entitled to receive dividends when, as and if declared by the board of directors of Presidio and as otherwise provided in Presidio’s amended and restated certificate of incorporation, out of funds legally available therefor. If Presidio declares, pays or sets apart any dividend or other distribution on its common stock, Presidio will simultaneously declare, pay and/or set apart for payment or distribution for each share of Series B Preferred Stock a dividend and/or distribution in an amount equal to the amount the holder of the Series B Preferred Stock would be entitled to receive if the holder had converted the Series B Preferred Stock into common stock and had held such shares of common stock on the record date for such dividends and distributions. Payments will be made concurrently with the dividend or distribution to the holders of common stock. The Series B Preferred Stock ranks junior to the Series A Preferred Stock as to the payment of any dividends by Presidio.
Liquidation preference
Upon any liquidation, dissolution or winding up of Presidio, the holders of Series B Preferred Stock will be entitled to receive the same payment of dividends or distributions of assets as if each such holder had converted each share of Series B Preferred Stock owned by such holder into common stock immediately prior to such liquidation, dissolution or winding up of Presidio.
The Series B Preferred Stock ranks pari passu with all of the common stock and any other class or series of capital stock of Presidio currently existing or hereafter authorized, classified or reclassified by Presidio and not expressly made senior to or on parity with the Series B Preferred Stock and ranks junior to the Series A Preferred Stock, in each case, as to the payment of dividends or distributions of assets upon liquidation, dissolution or winding up of Presidio, whether voluntarily or involuntarily. The Series B Preferred Stock also ranks junior to Presidio’s existing and future indebtedness.
130
Conversion
Each share of Series B Preferred Stock is convertible, at any time and from time to time at the option of the holder, into 100 shares of common stock, in accordance with and subject to the limitations set forth in the Series B Preferred Certificate of Designation. If any shares of Series B Preferred Stock are transferred to any person that is not an affiliate of the holder in compliance with the transfer restrictions described below, each such share of Series B Preferred Stock will be automatically converted into 100 shares of common stock at the closing of such transfer, subject to adjustment as described in the Series B Preferred Certificate of Designation.
Voting, consent and approval rights
Except as otherwise required by law or as provided in the Series B Preferred Certificate of Designation, holders of the Series B Preferred Stock will not have voting, consent or approval rights.
Transfer restrictions
The Series B Preferred Stock may not be transferred, assigned or pledged at any time without Presidio’s prior written consent, subject to applicable law.
The foregoing descriptions of the Series A Preferred Stock and Series B Preferred Stock do not purport to be complete and are qualified in their entirety by reference to the full texts of the Series A Preferred Certificate of Designation and the Series B Preferred Certificate of Designation, copies of which are filed as Exhibits 3.4 and 3.5 hereto, respectively, and are incorporated herein by reference.
Warrants
Presidio currently has outstanding (i) the Public Warrants, (ii) the Private Placement Warrants, and (iii) the Series A Preferred Investor Warrants.
Holders of warrants do not have the rights or privileges of holders of Presidio Class A Common Stock, including voting or dividend rights, until they exercise their warrants and receive shares of Presidio Class A Common Stock.
Public Warrants
Each whole Public Warrant entitles the registered holder to purchase one share of Presidio Class A Common Stock at a price of $11.50 per share, subject to adjustment as described below under “— Anti-Dilution Adjustments.” The Public Warrants may be exercised only if the last reported sale price of Presidio Class A Common Stock is at or above the exercise price in effect at the time of exercise, unless a cashless exercise is permitted under the circumstances described in the Warrant Agreement. The Public Warrants became exercisable on March 23, 2026. The Public Warrants will expire at 5:00 p.m., New York City time, on March 4, 2031 (the date that is five years after the consummation of the Business Combination), or earlier upon redemption or liquidation.
We are not obligated to deliver any shares of Presidio Class A Common Stock pursuant to the exercise of a Public Warrant and have no obligation to settle such warrant exercise unless a registration statement under the Securities Act covering the issuance of the shares of Presidio Class A Common Stock issuable upon exercise of the Public Warrants is then effective and a current prospectus relating thereto is current, or a valid exemption from registration is available. No Public Warrant is exercisable for cash or on a cashless basis, and we are not obligated to issue any shares to holders seeking to exercise their Public Warrant, unless the issuance of the shares of Presidio Class A Common Stock upon such exercise is registered or qualified under the securities laws of the state of the exercising holder, or an exemption is available. In the event that the conditions in the two immediately preceding sentences are not satisfied with respect to a Public Warrant, the holder of such warrant will not be entitled to exercise such warrant and such warrant may have no value and expire worthless. In no event will we be required to net cash settle any warrant.
131
In order to comply with the requirements of Section 10(a)(3) of the Securities Act following the Closing, we registered the Presidio Class A Common Stock issuable upon the exercise of the Public Warrants in a registration statement that was declared effective by the Securities and Exchange Commission on March 23, 2026, and we will use our commercially reasonable efforts to maintain the effectiveness of the registration statement and a current prospectus relating thereto until the Public Warrants expire or are redeemed, as specified in the Warrant Agreement; provided that if shares of Presidio Class A Common Stock are at the time of any exercise of a warrant not listed on a national securities exchange such that they satisfy the definition of a “covered security” under Section 18(b)(1) of the Securities Act, we may, at our option, require holders of the Public Warrants who exercise their warrants to do so on a “cashless basis” in accordance with Section 3(a)(9) of the Securities Act and, in the event we so elect, we will not be required to file or maintain in effect a registration statement, but we will use our commercially reasonable efforts to register or qualify the issuance of shares under applicable blue sky laws to the extent an exemption is not available. Warrant holders may, during any period when we will have failed to maintain an effective registration statement, exercise warrants on a “cashless basis” in accordance with Section 3(a)(9) of the Securities Act or another exemption. In such event, each holder would pay the exercise price by surrendering the warrants for that number of Presidio Class A Common Stock equal to the quotient obtained by dividing (x) the product of the number of Presidio Class A Common Stock underlying the warrants, multiplied by the excess of the “fair market value” (as defined below) of Presidio Class A Common Stock less the exercise price of the warrants by (y) the fair market value of Presidio Class A Common Stock. The “fair market value” as used in this paragraph means the average reported last sale price of Presidio Class A Common Stock for the 10 trading days ending on the third trading day prior to the date on which the notice of exercise is received by the warrant agent.
Redemption of Public Warrants when the price per share of Presidio Class A Common Stock equals or exceeds $18.00
Presidio may redeem the outstanding Public Warrants:
| ● | in whole and not in part; |
| ● | at a price of $0.01 per Public Warrant; |
| ● | upon not less than 30 days’ prior written notice of redemption given after the warrants become exercisable to each warrant holder; and |
| ● | if, and only if, the closing price of Presidio Class A Common Stock equals or exceeds $18.00 per share (as adjusted for adjustments to the number of shares issuable upon exercise or the exercise price of a warrant as described under the heading “— Anti-Dilution Adjustments”) for any 20 trading days within a 30-trading day period ending on the third trading day prior to the date on which the notice of redemption is sent to the warrant holders. |
We will not redeem the Public Warrants unless such warrants are then exercisable and an effective registration statement under the Securities Act covering the issuance of the shares of Presidio Class A Common Stock issuable upon exercise of the Public Warrants is then effective and a current prospectus relating to those shares is available throughout the 30-day redemption period. If and when the warrants become redeemable by us, we may exercise our redemption right even if we are unable to register or qualify the underlying securities for sale under all applicable state securities laws.
We have established the last of the redemption criteria discussed above to prevent a redemption call unless there is at the time of the call a significant premium to the warrant exercise price. If the foregoing conditions are satisfied and we issue a notice of redemption of the warrants, each warrant holder will be entitled to exercise his, her or its warrant prior to the scheduled redemption date. However, the price of Presidio Class A Common Stock may fall below the $18.00 redemption trigger price (as adjusted for adjustments to the number of shares issuable upon exercise or the exercise price of a warrant as described under the heading “— Anti-Dilution Adjustments”) as well as the $11.50 (for whole shares) warrant exercise price after the redemption notice is issued.
If we call the Public Warrants for redemption as described above, we will have the option to require any holder that wishes to exercise its Public Warrants to do so on a “cashless basis.” In determining whether to require all holders to exercise their Public Warrants on a “cashless basis,” we will consider, among other factors, our cash position, the number of Public Warrants that are outstanding and the dilutive effect on our shareholders of issuing the maximum number of Presidio Class A Common Stock issuable upon the exercise of our Public Warrants. If we take advantage of this option, all holders of Public Warrants would pay the exercise price by surrendering their Public Warrants for that number of Presidio Class A Common Stock equal to the quotient obtained by dividing (x) the product of the number of Presidio Class A Common Stock underlying the warrants, multiplied by the difference between the exercise price of the warrants and the “fair market value” (as defined below) of Presidio Class A Common Stock by (y) the fair market value of Presidio Class A Common Stock. The “fair market value” as used in this paragraph means the average last reported sale price of Presidio Class A Common Stock for the 10 trading days ending on the third trading day immediately prior to the date on which the notice of redemption is sent to the holders of the warrants. If we take advantage of this option, the notice of redemption will contain the information necessary to calculate the number of Presidio Class A Common Stock to be received upon exercise of the warrants, including the “fair market value” in such case. Requiring a cashless exercise in this manner will reduce the number of shares to be issued and thereby lessen the dilutive effect of a warrant redemption.
132
No fractional Presidio Class A Common Stock will be issued upon exercise. If, upon exercise, a holder would be entitled to receive a fractional interest in a share, we will round down to the nearest whole number of the number of Presidio Class A Common Stock to be issued to the holder. If, at the time of redemption, the warrants are exercisable for a security other than Presidio Class A Common Stock pursuant to the warrant agreement, the warrants may be exercised for such security. At such time as the warrants become exercisable for a security other than Presidio Class A Common Stock, Presidio (or the surviving company) will use its commercially reasonable efforts to register under the Securities Act the security issuable upon the exercise of the warrants.
Ownership limits
A holder of a warrant may notify us in writing in the event it elects to be subject to a requirement that such holder will not have the right to exercise such warrant, to the extent that after giving effect to such exercise, such person (together with such person’s affiliates), to the warrant agent’s actual knowledge, would beneficially own in excess of 9.8% (or such other amount as a holder may specify) of the shares of Presidio Class A Common Stock issued and outstanding immediately after giving effect to such exercise.
Anti-dilution adjustments
If the number of outstanding shares of Presidio Class A Common Stock is increased by a capitalization or stock dividend payable in shares of Presidio Class A Common Stock, or by a sub-division of Presidio Class A Common Stock or other similar event, then, on the effective date of such capitalization or stock dividend, sub-division or similar event, the number of shares of Presidio Class A Common Stock issuable on exercise of each warrant will be increased in proportion to such increase in the outstanding Presidio Class A Common Stock. A rights offering made to all or substantially all holders of Presidio Class A Common Stock entitling holders to purchase shares of Presidio Class A Common Stock at a price less than the “historical fair market value” (as defined below) will be deemed a stock dividend of a number of shares of Presidio Class A Common Stock equal to the product of (i) the number of shares of Presidio Class A Common Stock actually sold in such rights offering (or issuable under any other equity securities sold in such rights offering that are convertible into or exercisable for shares of Presidio Class A Common Stock) and (ii) one minus the quotient of (x) the price per Presidio Class A Common Stock paid in such rights offering and (y) the historical fair market value. For these purposes, (i) if the rights offering is for securities convertible into or exercisable for shares of Presidio Class A Common Stock, in determining the price payable for shares of Presidio Class A Common Stock, there will be taken into account any consideration received for such rights, as well as any additional amount payable upon exercise or conversion and (ii) “historical fair market value” means the volume weighted average price of shares of Presidio Class A Common Stock as reported during the 10 trading day period ending on the trading day prior to the first date on which the shares of Presidio Class A Common Stock trade on the applicable exchange or in the applicable market, regular way, without the right to receive such rights.
If the number of outstanding shares of Presidio Class A Common Stock is decreased by a consolidation, combination or reclassification of shares of Presidio Class A Common Stock or other similar event, then, on the effective date of such consolidation, combination, reclassification or similar event, the number of shares of Presidio Class A Common Stock issuable on exercise of each warrant will be decreased in proportion to such decrease in outstanding shares of Presidio Class A Common Stock.
Whenever the number of shares of Presidio Class A Common Stock purchasable upon the exercise of the warrants is adjusted, as described above, the warrant exercise price will be adjusted by multiplying the warrant exercise price immediately prior to such adjustment by a fraction (x) the numerator of which will be the number of shares of Presidio Class A Common Stock purchasable upon the exercise of the warrants immediately prior to such adjustment and (y) the denominator of which will be the number of shares of Presidio Class A Common Stock so purchasable immediately thereafter.
133
In case of any reclassification or reorganization of the outstanding shares of Presidio Class A Common Stock (other than those described above or that solely affect the par value of such shares of Presidio Class A Common Stock), or in the case of any merger or consolidation of us with or into another corporation (other than a consolidation or merger in which we are the continuing corporation and that does not result in any reclassification or reorganization of our outstanding shares of Presidio Class A Common Stock), or in the case of any sale or conveyance to another corporation or entity of the assets or other property of us as an entirety or substantially as an entirety in connection with which we are dissolved, the holders of the warrants will thereafter have the right to purchase and receive, upon the basis and upon the terms and conditions specified in the warrants and in lieu of the shares of Presidio Class A Common Stock immediately theretofore purchasable and receivable upon the exercise of the rights represented thereby, the kind and amount of Presidio Class A Common Stock or other securities or property (including cash) receivable upon such reclassification, reorganization, merger or consolidation, or upon a dissolution following any such sale or transfer, that the holder of the warrants would have received if such holder had exercised their warrants immediately prior to such event.
The warrants were issued in registered form under a warrant agreement between the Transfer Agent, as warrant agent, and EQV, which was assumed by Presidio in connection with the Closing pursuant to the Warrant Agreement Amendment and Assignment. The warrant agreement provides that the terms of the warrants may be amended without the consent of any holder for the purpose of (i) curing any ambiguity or to correct any mistake, including to conform the provisions of the warrant agreement to the description of the terms of the warrants and the warrant agreement set forth in this prospectus, or defective provision, (ii) amending the provisions relating to cash dividends on Presidio Class A Common Stock as contemplated by and in accordance with the warrant agreement or (iii) adding or changing any provisions with respect to matters or questions arising under the warrant agreement as the parties to the warrant agreement may deem necessary or desirable and that the parties deem to not adversely affect the rights of the registered holders of the warrants, provided that the approval by the holders of at least 50% of the then-outstanding Public Warrants is required to make any change that adversely affects the interests of the registered holders.
The warrant holders do not have the rights or privileges of holders of Presidio Class A Common Stock and any voting rights until they exercise their warrants and receive shares of Presidio Class A Common Stock. After the issuance of shares of Presidio Class A Common Stock upon exercise of the warrants, each holder will be entitled to one vote for each share held of record on all matters to be voted on by shareholders.
We have agreed that, subject to applicable law, any action, proceeding or claim against us arising out of or relating in any way to the warrant agreement will be brought and enforced in the courts of the State of New York or the United States District Court for the Southern District of New York, and we irrevocably submit to such jurisdiction, which jurisdiction will be the exclusive forum for any such action, proceeding or claim. This provision applies to claims under the Securities Act but does not apply to claims under the Exchange Act or any claim for which the federal district courts of the United States of America are the sole and exclusive forum. We note, however, that there is uncertainty as to whether a court would enforce this provision and that investors cannot waive compliance with the federal securities laws and the rules and regulations thereunder. Section 22 of the Securities Act creates concurrent jurisdiction for state and federal courts over all suits brought to enforce any duty or liability created by the Securities Act or the rules and regulations thereunder.
Private Placement Warrants
The Private Placement Warrants, including Presidio Class A Common Stock issuable upon exercise of the warrants, are not transferable, assignable or salable until 30 days after the Closing (other than to certain permitted transferees who agree to be bound by these restrictions), and the Private Placement Warrants are not redeemable by us.
If holders of the Private Placement Warrants elect to exercise the warrants on a cashless basis, they would pay the exercise price by surrendering his, her or its warrants for that number of shares of Presidio Class A Common Stock equal to the quotient obtained by dividing (x) the product of the number of shares of Presidio Class A Common Stock underlying the warrants, multiplied by the difference between the exercise price of the warrants and the “sponsor fair market value” (defined below), by (y) the sponsor fair market value. For these purposes, the “sponsor fair market value” shall mean the average last reported sale price of the shares of Presidio Class A Common Stock for the trading days ending on the third trading day prior to the date on which the notice of warrant exercise is sent to the warrant agent.
134
Series A Preferred Investor Warrants
At the Closing, in connection with the Series A Securities Purchase Agreement, Presidio issued Series A Preferred Investor Warrants to purchase 937,500 shares of Presidio’s Class A Common Stock to the Series A Preferred Investors.
Each whole Series A Preferred Investor Warrant entitles the registered holder to purchase one share of Presidio Class A Common Stock at an exercise price of $0.01, subject to adjustment as described below under “— Anti-Dilution Adjustments for Series A Preferred Investor Warrants.” Fifty percent (50%) of each holder’s Series A Preferred Investor Warrants became exercisable six months after the Closing on September 4, 2026, and the remaining 50% will become exercisable 12 months after the Closing beginning March 4, 2027. Each tranche will be exercisable until September 4, 2031 and March 4, 2032, respectively, for a term of five years from the date on which such tranche becomes exercisable. The warrants may be exercised for cash or on a cashless basis for a number of shares determined using a formula based on the difference between the exercise price and the market price at the time of such cashless exercise. The Series A Preferred Investor Warrants are not redeemable by us.
We are not obligated to deliver any shares of Class A Common Stock pursuant to the exercise of a Series A Preferred Investor Warrant and have no obligation to settle such warrant exercise unless either (i) a registration statement under the Securities Act covering the issuance of the shares of Presidio Class A Common Stock issuable upon exercise of the Series A Preferred Investor Warrants is then effective and a current prospectus relating thereto is available or (ii) the shares of Presidio Class A Common Stock issuable upon such exercise are eligible for resale without volume or manner-of-sale limitations pursuant to Rule 144 under the Securities Act and without the requirement for us to be in compliance with the current public information requirement under Rule 144(c)(1) or Rule 144(i)(2). In the event that these conditions are not satisfied with respect to a Series A Preferred Investor Warrant, the holder of such warrant will not be entitled to exercise such warrant for cash, but may be able to exercise the warrant on a “cashless basis” in accordance with Section 3(a)(9) of the Securities Act or another exemption from registration. In no event will we be required to net cash settle any Series A Preferred Investor Warrant.
Holders of the Series A Preferred Investor Warrants have the right to participate in pro rata distributions of assets (including cash or securities) to holders of Presidio Class A Common Stock, to the same extent as if the warrants had been exercised in full without regard to ownership limitations.
Ownership limits for Series A Preferred Investor Warrants
A holder of a Series A Preferred Investor Warrant may notify us in writing in the event it elects to be subject to a requirement that such holder will not have the right to exercise such warrant to the extent that, after giving effect to such exercise, such person (together with such person’s affiliates and certain attribution parties) would beneficially own in excess of 9.99% of the shares of Presidio Class A Common Stock outstanding immediately after giving effect to such exercise, which limit may be increased by the holder up to 19.99% upon 61 days’ prior written notice. For purposes of this limitation, beneficial ownership is calculated in accordance with Section 13(d) of the Exchange Act and the rules and regulations promulgated thereunder. This limitation may be decreased by the holder at any time, and any such decrease will be effective immediately upon notice to us.
Anti-dilution adjustments for Series A Preferred Investor Warrants
If the number of outstanding shares of Presidio Class A Common Stock is increased by a stock dividend payable in shares of Presidio Class A Common Stock, or by a stock split of Presidio Class A Common Stock or other similar event, then, on the effective date of such stock dividend, stock split or similar event, the number of shares of Presidio Class A Common Stock issuable on exercise of each Series A Preferred Investor Warrant will be increased in proportion to such increase in the outstanding shares of Presidio Class A Common Stock. Similarly, if the number of outstanding shares of Presidio Class A Common Stock is decreased by a consolidation, combination, reverse stock split or reclassification of shares of Presidio Class A Common Stock or other similar event, then, on the effective date of such consolidation, combination, reverse stock split, reclassification or similar event, the number of shares of Presidio Class A Common Stock issuable on exercise of each Series A Preferred Investor Warrant will be decreased in proportion to such decrease in outstanding shares of Presidio Class A Common Stock.
135
In addition, the exercise price of each Series A Preferred Investor Warrant will be proportionally adjusted for any such event so that the aggregate exercise price for the warrant remains unchanged. The Series A Preferred Investor Warrants also provide for adjustments to the exercise price and the number of shares issuable upon exercise in the event of certain rights offerings, distributions, or extraordinary dividends.
Forum Selection
The Certificate of Incorporation provides that (i) (a) any derivative action or proceeding brought on behalf of Presidio under Delaware law, (b) any action asserting a claim of breach of a fiduciary duty owed by any current or former director, officer, other employee or stockholder of Presidio to Presidio or Presidio’s stockholders, (c) any action asserting a claim arising pursuant to any provision of the DGCL, the Certificate of Incorporation or the Bylaws (as either may be amended or restated) or as to which the DGCL confers jurisdiction on the Court of Chancery of the State of Delaware, (d) any action asserting a claim governed by the internal affairs doctrine of the law of the State of Delaware, or (e) any other action asserting an “internal corporate claim,” as defined in the DGCL, to the fullest extent permitted by law, be exclusively brought in the Court of Chancery of the State of Delaware or, if such court does not have subject matter jurisdiction thereof, the federal district court of the State of Delaware; and (ii) the federal district courts of the United States shall be the exclusive forum for the resolution of any complaint asserting a cause of action arising under the Securities Act; provided, however, that the foregoing choice of forum provision shall not apply to claims seeking to enforce any liability or duty created by the Exchange Act, or any other claim for which the U.S. federal courts have exclusive jurisdiction. The Certificate of Incorporation also provides that, to the fullest extent permitted by law, any person or entity purchasing or otherwise acquiring or holding any interest in shares of our capital stock shall be deemed to have notice of and consented to the foregoing. By agreeing to this provision, however, stockholders are not deemed to have waived our compliance with the federal securities laws and the rules and regulations thereunder.
Dividends
Declaration and payment of any dividend are subject to the discretion of our board of directors. The timing and amount of any dividends will be dependent upon our business prospects, results of operations, financial condition, cash requirements and availability, debt repayment obligations, capital expenditure needs, contractual restrictions, covenants in the agreements governing our current and future indebtedness, industry trends, the provisions of Delaware law affecting the payment of distributions to stockholders and any other factors our board of directors may consider relevant. We currently intend to pay a dividend from available funds and future earnings on the Presidio Class A Common Stock. Because we are a holding company, our ability to pay cash dividends on the Presidio Class A Common Stock depends on our receipt of cash distributions from Prometheus Holdings and, through Prometheus Holdings, cash distributions and dividends from our other direct and indirect subsidiaries. Our ability to pay dividends may be restricted by the terms of any future credit agreement or any future debt or preferred equity securities of us or our subsidiaries. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations of Presidio Production Company — Liquidity and Capital Resources” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations of the Predecessor — Liquidity and Capital Resources.”
Anti-Takeover Provisions
The Certificate of Incorporation and the Bylaws contain provisions that may delay, defer or discourage another party from acquiring control of us. These provisions, which are summarized below, may discourage coercive takeover practices or inadequate takeover bids. These provisions are also designed to encourage persons seeking to acquire control of us to first negotiate with our board of directors, which we believe may result in an improvement of the terms of any such acquisition in favor of our stockholders. However, they also give our board of directors the power to discourage acquisitions that some stockholders may favor.
136
Authorized but Unissued Shares
The authorized but unissued shares of our common stock and our preferred stock are available for future issuance without stockholder approval, subject to any limitations imposed by the NYSE rules. These additional shares may be used for a variety of corporate finance transactions, acquisitions and employee benefit plans and, as described under “Certain Relationships and Related Person Transactions — Prometheus Holdings LLC Agreement,” funding of redemptions of Prometheus Holdings Common Units. The existence of authorized but unissued and unreserved common stock and preferred stock could make it more difficult or discourage an attempt to obtain control of us by means of a proxy contest, tender offer, merger or otherwise.
Classified Board of Directors
The Certificate of Incorporation provides that our board of directors is divided into three classes, with the classes as nearly equal in number as possible and each class serving three-year staggered terms. Directors may only be removed from our board of directors for cause by the affirmative vote of a majority of the shares entitled to vote. See “Management of Presidio — Composition of the Presidio Board.” These provisions may have the effect of deferring, delaying or discouraging hostile takeovers, or changes in control of us or our management.
Special Meetings of Stockholders; Action by Written Consent of Stockholders
The Bylaws provide that only the Chairperson of our board of directors, our chief executive officer or a majority of our board of directors may call special meetings of our stockholders. The Certificate of Incorporation provides that our stockholders may not take action by consent without a meeting, but may only take action at a meeting of stockholders. These provisions may delay the ability of our stockholders to force consideration of a proposal or for stockholders controlling a majority of our capital stock to take any action, including the removal of directors.
Advance Notice Requirements for Stockholder Proposals and Director Nominations
In addition, the Bylaws established an advance notice procedure for stockholder proposals to be brought before an annual meeting of stockholders, including proposed nominations of candidates for election to our board of directors. In order for any matter to be “properly brought” before a meeting, a stockholder must comply with advance notice and duration of ownership requirements and provide us with certain information. Stockholders at an annual meeting may only consider proposals or nominations specified in the notice of meeting or brought before the meeting by or at the direction of our board of directors or by a qualified stockholder of record on the record date for the meeting, who is entitled to vote at the meeting and who has delivered timely written notice in proper form to our secretary of the stockholder’s intention to bring such business before the meeting. These provisions could have the effect of delaying stockholder actions that are favored by the holders of a majority of our outstanding voting securities until the next stockholder meeting.
No Cumulative Voting
The DGCL provides that stockholders are not entitled to cumulate votes in the election of directors unless a corporation’s certificate of incorporation provides otherwise. The Certificate of Incorporation does not provide for cumulative voting.
Amendment of Certificate of Incorporation or Bylaws
The Delaware General Corporation Law provides generally that the affirmative vote of a majority of the shares entitled to vote on any matter is required to amend a corporation’s certificate of incorporation or bylaws, unless a corporation’s certificate of incorporation or bylaws, as the case may be, requires a greater percentage. The Certificate of Incorporation provides that the board of directors may adopt, amend, alter, or repeal our bylaws. In addition, the Certificate of Incorporation provides that the stockholders may not adopt, amend, alter or repeal our bylaws unless such action is approved, in addition to any other vote required by the Certificate of Incorporation, by the affirmative vote of the holders of at least a majority of the voting power of all of the then-outstanding shares of our capital stock entitled to vote thereon, voting together as a single class.
137
Section 203 of the DGCL
We have opted out of Section 203 of the DGCL. However, the Certificate of Incorporation contains provisions that are similar to Section 203. Specifically, the Certificate of Incorporation provides that, subject to certain exceptions, we will not be able to engage in a “business combination” with any “interested stockholder” for three years following the date that the person became an interested stockholder, unless the interested stockholder attained such status with the approval of our board of directors or unless the business combination is approved in a prescribed manner. A “business combination” includes, among other things, a merger or consolidation involving us and the “interested stockholder” and the sale of more than 10% of our assets. In general, an “interested stockholder” is any entity or person beneficially owning 15% or more of our outstanding voting stock and any entity or person affiliated with, or controlling or controlled by, such entity or person.
Limitations on Liability and Indemnification of Officers and Directors
The Certificate of Incorporation provides indemnification for our directors and officers to the fullest extent permitted by the Delaware General Corporation Law. We have entered into indemnification agreements with each of our directors and executive officers that may, in some cases, be broader than the specific indemnification provisions contained under Delaware law. In addition, as permitted by Delaware law, the Certificate of Incorporation includes provisions that eliminate the personal liability of our directors for monetary damages resulting from breaches of certain fiduciary duties as a director. The effect of this provision is to restrict our rights and the rights of our stockholders in derivative suits to recover monetary damages against a director for breach of fiduciary duties as a director.
These provisions may be held not to be enforceable for violations of the federal securities laws of the United States.
Dissenters’ Rights of Appraisal and Payment
Under the DGCL, with certain exceptions, our stockholders have appraisal rights in connection with a merger or consolidation of Presidio. Pursuant to the DGCL, stockholders who properly request and perfect appraisal rights in connection with such merger or consolidation will have the right to receive payment of the fair value of their shares as determined by the Delaware Court of Chancery.
Stockholders’ Derivative Actions
Under the DGCL, any of our stockholders may bring an action in our name to procure a judgment in our favor, also known as a derivative action, provided that the stockholder bringing the action is a holder of our shares at the time of the transaction to which the action relates or such stockholder’s stock thereafter devolved by operation of law.
Transfer Agent and Registrar
The transfer agent and registrar for our securities is Continental Stock Transfer & Trust Company.
Trading Symbol and Market
The Presidio Class A Common Stock and the Public Warrants are listed on the NYSE under the symbols “FTW” and “FTW WS,” respectively.
138
SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT
The following table sets forth information known to the Company as of September 18, 2026, regarding beneficial ownership of shares of voting securities of the Company, which consist of Presidio Class A Common Stock and Presidio Class B Common Stock, by:
| ● | each person known by the Company to be the beneficial owner of more than 5% of any class of the Company’s voting securities; |
| ● | each of the Company’s executive officers and directors; and |
| ● | all of the Company’s executive officers and directors as a group. |
Beneficial ownership is determined according to the rules of the SEC, which generally provide that a person has beneficial ownership of a security if he, she or it possesses sole or shared voting or investment power over that security, including options, warrants and certain other derivative securities that are currently exercisable or will become exercisable within 60 days. Shares subject to warrants that are currently exercisable or exercisable within 60 days of the Closing Date are considered outstanding and beneficially owned by the person holding such warrants for the purpose of computing the percentage ownership of that person but are not treated as outstanding for the purpose of computing the percentage ownership of any other person.
The beneficial ownership of Presidio Class A Common Stock is based on 29,825,480 shares of Presidio Class A Common Stock outstanding as of September 18, 2026. The beneficial ownership percentages set forth in the table below with respect to Presidio common stock do not take into account (i) the issuance of any shares (or options to acquire shares) under the Incentive Plan and (ii) the issuance of any shares upon the exercise of warrants to purchase up to a total of 11,666,571 shares of Presidio common stock outstanding (other than any warrants held by each such person named below).
Unless otherwise indicated and subject to community property laws and similar laws, the Company believes that all parties named in the table below have sole voting and investment power with respect to all shares of Presidio Class A Common Stock and Presidio Class B Common Stock beneficially owned by them.
| Presidio Class A Common Stock | Presidio Class B Common Stock | Presidio Combined Voting Power | ||||||||||||||||||||||
| Name of Beneficial Owners | Number | Percentage(1) | Number | Percentage | Number | Percentage | ||||||||||||||||||
| Five Percent Holders: | ||||||||||||||||||||||||
| EQV Ventures Sponsor LLC(2) | 7,820,292 | 26.4 | % | — | — | 7,820,292 | 25.0 | % | ||||||||||||||||
| NH Presidio Investments LLC(3) | 1,717,391 | 5.8 | % | 1,000,000 | 59.6 | % | 2,717,391 | 8.7 | % | |||||||||||||||
| Alyeska Master. Fund, L.P.(4) | 2,717,391 | 9.2 | % | — | — | 2,717,391 | 8.7 | % | ||||||||||||||||
| Directors and Executive Officers(5): | ||||||||||||||||||||||||
| William Ulrich | 1,157,068 | 3.9 | % | — | — | 1,157,068 | 3.7 | % | ||||||||||||||||
| Chris Hammack | 694,241 | 2.3 | % | — | — | 694,241 | 2.2 | % | ||||||||||||||||
| John Brawley | 140,353 | * | — | — | 140,353 | * | ||||||||||||||||||
| Brett Barnes | 462,827 | 1.6 | % | — | — | 462,827 | 1.5 | % | ||||||||||||||||
| Jerry Silvey(6) | — | — | — | — | — | — | ||||||||||||||||||
| Tyson Taylor(6) | — | — | — | — | — | — | ||||||||||||||||||
| Daniel C. Herz | — | — | — | — | — | — | ||||||||||||||||||
| Jerry Schretter | — | — | — | — | — | — | ||||||||||||||||||
| James E. Vallee | — | — | — | — | — | — | ||||||||||||||||||
| Ray N. Walker, Jr. | — | — | — | — | — | — | ||||||||||||||||||
| Jeffrey S. Serota | — | — | — | — | — | — | ||||||||||||||||||
| All directors and executive officers as a group (11 individuals) | 2,454,489 | 8.3 | % | — | — | 2,454,489 | 7.8 | % | ||||||||||||||||
| * | Less than 1%. |
139
| (1) | Based on 29,825,480 shares of Presidio Class A Common Stock issued and outstanding as of September 18, 2026. |
| (2) | Consists of (i) 7,686,960 shares of Presidio Class A Common Stock and (ii) 133,332 shares of Presidio Class A Common Stock underlying Presidio Warrants. Jerry Silvey, Jerome C. Silvey, Jr. and Tyson Taylor directly control the Sponsor as managers of the entity, and each of Jerry Silvey, Jerome C. Silvey, Jr. and Tyson Taylor disclaim any beneficial ownership of such securities except to the extent of their ultimate pecuniary interest. Each of Jerry Silvey and Tyson Taylor has a direct or indirect economic interest in the Sponsor which is approximately 37.65% and 16.41%, respectively, and each of them disclaims any beneficial ownership of any securities held by the Sponsor except to the extent of his ultimate pecuniary interest. The business address of EQV Ventures Sponsor LLC is 1090 Center Drive, Park City, UT 84098. |
| (3) | NH Presidio Investments LLC is majority-owned by various investment vehicles that are managed by MS Capital Partners Adviser Inc. and for which MS Energy Partners GP LP serves as general partner. Morgan Stanley is the ultimate parent of MS Capital Partners Adviser Inc. and MS Energy Partners GP LP. The business address of NH Presidio Investments LLC is 1633 Broadway New York, NY 10019. |
| (4) | Alyeska Investment Group, L.P., the investment manager of Alyeska Master Fund, L.P. (“Alyeska”), has voting and investment control of the shares held by Alyeska. Anand Parekh is the Chief Executive Officer of Alyeska Investment Group, L.P. and may be deemed to be the beneficial owner of such shares. Mr. Parekh, however, disclaims any beneficial ownership of the shares held by Alyeska. The registered address of Alyeska Master Fund, L.P. is at c/o Maples Corporate Services Limited, P.O. Box 309, Ugland House, South Church Street George Town, Grand Cayman, KY1-1104, Cayman Islands. Alyeska Investment Group, L.P. is located at 77 W. Wacker, Suite 700, Chicago IL 60601. |
| (5) | The business address of each of the following individuals is 500 W. 7th Street, Suite 1500, Fort Worth, Texas 76102. |
| (6) | Does not include any shares indirectly owned by this individual as a result of his role as a manager of the Sponsor or direct or indirect economic interest in the Sponsor, as applicable. |
140
SELLING SECURITYHOLDERS
This prospectus relates to the resale by the Selling Securityholders from time to time of up to 24,222,945 shares of Presidio Class A Common Stock and up to 133,332 Presidio Warrants. The shares of Presidio Class A Common Stock and Presidio Warrants being offered by the Selling Securityholders are those previously issued to the Selling Securityholders in connection with the Business Combination. We are registering the shares of Presidio Class A Common Stock and Presidio Warrants in order to permit the Selling Securityholders to offer the shares for resale from time to time. When we refer to the “Selling Securityholders” in this prospectus, we mean the persons listed in the table below, and the pledgees, donees, transferees, assignees, successors, designees and others who later come to hold any of the Selling Securityholders’ interest in the Presidio Class A Common Stock and Presidio Warrants other than through a public sale.
The table below lists the Selling Securityholders and other information regarding the beneficial ownership of the shares of Presidio Class A Common Stock and Presidio Warrants by each of the Selling Securityholders. The second column lists the number of shares of Presidio Class A Common Stock beneficially owned by each selling securityholder, based on its ownership of the shares of Presidio Class A Common Stock, as of September 18, 2026. The third column lists the shares of Presidio Class A Common Stock being offered by this prospectus by the Selling Securityholders. The fourth column assumes the sale of all of the shares offered by the Selling Securityholders pursuant to this prospectus but no other shares owned by the Selling Securityholders prior to this offering. The fifth column lists the number of Presidio Warrants beneficially owned by each Selling Securityholder as of September 18, 2026. The sixth column lists the Presidio Warrants being offered by this prospectus by the Selling Securityholders. The seventh column assumes the sale of the Presidio Warrants offered by the Selling Securityholders pursuant to this prospectus but no other warrants owned by the Selling Securityholder prior to this offering.
The Selling Securityholders may sell all, some or none of their shares in this offering. See “Plan of Distribution.” Unless otherwise indicated, the address of each selling securityholder named in the table below is 500 W. 7th Street Suite 1500 Fort Worth, Texas 76102.
| Name of Selling Securityholder | Number of Shares of Presidio Class A Common Stock Owned Prior to Offering | Maximum Number of Shares of Presidio Class A Common Stock to be Sold Pursuant to this Prospectus | Number of Shares of Presidio Class A Common Stock Owned After Offering | Number of Presidio Warrants Owned Prior to Offering | Maximum Number of Presidio Warrants to be Sold Pursuant to this Prospectus | Number of Presidio Warrants Owned After Offering | Percentage of Outstanding Presidio Class A Common Stock Owned After Offering | |||||||||||||||||||||
| Adage Capital Partners, L.P. (1) | 5,034,136 | 4,981,623 | 52,513 | 297,106 | - | 297,106 | * | |||||||||||||||||||||
| Alyeska Master Fund, L.P. (2) | 2,500,000 | 2,500,000 | - | - | - | - | - | |||||||||||||||||||||
| Andrew Peter Matthew Blakeman | 40,000 | 40,000 | - | - | - | - | - | |||||||||||||||||||||
| BP Energy Company (3) | 1,500,000 | 1,500,000 | - | - | - | - | - | |||||||||||||||||||||
| Brett J. Barnes (4) | 462,827 | 462,827 | - | - | - | - | - | |||||||||||||||||||||
| Bryan Summers | 40,000 | 40,000 | - | - | - | - | - | |||||||||||||||||||||
| Christopher L. Hammack (5) | 694,241 | 694,241 | - | - | - | - | - | |||||||||||||||||||||
| Black Fork River Trust (6) | - | 208,115 | - | - | - | - | - | |||||||||||||||||||||
| EQV Ventures Sponsor LLC (7) | 7,686,960 | 7,820,292 | - | 133,332 | 133,332 | - | - | |||||||||||||||||||||
| Ghisallo Master Fund LP (8) | 122,500 | 122,500 | - | - | - | - | - | |||||||||||||||||||||
| Jerome C. Silvey Jr. | 40,000 | 40,000 | - | - | - | - | - | |||||||||||||||||||||
| John Brawley (9) | 140,353 | 140,353 | - | - | - | - | - | |||||||||||||||||||||
| JPMorgan Core Plus Bond ETF (10) | - | 106,500 | - | - | - | - | - | |||||||||||||||||||||
| JPMorgan Core Plus Bond Fund (11) | - | 306,000 | - | - | - | - | - | |||||||||||||||||||||
| JPMorgan Income ETF (12) | - | 60,000 | - | - | - | - | - | |||||||||||||||||||||
| JPMorgan Income Fund (13) | - | 165,000 | - | - | - | - | - | |||||||||||||||||||||
| LF-HW, LLC (14) | 500,000 | 500,000 | - | - | - | - | - | |||||||||||||||||||||
| LuminArx Opportunistic Alternative Solutions Holdings II Fund LP (15) | 183,957 | 183,957 | - | - | - | - | - | |||||||||||||||||||||
| LuminArx Pavo Holdings II LP (16) | 66,043 | 66,043 | - | - | - | - | - | |||||||||||||||||||||
| Marcus Peperzak | 40,000 | 40,000 | - | - | - | - | - | |||||||||||||||||||||
| NH Presidio Investments LLC (17) | 1,717,391 | 2,717,391 | - | - | - | - | - | |||||||||||||||||||||
| Whitney Dana Hornak (18) | - | 1,618 | - | - | - | - | - | |||||||||||||||||||||
| William A. Ulrich (19) | 1,157,068 | 1,157,068 | - | - | - | - | - | |||||||||||||||||||||
| Penbryn LLC(20) | 278,917 | 278,917 | - | - | - | - | - | |||||||||||||||||||||
| Granite Arch Investments LLC(21) | 90,500 | 90,500 | - | - | - | - | - | |||||||||||||||||||||
| * | Less than 1%. |
| (1) | Consists of (i) 2,129,336 shares of Presidio Class A Common Stock held by the Selling Securityholder, (ii) 187,500 shares of Presidio Class A Common Stock issuable upon the exercise of Series A Preferred Investor Warrants held by the Selling Securityholder and (iii) 2,717,300 shares of Presidio Class A Common Stock issuable upon the conversion of the 27,173 shares of Series B Preferred Stock held by the Selling Securityholder. Bob Atchinson and Phillip Gross are the managing members of Adage Capital Advisors, L.L.C., which is the managing member of Adage Capital Partners GP, L.L.C., which is the general partner of Adage, and each such person or entity, as the case may be, has shared voting and/or investment power over the securities held by Adage Capital Partners, LP and may be deemed the beneficial owner of such shares, and each such person or entity, as the case may be, disclaims beneficial ownership of such securities except to the extent of their respective pecuniary interest therein. The business address of Adage Capital Partners, L.P. is 200 Clarendon Street, Floor 52, Boston, Massachusetts 02116-5021. |
141
| (2) | Alyeska Investment Group, L.P., the investment manager of Alyeska Master Fund, L.P. (“Alyeska”), has voting and investment control of the shares held by Alyeska. Anand Parekh is the Chief Executive Officer of Alyeska Investment Group, L.P. and may be deemed to be the beneficial owner of such shares. Mr. Parekh, however, disclaims any beneficial ownership of the shares held by Alyeska. The registered address of Alyeska Master Fund, L.P. is at c/o Maples Corporate Services Limited, P.O. Box 309, Ugland House, South Church Street George Town, Grand Cayman, KY1-1104, Cayman Islands. Alyeska Investment Group, L.P. is located at 77 W. Wacker, Suite 700, Chicago IL 60601. |
| (3) | BP Energy Company is an indirect, wholly owned subsidiary of BP p.l.c., a publicly traded company. The business address of BP Energy Company is 201 Helios Way, Houston, Texas 77079-2678. |
| (4) | Mr. Barnes is the Executive Vice President and General Counsel of Presidio. |
| (5) | Mr. Hammack is the Co-Chief Executive Officer of Presidio. |
| (6) | Consists of 208,115 shares of Presidio Class A Common Stock issuable upon the exchange of 208,115 Prometheus Holdings Common Units held by the Selling Security Holder. Colby D. Tiffee and Leigh Ann Cales serve as trustees of the Selling Securityholder and have voting and investment control over the shares. |
| (7) | Consists of (i) 7,686,960 shares of Presidio Class A Common Stock held by the Selling Securityholder, (ii) 133,332 shares of Presidio Class A Common Stock issuable upon the exercise of 133,332 Presidio Warrants held by the Selling Securityholder and (iii) 133,332 Presidio Warrants held by the Selling Securityholder. Jerry Silvey, Jerome C. Silvey, Jr. and Tyson Taylor directly control the Sponsor as managers of the entity, and each of Jerry Silvey, Jerome C. Silvey, Jr. and Tyson Taylor disclaim any beneficial ownership of such securities except to the extent of their ultimate pecuniary interest. Each of Jerry Silvey and Tyson Taylor has a direct or indirect economic interest in the Sponsor which is approximately 37.65% and 16.41%, respectively, and each of them disclaims any beneficial ownership of any securities held by the Sponsor except to the extent of his ultimate pecuniary interest. The business address of EQV Ventures Sponsor LLC is 1090 Center Drive, Park City, Utah 84098. |
| (8) | Consists of (i) 66,250 shares of Presidio Class A Common Stock held by the Selling Securityholder and (ii) 56,250 shares of Presidio Class A Common Stock issuable upon the exercise of Series A Preferred Investor Warrants held by the Selling Securityholder. Ghisallo Capital Management LLC (“Ghisallo Capital”) is the investment manager of Ghisallo Master Fund LP and has voting and investment control over the shares held by Ghisallo Master Fund LP. The securities held by Ghisallo Master Fund LP may be deemed to be beneficially owned by Ghisallo Capital and Michael Germino, the managing member of Ghisallo Capital. Mr. Germino disclaims beneficial ownership of such shares except to the extent of his pecuniary interest therein. The business address of Ghisallo Master Fund LP is 149 Newbury St., 2nd Floor, Boston, MA 02116. |
| (9) | Mr. Brawley is the Chief Financial Officer of Presidio. |
| (10) | Consists of 106,500 shares of Presidio Class A Common Stock issuable upon the exercise of Series A Preferred Investor Warrants held by JPMorgan Core Plus Bond ETF. JPMorgan Investment Management Inc. serves as the investment advisor to JPMorgan Core Plus Bond ETF and has voting and investment control over the shares held by JPMorgan Core Plus Bond ETF. The business address of JPMorgan Core Plus Bond ETF is 1111 Polaris Pkwy, Columbus, Ohio 43240. |
| (11) | Consists of 306,000 shares of Presidio Class A Common Stock issuable upon the exercise of Series A Preferred Investor Warrants held by JPMorgan Core Plus Bond Fund. JPMorgan Investment Management Inc. serves as the investment advisor to JPMorgan Core Plus Bond Fund and has voting and investment control over the shares held by JPMorgan Core Plus Bond Fund. The business address of JPMorgan Core Plus Bond Fund is 1111 Polaris Pkwy, Columbus, Ohio 43240. |
| (12) | Consists of 60,000 shares of Presidio Class A Common Stock issuable upon the exercise of Series A Preferred Investor Warrants held by JPMorgan Income ETF. JPMorgan Investment Management Inc. serves as the investment advisor to JPMorgan Income ETF and has voting and investment control over the shares held by JPMorgan Income ETF. The business address of JPMorgan Income ETF is 1111 Polaris Pkwy, Columbus, Ohio 43240. |
| (13) | Consists of 165,000 shares of Presidio Class A Common Stock issuable upon the exercise of Series A Preferred Investor Warrants held by JPMorgan Income Fund. JPMorgan Investment Management Inc. serves as the investment advisor to JPMorgan Income Fund and has voting and investment control over the shares held by JPMorgan Income Fund. The business address of JPMorgan Income Fund is 1111 Polaris Pkwy, Columbus, Ohio 43240. |
| (14) | Alec Litowtiz has voting and investment control over the shares held by LF-HW, LLC. The business address of LF-HW, LLC is 1001 Green Bay Road #317, Winnetka, IL 60093-1721. |
| (15) | LuminArx Opportunistic Alternative Solutions Holdings II Fund LP’s registered SEC investment advisor is LuminArx Capital Management LP. Gideon Berger, Chief Executive Officer, and Min Htoo, Chief Investment Officer, of LuminArx Capital Management LP exercise discretionary investment authority over LuminArx Opportunistic Alternative Solutions Holdings II Fund LP and share voting and investment power over its shares. The business address of LuminArx Opportunistic Alternative Solutions Holdings II Fund LP is 712 Fifth Avenue, 23rd Floor, New York, New York 10019. |
| (16) | LuminArx Pavo Holdings II LP’s registered SEC investment advisor is LuminArx Capital Management LP. Gideon Berger, Chief Executive Officer, and Min Htoo, Chief Investment Officer, of LuminArx Capital Management LP exercise discretionary investment authority over LuminArx Pavo Holdings II LP and share voting and investment power over its shares. The business address of LuminArx Pavo Holdings II LP is 712 Fifth Avenue, 23rd Floor, New York, New York 10019. |
| (17) | Consists of (i) 1,717,391 shares of Presidio Class A Common Stock held by the Selling Securityholder and (ii) 1,000,000 shares of Presidio Class A Common Stock issuable upon the exchange of 1,000,000 Prometheus Holdings Common Units held by the Selling Securityholder. NH Presidio Investments LLC is majority-owned by various investment vehicles that are managed by MS Capital Partners Adviser Inc. and for which MS Energy Partners GP LP serves as general partner. Morgan Stanley is the ultimate parent of MS Capital Partners Adviser Inc. and MS Energy Partners GP LP. The business address of NH Presidio Investments LLC is 1633 Broadway, New York, New York 10019. |
| (18) | Consists of 1,618 shares of Presidio Class A Common Stock issuable upon the exchange of 1,618 Prometheus Holdings Common Units held by the Selling Securityholder. |
| (19) | Mr. Ulrich is the Chairman and Co-Chief Executive Officer of Presidio. |
| (20) | Jerry Silvey has voting and investment control over the shares held by the Selling Securityholder. The business address of Penbryn LLC is 1887 Whitney Mesa Dr. #1748, Henderson, NV 89014. |
| (21) | Tyson Taylor is the managing member and has voting and investment control over the shares held by the Selling Securityholder. The business address of Granite Arch Investments LLC is 1677 W Royal Cir, Lehi UT 84043. |
142
PLAN OF DISTRIBUTION
Selling Securityholders
This prospectus includes the registration of the issuance by the Company of up to 11,887,403 shares of Presidio Class A Common Stock issuable upon exercise of the Presidio Warrants.
This prospectus also includes the registration for possible resale of 24,222,945 shares of Presidio Class A Common Stock issued in connection with the Business Combination.
The shares of Presidio Class A Common Stock offered for resale under this prospectus were issued to the Selling Securityholders (as applicable to each) in accordance with the terms of, and transactions contemplated by, the Business Combination Agreement and the EQVR Merger Agreement. The Presidio Class A Common Stock registered hereunder represents the securities issued to the Selling Securityholders pursuant to the terms of the Business Combination Agreement, as applicable to each Selling Securityholder, concurrently with the closing of the Business Combination. Additional information about any offering may be provided in a prospectus supplement that describes, among other things, the specific amounts and prices of the Presidio Class A Common Stock being offered and the terms of the offering.
As of the date of this prospectus, the Selling Securityholders have advised us that they do not currently have any plan of distribution. Unless the context otherwise requires, as used in this prospectus, “Selling Securityholders” includes the Selling Securityholders named in the table included in the section above entitled “Selling Securityholders” and donees, transferees, assignees, successors, designees and others who later come to hold any of the Selling Securityholders’ interest in the Presidio Class A Common Stock other than through a public sale.
We will not receive any of the proceeds from the sale of the securities by the Selling Securityholders. We will receive proceeds from Presidio Warrants and the Series A Preferred Investor Warrants exercised in the event that such warrants are exercised for cash.
The Selling Securityholders may offer and sell all or a portion of the securities covered by this prospectus from time to time, in one or more or any combination of the following transactions:
| ● | on the New York Stock Exchange, in the over-the-counter market or on any other national securities exchange on which our securities are listed or traded; |
| ● | directly to purchasers, including through a specific bidding, auction or other process or in privately negotiated transactions; |
| ● | in one or more underwritten transactions; |
| ● | in a block trade in which a broker-dealer will attempt to sell the offered securities as agent but may purchase and resell a portion of the block as principal to facilitate the transaction; |
| ● | through purchases by a broker-dealer as principal and resale by the broker-dealer for its account pursuant to this prospectus; |
| ● | in ordinary brokerage transactions and transactions in which the broker solicits purchasers; |
| ● | through the writing or settlement of options (including put or call options), or other hedging transactions, whether through an options exchange or otherwise; |
| ● | through the distribution of the securities by any selling securityholder to its partners, members or stockholders; |
| ● | agreements with broker dealers to sell a specified number of the securities at a stipulated price per share; |
| ● | in short sales entered into after the effective date of the registration statement of which this prospectus is a part; |
| ● | “at the market” or through market makers or into an existing market for the securities; |
143
| ● | through a combination of any of the above methods of sale; or |
| ● | any other method permitted pursuant to applicable law. |
In addition, a selling securityholder that is an entity may elect to make a pro rata in-kind distribution of securities to its members, partners or stockholders pursuant to the registration statement of which this prospectus is a part by delivering a prospectus with a plan of distribution. Such members, partners or stockholders would thereby receive freely tradeable securities pursuant to the distribution through a registration statement. To the extent a distributee is an affiliate of ours (or to the extent otherwise required by law), we may file a prospectus supplement in order to permit the distributees to use the prospectus to resell the securities acquired in the distribution.
The Selling Securityholders may sell the securities at prices then prevailing, related to the then prevailing market price or at negotiated prices. The offering price of the securities from time to time will be determined by us and by the Selling Securityholders and, at the time of the determination, may be higher or lower than the market price of our securities on the New York Stock Exchange or any other exchange or market.
The Selling Securityholders may also sell our securities short and deliver these securities to close out their short positions, or loan or pledge the securities to broker-dealers that in turn may sell these securities. The shares may be sold directly or through broker-dealers acting as principal or agent, or pursuant to a distribution by one or more underwriters on a firm commitment or best-efforts basis. The Selling Securityholders may also enter into hedging transactions with broker-dealers. In connection with such transactions, broker-dealers of other financial institutions may engage in short sales of our securities in the course of hedging the positions they assume with us and with the Selling Securityholders. The Selling Securityholders may also enter into options or other transactions with broker-dealers or other financial institutions which require the delivery to such broker-dealer or other financial institution of securities offered by this prospectus, which securities such broker-dealer or other financial institution may resell pursuant to this prospectus (as supplemented or amended to reflect such transaction).
The Selling Securityholders also may resell all or a portion of the securities in open market transactions in reliance upon Rule 144 under the Securities Act rather than pursuant to this prospectus, provided that they meet the criteria and conform to the requirements of that rule. In connection with an underwritten offering, underwriters or agents may receive compensation in the form of discounts, concessions or commissions from the Selling Securityholders or from purchasers of the offered securities for whom they may act as agents. In addition, underwriters may sell the securities to or through dealers, and those dealers may receive compensation in the form of discounts, concessions or commissions from the underwriters and/or commissions from the purchasers for whom they may act as agents. The Selling Securityholders and any underwriters, dealers or agents participating in a distribution of the securities may be deemed to be “underwriters” within the meaning of the Securities Act, and any profit on the sale of the securities by the Selling Securityholders and any commissions received by broker-dealers may be deemed to be underwriting commissions under the Securities Act.
The Selling Securityholders may agree to indemnify an underwriter, broker-dealer or agent against certain liabilities related to the sale of the securities, including liabilities under the Securities Act. The Selling Securityholders have advised us that they have not entered into any agreements, understandings or arrangements with any underwriters or broker-dealers regarding the sale of their securities. Upon our notification by a selling securityholder that any material arrangement has been entered into with an underwriter or broker-dealer for the sale of securities through a block trade, special offering, exchange distribution, secondary distribution or a purchase by an underwriter or broker-dealer, we will file a supplement to this prospectus, if required, pursuant to Rule 424(b) under the Securities Act, disclosing certain material information, including:
| ● | the name of the selling securityholder; |
| ● | the number of securities being offered; |
| ● | the terms of the offering; |
| ● | the names of the participating underwriters, broker-dealers or agents; |
144
| ● | any discounts, commissions or other compensation paid to underwriters or broker-dealers and any discounts, commissions or concessions allowed or reallowed or paid by any underwriters to dealers; |
| ● | the public offering price; and other material terms of the offering. |
In addition, upon being notified by a selling securityholder that a donee, pledgee, transferee or other successor-in-interest intends to sell securities, we will, to the extent required, promptly file a supplement to this prospectus to name specifically such person as a selling securityholder.
The Selling Securityholders are subject to the applicable provisions of the Exchange Act and the rules and regulations under the Exchange Act, including Regulation M. This regulation may limit the timing of purchases and sales of any of the securities offered in this prospectus by the Selling Securityholders. The anti-manipulation rules under the Exchange Act may apply to sales of securities in the market and to activities of the Selling Securityholders and their affiliates. Furthermore, Regulation M may restrict the ability of any person engaged in the distribution of the securities to engage in market-making activities for the particular securities being distributed for a period of up to five business days before the distribution. The restrictions may affect the marketability of the securities and the ability of any person or entity to engage in market-making activities for the securities.
In compliance with guidelines of the Financial Industry Regulatory Authority (“FINRA”), the maximum compensation or discount to be received by any FINRA member or independent broker or dealer may not exceed 8% of the aggregate amount of securities offered pursuant to this prospectus.
To the extent required, this prospectus may be amended and/or supplemented from time to time to describe a specific plan of distribution. Instead of selling the securities under this prospectus, the Selling Securityholders may sell the securities in compliance with the provisions of Rule 144 under the Securities Act, if available, or pursuant to other available exemptions from the registration requirements of the Securities Act.
A holder of Presidio Warrants or Series A Preferred Investor Warrants may exercise its warrants in accordance with the Presidio Warrant Agreement, for the Presidio Warrants, or the terms of the Series A Preferred Investor Warrants, for the Series A Preferred Investor Warrants, on or before the expiration date set forth therein by surrendering, at the office of the warrant agent, Continental Stock Transfer & Trust Company, the certificate evidencing such Presidio Warrants or Series A Preferred Investor Warrants, with the form of election to purchase set forth thereon, properly completed and duly executed, accompanied by full payment of the exercise price and any and all applicable taxes due in connection with the exercise of the Presidio Warrants or the Series A Preferred Investor Warrants, subject to any applicable provisions relating to cashless exercises in accordance with the Presidio Warrant Agreement or the terms of the Series A Preferred Investor Warrants, as applicable.
145
SECURITIES ACT RESTRICTIONS ON RESALE OF PRESIDIO SECURITIES
Pursuant to Rule 144 under the Securities Act (“Rule 144”), a person who has beneficially owned restricted Presidio Class A Common Stock or Presidio Warrants for at least six months would be entitled to sell their securities provided that (i) such person is not deemed to have been an affiliate of Presidio at the time of, or at any time during the three months preceding, a sale and (ii) Presidio is subject to the Exchange Act periodic reporting requirements for at least three months before the sale and have filed all required reports under Section 13 or 15(d) of the Exchange Act during the twelve months preceding the sale.
Persons who have beneficially owned restricted shares of Presidio Class A Common Stock or Presidio Warrants for at least six months but who are affiliates of Presidio at the time of, or at any time during the three months preceding, a sale, would be subject to additional restrictions, by which such person would be entitled to sell within any three-month period only a number of securities that does not exceed the greater of:
| ● | 1% of the total number of Presidio Class A Common Stock then outstanding; or |
| ● | the average weekly reported trading volume of Presidio Common Stock during the four calendar weeks preceding the filing of a notice on Form 144 with respect to the sale. |
Sales by affiliates of Presidio under Rule 144 are also limited by manner of sale provisions and notice requirements and to the availability of current public information about Presidio.
Restrictions on the Use of Rule 144 by Shell Companies or Former Shell Companies
Rule 144 is not available for the resale of securities initially issued by shell companies (other than business combination related shell companies) or issuers that have been at any time previously a shell company. However, Rule 144 also includes an important exception to this prohibition if the following conditions are met:
| ● | the issuer of the securities that was formerly a shell company has ceased to be a shell company; |
| ● | the issuer of the securities is subject to the reporting requirements of Section 13 or 15(d) of the Exchange Act; |
| ● | the issuer of the securities has filed all Exchange Act reports and material required to be filed, as applicable, during the preceding twelve months (or such shorter period that the issuer was required to file such reports and materials), other than Form 8-K reports; and |
| ● | at least one year has elapsed from the time that the issuer filed current Form 10 type information with the SEC reflecting its status as an entity that is not a shell company. |
Following the completion of the Business Combination, Presidio is no longer a shell company and so, once and for as long as the conditions set forth above are satisfied, Rule 144 will become available for the resale of the above noted restricted securities.
146
MATERIAL U.S. FEDERAL INCOME TAX CONSIDERATIONS
The following discussion is a summary of the U.S. federal income tax considerations generally applicable to the ownership and disposition of shares of Presidio Class A Common Stock and Presidio Warrants, which we refer to collectively as our securities. This summary is based upon provisions of the United States Internal Revenue Code of 1986, as amended (the “Code”), United States Treasury regulations promulgated thereunder, rulings, judicial decisions, published positions of the Internal Revenue Service (the “IRS”) and other applicable authorities, as of the date hereof. Those authorities are subject to different interpretations and may be changed, perhaps retroactively, so as to result in United States federal income tax consequences different from those summarized below. This summary does not discuss all aspects of U.S. federal income taxation that may be important to particular investors in light of their individual circumstances, including investors subject to special tax rules (e.g., financial institutions, insurance companies, traders or broker-dealers, tax-exempt organizations (including private foundations), governmental organizations, foreign pension funds, tax qualified retirement plans, taxpayers that have elected mark-to-market accounting, accrual-method taxpayers subject to special tax accounting rules under Section 451(b) of the Code, persons subject to the alternative minimum tax, partnerships or other pass-through entities for United States federal income tax purposes (or an investor in such pass-through entities), S corporations, regulated investment companies, real estate investment trusts, passive foreign investment companies, controlled foreign corporations, investors that will hold our securities as part of a straddle, hedge, conversion, or other integrated transaction for U.S. federal income tax purposes, former citizens or long-term residents of the United States or U.S. Holders (as defined below) that have a functional currency other than the U.S. dollar), all of whom may be subject to tax rules that differ materially from those summarized below. In addition, this summary does not discuss other U.S. federal tax consequences (e.g., estate or gift tax), any state, local, or non-U.S. tax considerations or the Medicare tax or alternative minimum tax. In addition, this summary is limited to investors that will hold our securities as “capital assets” (generally, property held for investment) under the Code. No ruling from the IRS has been or will be sought regarding any matter discussed herein. No assurance can be given that the IRS would not assert, or that a court would not sustain a position contrary to any of the tax aspects set forth below.
For purposes of this summary, a “U.S. Holder” is a beneficial holder of securities who or that, for U.S. federal income tax purposes is:
| ● | an individual who is a United States citizen or resident of the United States; |
| ● | a corporation created in, or organized under the law of, the United States or any state or political subdivision thereof; |
| ● | an estate the income of which is includible in gross income for United States federal income tax purposes regardless of its source; or |
| ● | a trust (A) the administration of which is subject to the primary supervision of a United States court and which has one or more United States persons (within the meaning of the Code) who have the authority to control all substantial decisions of the trust or (B) that has in effect a valid election under applicable Treasury regulations to be treated as a United States person. |
A “non-U.S. Holder” is a beneficial holder of securities that is neither a U.S. Holder nor a partnership for U.S. federal income tax purposes.
If a partnership (including an entity or arrangement treated as a partnership for U.S. federal income tax purposes) holds our securities, the tax treatment of a partner, member or other beneficial owner in such partnership will generally depend upon the status of the partner, member or other beneficial owner, the activities of the partnership and certain determinations made at the partner, member or other beneficial owner level. If you are a partner, member or other beneficial owner of a partnership holding our securities, you are urged to consult your tax advisor regarding the tax consequences of the ownership and disposition of our securities.
THIS DISCUSSION OF U.S. FEDERAL INCOME TAX CONSIDERATIONS IS FOR GENERAL INFORMATION PURPOSES ONLY AND IS NOT TAX ADVICE. PROSPECTIVE HOLDERS SHOULD CONSULT THEIR TAX ADVISORS CONCERNING THE U.S. FEDERAL INCOME TAX CONSEQUENCES TO THEM OF OWNING AND DISPOSING OF OUR SECURITIES, AS WELL AS THE APPLICATION OF ANY, STATE, LOCAL AND NON-U.S. INCOME, ESTATE AND OTHER TAX CONSIDERATIONS. IN ADDITION, PROSPECTIVE HOLDERS SHOULD CONSULT WITH THEIR TAX ADVISORS WITH RESPECT TO POTENTIAL CHANGES IN UNITED STATES FEDERAL TAX LAW AS WELL AS POTENTIAL CHANGES IN STATE, LOCAL OR NON-U.S. TAX LAWS.
U.S. Holders
Taxation of Distributions
If we pay distributions to U.S. Holders of shares of Presidio Class A Common Stock, such distributions will constitute dividends for U.S. federal income tax purposes to the extent paid from our current or accumulated earnings and profits, as determined under U.S. federal income tax principles. Distributions in excess of current and accumulated earnings and profits will constitute a return of capital that will be applied against and reduce (but not below zero) the U.S. Holder’s adjusted tax basis in its shares of Presidio Class A Common Stock. Any remaining excess will be treated as gain realized on the sale or other disposition of the Presidio Class A Common Stock and will be treated as described under the section of this prospectus entitled “— U.S. Holders — Gain or Loss on Sale, Taxable Exchange or Other Taxable Disposition of Presidio Class A Common Stock or Presidio Warrants” below.
147
Dividends we pay to a U.S. Holder that is a taxable corporation generally will qualify for the dividends received deduction if the requisite holding period is satisfied. With certain exceptions (including dividends treated as investment income for purposes of investment interest deduction limitations), and provided certain holding period requirements are met, dividends we pay to a non-corporate U.S. Holder will generally constitute “qualified dividends” that will be subject to tax at the maximum tax rate accorded to long-term capital gains.
Gain or Loss on Sale, Taxable Exchange or Other Taxable Disposition of Presidio Class A Common Stock or Presidio Warrants
A U.S. Holder will recognize gain or loss on the sale, taxable exchange (other than by exercise) or other taxable disposition of shares of Presidio Class A Common Stock or Presidio Warrants. Any such gain or loss will be capital gain or loss and will be long-term capital gain or loss if the U.S. Holder’s holding period for the shares of Presidio Class A Common Stock or Presidio Warrants so disposed of exceeds one year. The amount of gain or loss recognized will generally be equal to the difference between (1) the sum of the amount of cash and the fair market value of any property received in such disposition and (2) the U.S. Holder’s adjusted tax basis in its shares of Presidio Class A Common Stock or Presidio Warrants so disposed of. A U.S. Holder’s adjusted tax basis in its shares of Presidio Class A Common Stock will generally equal the U.S. Holder’s acquisition cost of such shares of Presidio Class A Common Stock, reduced by any prior distributions treated as a return of capital as described under “— U.S. Holders — Taxation of Distributions” above. A U.S. Holder’s adjusted tax basis in its Presidio Warrants generally will equal the U.S. Holder’s acquisition cost of such Presidio Warrants, increased by any constructive distributions treated as dividends as described under “— U.S. Holders – Constructive Distributions” below. The deductibility of capital losses is subject to limitations.
Exercise or Lapse of a Presidio Warrant
Except as discussed below with respect to the cashless exercise of a Presidio Warrant, a U.S. Holder generally will not recognize gain or loss upon the acquisition Presidio Class A Common Stock on the exercise of a Presidio Warrant for cash. The U.S. Holder’s tax basis in the share of Presidio Class A Common Stock received upon exercise of a Presidio Warrant generally will be an amount equal to the sum of the U.S. Holder’s adjusted tax basis in the Presidio Warrant and the exercise price of such Presidio Warrant. It is unclear whether a U.S. Holder’s holding period for the Presidio Class A Common Stock will commence on the date of exercise of the Presidio Warrant or the day following the date of exercise of the Presidio Warrant; in either case, the holding period will not include the period during which the U.S. Holder held the Presidio Warrant. If a Presidio Warrant is allowed to lapse unexercised, a U.S. Holder generally will recognize a capital loss equal to such holder’s adjusted tax basis in the Presidio Warrant.
The tax consequences of a cashless exercise of a Presidio Warrant are not clear under current law. A cashless exercise may not be taxable, either because the exercise is not a realization event or because the exercise is treated as a “recapitalization” for U.S. federal income tax purposes. In either situation, a U.S. Holder’s tax basis in the Presidio Class A Common Stock received upon such cashless exercise generally should equal the U.S. Holder’s adjusted tax basis in the Presidio Warrants so exercised. If the cashless exercise is not a realization event, it is unclear whether a U.S. Holder’s holding period for the Presidio Class A Common Stock will commence on the date of exercise of the Presidio Warrant or the day following the date of exercise of the Presidio Warrant; in either case, the holding period will not include the period during which the U.S. Holder held the Presidio warrant. If the cashless exercise were treated as a recapitalization, the holding period of the Presidio Class A Common Stock should include the holding period of the Presidio Warrants so exercised.
It is also possible that a cashless exercise may be treated in part as a taxable exchange in which gain or loss would be recognized. In such event, a U.S. Holder may be deemed to have surrendered a number of Presidio Warrants having a value equal to the exercise price for the total number of Presidio Warrants to be exercised. The U.S. Holder would recognize capital gain or loss in an amount equal to the difference between the fair market value of Presidio Warrants deemed surrendered and the U.S. Holder’s adjusted tax basis in Presidio Warrants deemed surrendered. In this case, a U.S. Holder’s tax basis in the Presidio Class A Common Stock received would equal the sum of the U.S. Holder’s adjusted tax basis in Presidio Warrants exercised and the exercise price of such Presidio Warrants. It is unclear whether a U.S. Holder’s holding period for the Presidio Class A Common Stock would commence on the date of exercise of the Presidio Warrants or the day following the date of exercise of the Presidio Warrant; in either case, the holding period would not include the period during which the U.S. Holder held the Presidio Warrants so exercised.
Due to the absence of authority on the U.S. federal income tax treatment of a cashless exercise, there can be no assurance which, if any, of the alternative tax consequences and holding periods described above would be adopted by the IRS or a court of law. Accordingly, a U.S. Holder should consult its own tax advisor regarding the tax consequences of a cashless exercise.
Constructive Distributions
The terms of each Presidio Warrant provide for an adjustment to the number of units of Presidio Class A Common Stock for which the Presidio Warrant may be exercised or to the exercise price of the Presidio Warrant in certain events. An adjustment which has the effect of preventing dilution generally is not taxable. The U.S. Holders of the Presidio Warrants would, however, be treated as receiving a constructive distribution from us if, for example, the adjustment increases the U.S. Holders’ proportionate interest in our assets or earnings and profits (e.g., through an increase in the number of shares of Presidio Class A Common Stock that would be obtained upon exercise or through a decrease to the exercise price). Such constructive distribution would be subject to tax as described under “— U.S. Holders — Taxation of Distributions” in the same manner as if the U.S. Holders of the Presidio Warrants received a cash distribution from us equal to the fair market value of such increased interest. Generally, a U.S. Holder’s adjusted tax basis in its Presidio Warrants would be increased to the extent any such constructive distribution is treated as a dividend.
148
Non-U.S. Holders
Taxation of Distributions
Subject to the discussions below regarding the Foreign Account Tax Compliance Act and backup withholding, in general, any distributions (including constructive distributions, as described under “— U.S. Holders — Constructive Distributions” above) we make to a non-U.S. Holder of shares of Presidio Class A Common Stock or Presidio Warrants, to the extent paid out of our current or accumulated earnings and profits (as determined under U.S. federal income tax principles), will constitute dividends for U.S. federal income tax purposes and, provided such dividends are not effectively connected with the non-U.S. Holder’s conduct of a trade or business within the United States (or if a tax treaty applies are attributable to a U.S. permanent establishment or fixed base maintained by the non-U.S. Holder), we will be required to withhold tax from the gross amount of the dividend at a rate of 30%, unless such non-U.S. Holder is eligible for a reduced rate of withholding tax under an applicable income tax treaty and provides proper certification of its eligibility for such reduced rate (usually on an IRS Form W-8BEN or W-8BEN-E, as applicable). In the case of any constructive dividend, it is possible that this tax would be withheld from any amount owed to a non-U.S. Holder by the applicable withholding agent, including cash distributions on other property or sale proceeds from Presidio Warrants or other property subsequently paid or credited to such holder. Any distribution not constituting a dividend paid to non-U.S. Holders of Presidio Class A Common Stock will be treated first as reducing (but not below zero) the non-U.S. Holder’s adjusted tax basis in its shares of Presidio Class A Common Stock and, to the extent such distribution exceeds the non-U.S. Holder’s adjusted tax basis, as gain realized from the sale or other disposition of the shares of Presidio Class A Common Stock, which will be treated as described under the section of this prospectus entitled “— Non-U.S. Holders — Gain on Sale, Taxable Exchange or Other Taxable Disposition of Presidio Class A Common Stock and Presidio Warrants” below.
Dividends we pay to a non-U.S. Holder that are effectively connected with such non-U.S. Holder’s conduct of a trade or business within the United States (or if a tax treaty applies are attributable to a U.S. permanent establishment or fixed base maintained by the non-U.S. Holder) will generally not be subject to U.S. withholding tax, provided such non-U.S. Holder complies with certain certification and disclosure requirements (usually by providing an IRS Form W-8ECI). Instead, such dividends will generally be subject to U.S. federal income tax, net of certain deductions, at the same graduated individual or corporate rates applicable to U.S. Holders. If the non-U.S. Holder is a corporation, dividends that are effectively connected income may also be subject to a “branch profits tax” at a rate of 30% (or such lower rate as may be specified by an applicable income tax treaty).
Gain on Sale, Exchange or Other Taxable Disposition of Presidio Class A Common Stock
Subject to the discussions below regarding the Foreign Account Tax Compliance Act (“FATCA”) and backup withholding, a non-U.S. Holder will generally not be subject to U.S. federal income or withholding tax in respect of gain recognized on a sale, taxable exchange or other taxable disposition of shares of Presidio Class A Common Stock or Presidio Warrants unless:
| ● | the gain is effectively connected with the conduct of a trade or business by the non-U.S. Holder within the United States (and, if an applicable tax treaty so requires, is attributable to a U.S. permanent establishment or fixed base maintained by the non-U.S. Holder); |
| ● | the non-U.S. Holder is an individual who is present in the United States for 183 days or more in the taxable year of disposition and certain other conditions are met; or |
| ● | we are or have been a “United States real property holding corporation” for U.S. federal income tax purposes at any time during the shorter of the five-year period preceding such disposition and such non-U.S. Holder’s holding period. |
Gain described in the first bullet point above will be subject to tax at generally applicable U.S. federal income tax rates. Any gains described in the first bullet point above of a non-U.S. Holder that is a foreign corporation may also be subject to an additional “branch profits tax” at a 30% rate (or lower applicable treaty rate). Gain described in the second bullet point above will generally be subject to a flat 30% U.S. federal income tax. Non-U.S. Holders are urged to consult their tax advisors regarding possible eligibility for benefits under income tax treaties.
If the third bullet above applies to a non-U.S. Holder, subject to certain exceptions in the case of interests that are regularly traded on an established securities market as described below, gain recognized by such non-U.S. Holder on the sale, exchange or other disposition of Presidio Class A Common Stock or Presidio Warrants will be subject to tax at generally applicable U.S. federal income tax rates. We will be classified as a United States real property holding corporation if the fair market value of our “United States real property interests” equals or exceeds 50% of the sum of the fair market value of our worldwide real property interests plus our other assets used or held for use in a trade or business, as determined for U.S. federal income tax purposes. We believe we currently are a United States real property holding corporation, and we do not expect that to change in the foreseeable future. However, such determination is factual and in nature and subject to change and no assurance can be provided as to whether we will be a U.S. real property holding corporation at any future time. Further, even if we are a United States real property holding corporation, gain arising from the sale or other taxable disposition of shares of Presidio Class A Common Stock by a non-U.S. Holder will not be subject to U.S. federal income tax if Presidio Class A Common Stock is “regularly traded,” as defined by applicable Treasury Regulations, on an established securities market, and such non-U.S. Holder owned, actually and constructively, 5% or less of Presidio Class A Common Stock throughout the shorter of the five-year period ending on the date of the sale or other taxable disposition or the non-U.S. Holder’s holding period. If Presidio Class A Common Stock ceases to be regularly traded on an established securities market, all non-U.S. Holders would be subject to U.S. federal income tax on a sale or other taxable disposition of shares of Presidio Class A Common Stock, and a purchaser may be required to withhold and remit to the IRS 15% of the purchase price, unless an exception applies. Non-U.S. Holders are urged to consult their tax advisors regarding the application of these rules.
149
Exercise or Lapse of a Presidio Warrant
The U.S. federal income tax treatment of a non-U.S. Holder’s exercise of a Presidio Warrant, or the lapse of a Presidio Warrant held by a non-U.S. Holder, generally will correspond to the U.S. federal income tax treatment of the exercise or lapse of a warrant held by a U.S. Holder, as described above under “— U.S. Holders — Exercise or Lapse of a Presidio Warrant,” although to the extent a cashless exercise results in a taxable exchange, the consequences would be similar to those described under “— Non-U.S. Holders — Gain on Sale, Exchange or Other Taxable Disposition of Presidio Class A Common Stock or Presidio Warrants” above.
Non-U.S. Holders should consult their tax advisors regarding the U.S. federal income tax consequences to them in respect of any exercise or lapse of a Presidio Warrant.
Constructive Distributions
The terms of each Presidio Warrant provide for an adjustment to the exercise price of Presidio Warrant or an increase in the shares of Presidio Class A Common Stock issuable on exercise in certain circumstances. As described above under “U.S. Holders - Constructive Distributions,” certain adjustments with respect to Presidio Warrants can give rise to a constructive distribution. Any constructive distribution received by a non-U.S. Holder would be subject to U.S. federal income tax (including any applicable withholding) in the same manner as if such non-U.S. Holder received a cash distribution from us equal to the fair market value of such increased interest. If withholding applies to any constructive distribution received by a non-U.S. Holder, it is possible that the tax would be withheld from any amount paid to or held on behalf of the non-U.S. Holder by the applicable withholding agent. The rules governing constructive distributions as a result of certain adjustments with respect to a Presidio Warrant are complex, and non-U.S. Holders are urged to consult their tax advisors on the tax consequences any such constructive distribution with respect to a Presidio Warrant.
Information Reporting and Backup Withholding
Dividend payments with respect to our securities and proceeds from the sale, exchange or other taxable disposition of our securities may be subject to information reporting to the IRS and possible United States backup withholding. Backup withholding will not apply, however, to a U.S. Holder who furnishes a correct taxpayer identification number and makes other required certifications, or who is otherwise exempt from backup withholding and establishes such exempt status. A non-U.S. Holder generally will eliminate the requirement for information reporting and backup withholding by providing certification of its foreign status, under penalties of perjury, on a duly executed applicable IRS Form W-8 or by otherwise establishing an exemption.
Backup withholding is not an additional tax. Amounts withheld as backup withholding may be credited against a holder’s U.S. federal income tax liability, and a holder generally may obtain a refund of any excess amounts withheld under the backup withholding rules by timely filing the appropriate claim for refund with the IRS and furnishing any required information.
FATCA Withholding Taxes
Sections 1471 through 1474 of the Code and the Treasury Regulations and administrative guidance promulgated thereunder (commonly referred to as the “Foreign Account Tax Compliance Act” or “FATCA”) generally impose withholding at a rate of 30% in certain circumstances on dividends in respect of, and (subject to the proposed Treasury Regulations discussed below) gross proceeds from the sale or other disposition of, securities (including our securities) which are held by or through certain foreign financial institutions (including investment funds), unless any such institution (i) enters into, and complies with, an agreement with the IRS to report, on an annual basis, information with respect to interests in, and accounts maintained by, the institution that are owned by certain U.S. persons and by certain non-U.S. entities that are wholly or partially owned by U.S. persons and to withhold on certain payments, or (ii) if required under an intergovernmental agreement between the U.S. and an applicable foreign country, reports such information to its local tax authority, which will exchange such information with the U.S. authorities. An intergovernmental agreement between the U.S. and an applicable foreign country may modify these requirements. Accordingly, the entity through which our securities are held will affect the determination of whether such withholding is required. Similarly, dividends in respect of, and (subject to the proposed Treasury Regulations discussed below) gross proceeds from the sale or other disposition of, our securities held by an investor that is a non-financial non-U.S. entity that does not qualify under certain exceptions will generally be subject to withholding at a rate of 30%, unless such entity either (i) certifies to the applicable withholding agent that such entity does not have any “substantial U.S. owners” or (ii) provides certain information regarding the entity’s “substantial U.S. owners,” which will in turn be provided to the U.S. Department of Treasury.
Under the applicable Treasury Regulations and administrative guidance, withholding under FATCA generally applies to payments of dividends in respect of our securities. While withholding under FATCA generally would also apply to payments of gross proceeds from the sale or other disposition of securities (including our securities), proposed Treasury Regulations eliminate FATCA withholding on payments of gross proceeds entirely. Taxpayers generally may rely on these proposed Treasury Regulations until final Treasury Regulations are issued. All holders should consult their tax advisors regarding the possible implications of FATCA on their investment in our securities.
150
SHAREHOLDER COMMUNICATIONS
Shareholders and interested parties may communicate with the Presidio Board, any committee chairperson or the non-management directors as a group by writing to the board or committee chairperson in care of Presidio Production Company, 500 W. 7th Street, Suite 1500, Fort Worth, Texas 76102, Attention: Investor Relations. Each communication will be forwarded, depending on the subject matter, to the board of directors, the appropriate committee chairperson or all non-management directors.
LEGAL MATTERS
Sidley Austin LLP, Houston, Texas has passed upon the validity of the securities of Presidio Production Company offered in this prospectus and certain other legal matters related to this prospectus.
EXPERTS
The audited consolidated financial statements of Presidio Investment Holdings LLC included in this prospectus and elsewhere in the registration statement have been so included in reliance upon the report of Grant Thornton LLP, independent registered public accountants, upon the authority of said firm as experts in accounting and auditing.
The estimates of total proved reserves and forecasts of economics attributable to Presidio Investment Holdings LLC ownership interests as of December 31, 2025, included in this prospectus were based upon a reserve report prepared by independent petroleum engineers, Cawley, Gillespie & Associates, Inc. We have included these estimates in reliance on the authority of such firm as an expert in such matters.
The audited financial statements of EQV Resources LLC as of and for the years ended December 31, 2025 and 2024 have been included in reliance upon the report of Weaver and Tidwell, L.L.P., independent auditors, upon the authority of said firm as experts in accounting and auditing.
The estimates of total proved reserves and forecasts of economics attributable to EQV Resources LLC ownership interests as of December 31, 2025, were based upon a reserve report prepared by independent petroleum engineers, Cawley, Gillespie & Associates, Inc. We have included these estimates in reliance on the authority of such firm as an expert in such matters.
The estimates of total proved reserves and forecasts of economics attributable to the Arkoma Acquired Properties as of December 31, 2025 and 2024, were based upon a reserve report prepared by independent petroleum engineers, Pinnacle Energy Services, LLC. We have included these estimates in reliance on the authority of such firm as an expert in such matters.
The audited combined statement of revenues and direct operating expenses of the Arkoma Acquired Properties included in this prospectus and elsewhere in the registration statement have been so included upon the report of Grant Thornton LLP, independent certified public accountants, upon the authority of said firm as experts in accounting and auditing.
WHERE YOU CAN FIND MORE INFORMATION; INCORPORATION BY REFERENCE
Presidio files reports, proxy statements and other information with the SEC as required by the Exchange Act. Such reports, proxy statements and other information contain business and financial information about Presidio that is not included in this prospectus and is incorporated by reference herein. You may access information on Presidio at the SEC website containing reports, proxy statements and other information at: http://www.sec.gov. Those filings are also available free of charge to the public on, or accessible through, Presidio’s corporate website at https://bypresidio.com/. Presidio’s website and the information contained on, or that can be accessed through, the website is not deemed to be incorporated by reference in, and is not considered part of, this prospectus.
Information and statements contained in this prospectus are qualified in all respects by reference to the copy of the relevant contract filed as an exhibit to the registration statement of which this prospectus forms a part, which includes exhibits incorporated by reference from other filings made with the SEC.
151
INDEX TO FINANCIAL STATEMENTS
PRESIDIO PRODUCTION COMPANY
PRESIDIO INVESTMENT HOLDINGS LLC
EQV RESOURCES LLC
ARKOMA ACQUIRED PROPERTIES
F-1
PRESIDIO PRODUCTION COMPANY
Condensed Consolidated Balance Sheets (Unaudited)
(in thousands, except par values and share data)
| Successor | Predecessor | |||||||
| June 30, | December 31, | |||||||
| 2026 | 2025 | |||||||
| ASSETS | ||||||||
| Current assets: | ||||||||
| Cash and cash equivalents | $ | $ | ||||||
| Restricted cash | ||||||||
| Accounts receivable, oil and gas | ||||||||
| Accounts receivable, joint interest owners | ||||||||
| Derivative assets - current | ||||||||
| Hedge receivable | ||||||||
| Prepaid expenses and other current assets | ||||||||
| Total current assets | ||||||||
| Oil and natural gas properties, successful efforts | ||||||||
| Less accumulated depletion, depreciation, and amortization | ( | ) | ( | ) | ||||
| Total oil and natural gas properties, net | ||||||||
| Other property and equipment, net | ||||||||
| Derivative assets - noncurrent | ||||||||
| Right-of-use assets | ||||||||
| Deferred tax assets - noncurrent | ||||||||
| Other noncurrent assets | ||||||||
| Total assets | $ | $ | ||||||
| LIABILITIES, REDEEMABLE PREFERRED STOCK, AND STOCKHOLDERS’ EQUITY / MEMBERS’ DEFICIT | ||||||||
| Current liabilities: | ||||||||
| Accounts payable | $ | $ | ||||||
| Production taxes payable | ||||||||
| Revenue and royalties payable | ||||||||
| Derivative liabilities - current | ||||||||
| Hedge payable | ||||||||
| Current portion of long-term debt | ||||||||
| Lease liabilities, current | ||||||||
| Related party payable | ||||||||
| Other current liabilities | ||||||||
| Total current liabilities | ||||||||
| Long-term debt, net | ||||||||
| Asset retirement obligations | ||||||||
| Lease liabilities | ||||||||
| Derivative liabilities - noncurrent | ||||||||
| Earnout liability | ||||||||
| Total liabilities | ||||||||
| Commitments and Contingencies (Note 14) | ||||||||
| Series A redeemable preferred stock, $ | ||||||||
| Series B convertible redeemable preferred stock, $ | ||||||||
| Stockholders’ equity / members’ deficit | ||||||||
| Members’ deficit | ( | ) | ||||||
| Class A common stock, $ | ||||||||
| Class B common stock, $ | ||||||||
| Additional paid-in capital | ||||||||
| Accumulated deficit | ( | ) | ||||||
| Total stockholders’ equity attributable to Presidio Production Company / members’ deficit | ( | ) | ||||||
| Non-controlling interest | ||||||||
| Total stockholders’ equity / members’ deficit | ( | ) | ||||||
| Total liabilities, redeemable preferred stock and stockholders’ equity / members’ deficit | $ | $ | ||||||
The accompanying notes are an integral part of the unaudited condensed consolidated financial statements.
F-2
PRESIDIO PRODUCTION COMPANY
Condensed Consolidated Statements of Operations (Unaudited)
(in thousands, except per share amounts)
| Successor | Predecessor | Successor | Predecessor | |||||||||||||||||
| Three Months Ended |
Three Months Ended |
March 4, 2026 to |
January 1, 2026 to |
Six Months Ended |
||||||||||||||||
| June 30, 2026 |
June 30, 2025 |
June 30, 2026 |
March 3, 2026 |
June 30, 2025 |
||||||||||||||||
| Revenues: | ||||||||||||||||||||
| Oil sales | $ | $ | $ | $ | $ | |||||||||||||||
| Natural gas sales | ||||||||||||||||||||
| Natural gas liquids sales | ||||||||||||||||||||
| Field services revenue | ||||||||||||||||||||
| Total revenues | ||||||||||||||||||||
| Operating expenses: | ||||||||||||||||||||
| Lease operating expenses | ||||||||||||||||||||
| Production taxes | ||||||||||||||||||||
| Ad valorem taxes | ||||||||||||||||||||
| Depletion, oil and gas properties | ||||||||||||||||||||
| Depreciation and amortization, other property and equipment | ||||||||||||||||||||
| Accretion of asset retirement obligation | ||||||||||||||||||||
| General and administrative | ||||||||||||||||||||
| Acquisition and transaction costs | ||||||||||||||||||||
| Cost of field services revenue | ( | ) | ||||||||||||||||||
| Gain on sale of assets | ( | ) | ( | ) | ( | ) | ( | ) | ( | ) | ||||||||||
| Total operating expenses | ||||||||||||||||||||
| Income (loss) from operations | ( | ) | ||||||||||||||||||
| Other income (expense): | ||||||||||||||||||||
| Gain (loss) on commodity derivatives | ( | ) | ( | ) | ||||||||||||||||
| Change in fair value of earnout liability | ( | ) | ( | ) | ||||||||||||||||
| Loss on early extinguishment of debt | ( | ) | ( | ) | ||||||||||||||||
| Interest expense | ( | ) | ( | ) | ( | ) | ( | ) | ( | ) | ||||||||||
| Other income (expense) | ( | ) | ( | ) | ||||||||||||||||
| Total other income (expense) | ( | ) | ( | ) | ( | ) | ||||||||||||||
| Net income (loss) before income taxes | ( | ) | ( | ) | ||||||||||||||||
| Income tax benefit (expense) | ( | ) | ( | ) | ( | ) | ||||||||||||||
| Net income (loss) | ( | ) | ( | ) | ||||||||||||||||
| Net income (loss) attributable to non-controlling interests | ( | ) | ||||||||||||||||||
| Net income (loss) attributable to Presidio Production Company | $ | $ | $ | ( | ) | $ | ( | ) | $ | |||||||||||
| Net income (loss) per Class A common stock: | ||||||||||||||||||||
| Basic | ( | ) | ||||||||||||||||||
| Diluted | ( | ) | ||||||||||||||||||
| Weighted average Class A common stock outstanding: | ||||||||||||||||||||
| Basic | ||||||||||||||||||||
| Diluted | ||||||||||||||||||||
| Net income (loss) per PIH Class A unit, basic and diluted | $ | $ | ( | ) | $ | |||||||||||||||
| Weighted average PIH Class A units outstanding, basic and diluted | ||||||||||||||||||||
The accompanying notes are an integral part of the unaudited condensed consolidated financial statements.
F-3
PRESIDIO PRODUCTION COMPANY
Condensed Consolidated Statements of Redeemable Preferred Stock and Stockholders’/Members’ Equity (Deficit) (Unaudited)
(in thousands)
| Predecessor | Members’ Deficit |
|||
| Balance at December 31, 2024 | $ | ( | ) | |
| Capital distributions | ( | ) | ||
| Net loss | ( | ) | ||
| Balance at March 31, 2025 | $ | ( | ) | |
| Capital distributions | ||||
| Net income | ||||
| Balance at June 30, 2025 | $ | ( | ) | |
| Balance at December 31, 2025 | $ | ( | ) | |
| Net loss | ( | ) | ||
| Balance at March 3, 2026 | $ | ( | ) | |
| Redeemable Preferred Stock | Total Stockholders’ |
|||||||||||||||||||||||||||||||||||||||||||||||||||
| Series A | Series B Convertible | Equity Attributable |
||||||||||||||||||||||||||||||||||||||||||||||||||
| Redeemable | Redeemable | Class A | Class B | Additional | to Presidio | Total | ||||||||||||||||||||||||||||||||||||||||||||||
| Preferred Stock | Preferred Stock | Common Stock | Common Stock | Paid-In | Accumulated | Production | Non-controlling | Stockholders’ | ||||||||||||||||||||||||||||||||||||||||||||
| Successor | Shares | Amount | Shares | Amount | Shares | Amount | Shares | Amount | Capital | Deficit | Company | Interest | Equity | |||||||||||||||||||||||||||||||||||||||
| Balance at March 4, 2026 | $ | $ | $ | $ | $ | $ | ( | ) | $ | ( | ) | $ | $ | ( | ) | |||||||||||||||||||||||||||||||||||||
| Conversion of Class A ordinary shares and Class B ordinary shares into Class A common stock | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Reclassification of Class B ordinary shares subject to earnout arrangement | ( | ) | ( | ) | ( | ) | ||||||||||||||||||||||||||||||||||||||||||||||
| Deferred tax effects of earnout arrangement | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Issuance of equity consideration in Business Combination | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Issuance of Class A and Class B common stock in settlement of PIH share-based compensation liability | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Issuance of equity consideration in EQVR Acquisition | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Issuance of Series A redeemable preferred stock and warrants, net of issuance costs and discounts | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Preferred dividends attributable to Series A redeemable preferred stock | ( | ) | ( | ) | ( | ) | ||||||||||||||||||||||||||||||||||||||||||||||
| Issuance of Series B convertible redeemable preferred stock, net of issuance costs and discounts | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Excise tax imposed on common stock redemptions | ( | ) | ( | ) | ( | ) | ||||||||||||||||||||||||||||||||||||||||||||||
| Issuance of Class A common stock in connection with PIPE financing, net of issuance costs | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Share-based compensation | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net loss | ( | ) | ( | ) | ( | ) | ( | ) | ||||||||||||||||||||||||||||||||||||||||||||
| Balance at March 31, 2026 | $ | $ | $ | $ | $ | $ | ( | ) | $ | $ | $ | |||||||||||||||||||||||||||||||||||||||||
| Class A dividends and dividend reinvestment program shares | ( | ) | ( | ) | ( | ) | ||||||||||||||||||||||||||||||||||||||||||||||
| Dividends attributable to Preferred Investor Warrants | ( | ) | ( | ) | ( | ) | ||||||||||||||||||||||||||||||||||||||||||||||
| Preferred dividends attributable to Series B redeemable preferred stock | ( | ) | ( | ) | ( | ) | ||||||||||||||||||||||||||||||||||||||||||||||
| Paid-in-kind preferred dividends issued attributable to Series A redeemable preferred stock | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Preferred dividends attributable to Series A redeemable preferred stock | ( | ) | ( | ) | ( | ) | ||||||||||||||||||||||||||||||||||||||||||||||
| Dividend equivalents on restricted stock units, net of forfeitures | ( | ) | ( | ) | ( | ) | ||||||||||||||||||||||||||||||||||||||||||||||
| Distributions to non-controlling interests | ( | ) | ( | ) | ||||||||||||||||||||||||||||||||||||||||||||||||
| Share-based compensation | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net income | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Balance at June 30, 2026 | $ | $ | $ | $ | $ | $ | ( | ) | $ | $ | $ | |||||||||||||||||||||||||||||||||||||||||
The accompanying notes are an integral part of the unaudited condensed consolidated financial statements.
F-4
PRESIDIO PRODUCTION COMPANY
Condensed Consolidated Statements of Cash Flows (Unaudited)
(in thousands)
| Successor | Predecessor | |||||||||||
| March 4, 2026 to |
January 1, 2026 to |
Six Months Ended |
||||||||||
| June 30, 2026 |
March 3, 2026 |
June 30, 2025 |
||||||||||
| Cash flows from operating activities: | ||||||||||||
| Net (loss) income | $ | ( | ) | $ | ( | ) | $ | |||||
| Adjustments to reconcile net (loss) income to net cash provided by (used in) operating activities: | ||||||||||||
| Depletion, oil and gas properties | ||||||||||||
| Depreciation and amortization, other property and equipment | ||||||||||||
| Accretion of asset retirement obligation | ||||||||||||
| Settlement of asset retirement obligation liabilities | ( | ) | ( | ) | ||||||||
| Deferred tax benefit | ( | ) | ||||||||||
| Amortization of debt issuance costs | ||||||||||||
| Amortization of debt premiums | ( | ) | ||||||||||
| Loss on early extinguishment of debt | ||||||||||||
| Loss (gain) on commodity derivatives | ( | ) | ||||||||||
| Net settlements of commodity derivatives | ( | ) | ( | ) | ||||||||
| Cash paid for modification of derivative contracts, net of realized loss | ( | ) | ||||||||||
| Stock compensation expense | ||||||||||||
| Change in fair value of earnout liability | ||||||||||||
| Reduction of operating lease liabilities | ( | ) | ||||||||||
| Gain on sale of assets | ( | ) | ( | ) | ( | ) | ||||||
| Changes in operating assets and liabilities, net of effects from acquisition: | ||||||||||||
| Accounts receivable | ( | ) | ||||||||||
| Hedge receivable | ( | ) | ||||||||||
| Hedge payable | ( | ) | ( | ) | ||||||||
| Prepaid expenses and other current assets | ( | ) | ( | ) | ||||||||
| Other noncurrent assets | ( | ) | ( | ) | ||||||||
| Accounts payable | ( | ) | ||||||||||
| Related party payable | ( | ) | ||||||||||
| Other current liabilities | ( | ) | ||||||||||
| Net cash provided by (used in) operating activities | ( | ) | ( | ) | ||||||||
| Cash flows from investing activities: | ||||||||||||
| Capital expenditures for oil and natural gas properties | ( | ) | ( | ) | ( | ) | ||||||
| Purchases of other property and equipment | ( | ) | ( | ) | ( | ) | ||||||
| Proceeds from sale of assets | ||||||||||||
| Acquisition, net of cash acquired | ( | ) | ||||||||||
| Net cash provided by (used in) investing activities | ( | ) | ( | ) | ||||||||
| Cash flows from financing activities: | ||||||||||||
| Proceeds from issuance of Class A common stock in connection with PIPE financing, net of issuance costs | ||||||||||||
| Proceeds from issuance of Series A redeemable preferred stock and warrants, net of issuance costs and discounts | ||||||||||||
| Proceeds from issuance of Series B convertible redeemable preferred stock, net of issuance costs and discounts | ||||||||||||
| Payments of dividends | ( | ) | ||||||||||
| Payments of dividend equivalents | ( | ) | ||||||||||
| Proceeds from long-term debt | ||||||||||||
| Repayments of long-term debt | ( | ) | ( | ) | ( | ) | ||||||
| Payments of debt issuance costs | ( | ) | ( | ) | ||||||||
| Payments on finance lease liabilities | ( | ) | ( | ) | ( | ) | ||||||
| Cash settlement of PIH share-based compensation liability | ( | ) | ||||||||||
| Member distributions | ( | ) | ||||||||||
| Net cash provided by (used in) financing activities | ( | ) | ( | ) | ||||||||
| Net increase (decrease) in cash, cash equivalents, and restricted cash | ( | ) | ||||||||||
| Cash, cash equivalents, and restricted cash at beginning of period | ||||||||||||
| Cash, cash equivalents, and restricted cash at end of period | $ | $ | $ | |||||||||
| Supplemental cash flow information: | ||||||||||||
| Cash paid for interest | $ | $ | $ | |||||||||
| Stock issued for acquisitions | $ | $ | $ | |||||||||
| Satisfaction of liability-classified share-based payment awards | $ | $ | $ | |||||||||
| Right-of-use assets obtained in exchange for new operating lease liabilities | $ | $ | $ | |||||||||
| Cash paid for amounts included in the measurement of lease liabilities: | ||||||||||||
| Operating cash flows from operating leases | $ | $ | $ | |||||||||
The accompanying notes are an integral part of the unaudited condensed consolidated financial statements.
F-5
PRESIDIO PRODUCTION COMPANY
Notes to Unaudited Condensed Consolidated Financial Statements
NOTE 1. ORGANIZATION AND DESCRIPTION OF BUSINESS
Organization
EQV Ventures Acquisition Corp. (“EQV”) was incorporated as a Cayman Islands exempted company on April 15, 2024. EQV was formed for the purpose of effecting a merger, amalgamation, share exchange, asset acquisition, share purchase, reorganization or similar business combination with one or more businesses or entities (the “Business Combination”).
On March 4, 2026 (the “Closing Date”), Presidio Production Company (“Presidio”, the “Company”) (formerly known as Presidio PubCo Inc.) consummated the Business Combination as described in Note 3 — Business Combinations pursuant to the Business Combination Agreement dated August 5, 2025. As part of the transaction, EQV changed its jurisdiction of incorporation from the Cayman Islands to the State of Delaware and was renamed “Presidio MidCo Inc.” (the “Domestication”). Immediately following the Domestication, Prometheus PubCo Merger Sub Inc., a Delaware corporation (“EQV Merger Sub”) merged with and into EQV (the “Merger”) with EQV surviving as a wholly-owned subsidiary of the Company (“EQV Surviving Subsidiary”). The Company is organized in an Up-C structure in which substantially all assets and operations of Presidio Investment Holdings LLC, a Delaware limited liability company (“PIH”) are held indirectly through Prometheus Holdings LLC, a Delaware limited liability company (“EQV Holdings”, “Opco”). The Company holds the managing member interest in Opco through EQV Surviving Subsidiary.
In connection with the Business Combination, a portion of EQV shares were exchanged for cash from shareholders who elected to execute their redemption right. The remaining EQV shares were exchanged for newly issued shares of Presidio Class A common stock (“Class A Common Stock”). The EQV public and private placement warrants were assumed by the Company and exchanged for warrants exercisable for Class A Common Stock (“Presidio Public and Private Placement Warrants”). Refer to Note 9 — Redeemable Preferred Stock and Stockholders’ Equity (Successor) for further discussion on the Presidio Public and Private Placement Warrants. Additionally, pursuant to the Rollover Agreements dated August 5, 2025, certain unitholders of PIH (“PIH Rollover Holders”) exchanged their outstanding equity interests in PIH for EQV Holdings common units (“Opco Common Units”) and an equal number of newly issued shares of Presidio Class B common stock (“Class B Common Stock”). The owners of Opco other than the Company are considered non-controlling interests in the accompanying condensed consolidated financial statements. Refer to Note 3 — Business Combinations for further discussion on the Business Combination.
Also on the Closing Date, the Company acquired all of the issued and outstanding equity interests of EQV Resources LLC, a Delaware limited liability company (“EQVR”) pursuant to the agreement and plan of merger dated August 5, 2025 (“EQVR Acquisition”). Immediately following closing of the EQVR Acquisition, Presidio contributed EQVR to EQV Surviving Subsidiary and EQV Surviving Subsidiary contributed EQVR to Opco. Refer to Note 3 — Business Combinations for further discussion on the EQVR Acquisition.
Opening successor cash and equity represent the carrying value of the accounting acquirer’s cash and equity and are not comparable to the predecessor cash and equity of PIH. Included in the opening cash balance as of March 4, 2026 was $
The Company’s Class A common stock and warrants are listed on the New York Stock Exchange under the ticker symbols “FTW” and “FTW WS,” respectively.
Description of Business
Presidio is an independent oil and natural gas company engaged in oil and gas exploration and production, with operations concentrated across the Western Anadarko Basin of Texas, Oklahoma, and Kansas. The Company’s strategy is centered on acquiring existing producing assets and applying engineering expertise and Artificial Intelligence (“AI”) data driven analytics to enhance performance and extend asset life.
F-6
Inflation Reduction Act of 2022
On August 16, 2022, the Inflation Reduction Act of 2022 (the “IR Act”) was signed into federal law. The IR Act provides for, among other things, a new U.S. federal
In connection with the Business Combination, a total of
NOTE 2. BASIS OF PRESENTATION AND SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES
Basis of Presentation
These unaudited, interim, condensed consolidated financial statements and notes are prepared in accordance with accounting principles generally accepted in the United States of America (“US GAAP”) and in accordance with the rules and regulations of the SEC. These unaudited interim financial statements reflect all adjustments which are, in the opinion of management, necessary to present fairly the results for the interim periods presented. The Company’s accounting policies conform to US GAAP and have been consistently applied in the presentation of financial statements. The Company’s condensed consolidated financial statements include all wholly-owned subsidiaries and all variable interest entities for which the Company determined it is the primary beneficiary. Intercompany balances and transactions have been eliminated in consolidation. Certain information and disclosures normally included in annual financial statements prepared in accordance with US GAAP have been condensed or omitted.
The condensed consolidated financial statements include a Predecessor period, which was the period from January 1, 2026 through March 3, 2026, concurrent with completion of the Business Combination and Successor period from March 4, 2026 through June 30, 2026. As a result of the Business Combination and EQVR Acquisition, the results of operations, financial position and cash flows of the Predecessor and Successor may not be directly comparable. A black-line between the Successor and Predecessor periods has been placed in the condensed consolidated financial statements and in the tables to the notes to the condensed consolidated financial statements to highlight the lack of comparability between these two periods as the Business Combination resulted in a new basis of accounting for PIH.
Correction of Immaterial Error
During the second quarter of 2026, the Company identified an immaterial error in its cash reconciliation process resulting in an understatement of cash of $
Reclassifications
Certain prior period amounts have been reclassified to conform to the current period presentation. Amounts payable to derivative counterparties for settled commodity derivative positions, previously included within accounts payable, are now presented separately as hedge payable on the condensed consolidated balance sheets, and the related changes are presented separately within operating activities on the condensed consolidated statements of cash flows. As a result, $
F-7
Principles of Consolidation
Under the Up-C structure, PIH Rollover Holders own all of the shares of Class B Common Stock which are non-economic voting only shares of the Company. PIH Unit Holders’ economic interest in the Company is held through their ownership (the “Common Units”) in the Opco. Pursuant to the amended and restated limited liability company agreement of the Opco (the “A&R LLC Agreement”), the Company’s ownership of Common Units in the Opco at all times equals the number of shares of the Company’s Class A Common Stock then outstanding, and PIH Rollover Holders’ ownership of Common Units in the Opco at all times equals the number of shares of Class B Common Stock then outstanding. The Opco was formed for the purpose of executing the Company’s organization with PIH Rollover Holders into an Up-C structure. The Opco, through its subsidiaries, owns, operates, and manages oil and gas properties and manages the Company’s outstanding debt and derivative instruments. The Company’s wholly-owned subsidiary, EQV Surviving Subsidiary, is the managing member of the Opco. Subsidiaries of the Opco own and operate all our oil and gas assets. The Company and the Opco are holding companies with no other operations, material cash flows, or material assets or liabilities other than the equity interests in their subsidiaries.
Holders of Common Units (other than the Company) have the right (an “exchange right”), subject to certain limitations, to exchange Presidio Interests (each consisting of
Holders of EQV Holdings Common Units (other than the Company) will generally be permitted to exercise the exchange right on a quarterly basis, subject to certain de minimis allowances. In addition, additional exchanges may occur in connection with certain specified events, and any exchanges involving more than a specified number of Common Units (subject to the Company’s discretion to permit exchanges of a lower number of units) may occur at any time with advanced notice. The exchange rights are subject to certain limitations and restrictions intended to reduce the administrative burden of exchanges upon the Company and ensure that Opco will continue to be treated as a partnership for U.S. federal income tax purposes.
The Opco is considered a variable interest entity for which the Company is the primary beneficiary. This conclusion was based on a qualitative analysis that considered the Opco’s governance structure and the Company’s control over operations of the Opco. The Company, through its wholly owned subsidiary, EQV Surviving Subsidiary, as the managing member of EQV Holdings, has the decision making authority along with the ability to control the most significant activities of the Opco and participate significantly in the Opco’s benefits and losses, where the PIH Rollover Holders directly holding other Common Units have neither substantive kick-out rights nor substantive participating rights. As such, because the Company has both power and economics in the Opco, the Company determined it is the primary beneficiary of the Opco and consolidates the Opco in the Company’s condensed consolidated financial statements. The Company reflects a non-controlling interest in the condensed consolidated financial statements based on the proportion of Common Units owned by PIH Rollover Holders relative to the total number of Common Units outstanding. The non-controlling interest is presented as a component of equity in the accompanying condensed consolidated financial statements and represents the ownership interest held by PIH Rollover Holders in the Opco.
Non-controlling Interest
The non-controlling interest percentage may be affected by the issuance of shares of Class A Common Stock, repurchases or cancellation of Class A Common Stock, the exchange of Class B Common Stock and the redemption of Common Units (and concurrent cancellation of Class B Common Stock), among other things. The percentage is based on the proportionate number of Opco Common Units held by PIH Rollover Holders relative to the total Common Units outstanding. As of June 30, 2026, the Company owned
When the Company’s relative ownership interest in the Opco changes, adjustments to Non-controlling interest and Paid-in capital, tax effected, will occur. Because these changes in the ownership interest in the Opco do not result in a change of control, the transactions are accounted for as equity transactions under authoritative guidance in Financial Accounting Standards Board (“FASB”) Accounting Standards Codification (“ASC”) Topic 810, Consolidation (“ASC 810”), which requires that any differences between the carrying value of the Company’s basis in the Opco and the fair value of the consideration received are recognized directly in equity and attributed to the controlling interest. Additionally, based on the A&R LLC Agreement, there are no substantive profit sharing arrangements that would cause distributions to be other than pro rata. Therefore, profits and losses are attributed to the common shareholders and non-controlling interest pro rata based on ownership interests in the Opco.
F-8
Use of Estimates
The preparation of financial statements in conformity with GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. Actual results could differ from these estimates. Additionally, the prices received for crude oil, natural gas, and NGLs production can heavily influence our assumptions, judgments and estimates, and continued volatility of crude oil and natural gas prices could have a significant impact on our estimates. Estimates significant to our condensed consolidated financial statements include the following:
| ● | proved reserves used in calculating depletion; |
| ● | estimates of accrued revenues and unbilled costs; |
| ● | future cash flows from proved oil and natural gas reserves used in the impairment assessment; |
| ● | derivative financial instruments; |
| ● | asset retirement obligations; |
| ● | income taxes; and |
| ● | the fair value of share-based compensation awards. |
Cash and Cash Equivalents
The Company considers all highly liquid investments with original maturities of three months or less to be cash equivalents. The Company had cash equivalents as of June 30, 2026 and December 31, 2025.
Restricted Cash
At the closing date of the ABS III securitization transaction (see Note 7 — Debt), the Company was required to deposit an additional $
The following table provides a reconciliation of cash, cash equivalents and restricted cash reported within the condensed consolidated balance sheets:
| Successor | Predecessor | |||||||
| (in thousands) | June 30, 2026 | December 31, 2025 | ||||||
| Cash and cash equivalents | $ | $ | ||||||
| Restricted cash | ||||||||
| Total cash, cash equivalents, and restricted cash presented in the statement of cash flows | $ | $ | ||||||
Concentrations of Credit Risk
Financial instruments that potentially subject the Company to a concentration of credit risk consist principally of cash and accounts receivable. The Company maintains deposits at financial institutions, which at times may exceed amounts covered by insurance provided by the U.S. Federal Deposit Insurance Corporation (“FDIC”). The Company has not experienced any losses related to amounts in excess of FDIC limits and believes the counter party risks are minimal based on the reputation and history of the institutions in which the funds are deposited and held.
During the three months ended June 30, 2026 (Successor) and the period from March 4, 2026 through June 30, 2026 (Successor), oil, natural gas and NGL revenues from three purchasers totaled approximately
F-9
No other customer balance represented greater than 10% of total accounts receivable as of June 30, 2026 or December 31, 2025. We believe that sufficient alternative purchasers exist for the Company’s oil, natural gas and NGL production and that the loss of any single purchaser would not be considered a significant interruption or business risk to the Company.
Accounts Receivable
The Company sells oil, natural gas and NGLs to various customers. Oil, natural gas and NGLs sales receivables related to these operations are generally unsecured and most payments for production are received within three months after the production date. Joint interest receivables are generally secured pursuant to the operating agreement between the operator and the joint interest owner. The Company regularly evaluates the collectability of joint interest receivables, including an assessment of expected credit losses. When appropriate based on credit risk considerations, the Company has the ability to settle receivables through netting of anticipated future production revenues. Accounts receivable amounts due from joint interest owners are stated net of an allowance for credit losses.
The Company establishes allowances for credit losses by applying an aged-based loss-rate to estimate expected lifetime credit losses on its joint interest receivables. The historical allowance for credit losses on joint interest receivables was eliminated through the Business Combination. As such, the allowance for credit losses on joint interest receivables was $
Derivative Activities
The Company has entered into derivative instruments to mitigate a portion of its exposure to market changes in hydrocarbon prices and basis differentials. Swap instruments require a sale of the hedged commodity at a fixed price and a purchase at a floating market price, as defined in each instrument, to a counterparty. The Company recognizes all price risk management instruments as either assets or liabilities measured at fair value. The Company has presented the fair value of derivative assets and liabilities on a net basis by counterparty in the accompanying condensed consolidated balance sheet where the right of offset exists.
The new ABS III securitization transaction (see Note 7 — Debt) included certain hedging requirements. At the closing date of the ABS III securitization transaction, the Company was required to hedge
The Company has designated any price risk management instruments as fair value or cash flow hedges during six months ended June 30, 2026 or June 30, 2025.
Oil and Natural Gas Properties
The Company utilizes the successful efforts method of accounting for its oil and gas properties. Under this method, costs of acquiring properties, drilling successful exploration wells, development costs, and workover costs result in additions to proved properties that are capitalized. The costs of exploratory wells are initially capitalized pending a determination of whether proved reserves have been found. At the completion of drilling activities, the costs of exploratory wells remain capitalized if the determination is made that proved reserves have been found. If no proved reserves have been found, the costs of each of the related exploratory wells are charged to expense. In some cases, a determination of proved reserves cannot be made at the completion of drilling, requiring additional testing and evaluation of the wells. The costs of such exploratory wells are expensed if a determination of proved reserves has not been made within a twelve-month period after drilling is complete. Exploration costs such as geological, geophysical and seismic costs are expensed as incurred.
F-10
The capitalized costs of proved properties are depleted using the unit-of-production method based on proved developed or total proved reserves as applicable. Costs of significant non-producing properties, wells in the process of being drilled and prepaid development costs are excluded from depletion until proved reserves are established or, if unsuccessful, impairment is determined.
Producing property is considered impaired when the carrying cost of property exceeds its undiscounted future net cash flows. When a property is impaired the carrying value is reduced to the discounted future net cash flows and an impairment charge of the difference between cost and discounted future net cash flows is recorded. Non-producing properties are considered impaired when the Company considers it likely that the associated leasehold will expire without plans to renew or extend the lease.
Other Property and Equipment
Other property and equipment are carried at cost less accumulated depreciation. Major renovations and improvements are capitalized while expenditures for maintenance and repairs are expensed as incurred. Upon sale or abandonment, the cost of the equipment and related accumulated depreciation are removed from the accounts and any gain or loss is recognized. Depreciation is calculated using the straight-line method over the estimated useful lives of the various assets. See Note 5 — Property, Plant and Equipment.
Impairment of Long-Lived Assets
The carrying value of proved oil and natural gas properties, salt water disposal wells and related facilities, and other property and equipment is periodically evaluated for impairment whenever events or changes in circumstances indicate that the carrying amount of an asset may not be recoverable. When it is determined that the estimated future net cash flows of an asset will not be sufficient to recover its carrying amount, an impairment loss must be recorded to reduce the carrying amount to its estimated fair value.
Under ASC Topic 360, Property, Plant, and Equipment, the Company evaluates impairment of proved and unproved oil and natural gas properties based on expected future net cash flows from the asset group. As the Company’s properties are managed and evaluated as a single field, impairment testing is performed on that basis. impairment was recorded during the period from March 4, 2026 through June 30, 2026 (Successor) or the period from January 1, 2026 through March 3, 2026 (Predecessor).
Leases
The Company leases office space and vehicles. Right-of-use assets and lease liabilities are initially recorded at the commencement date based on the present value of lease payments over the lease term. The Company uses its incremental borrowing rate to discount future lease payments. Certain leases contain variable costs above the minimum required payments and are not included in the right-of-use assets or lease liabilities. Options to extend or terminate a lease are included in the lease term when it is reasonably certain the Company will exercise that option. For operating leases, lease cost is recognized on a straight-line basis over the term of the lease. Leases with an initial term of 12 months or less are not included on the condensed consolidated balance sheet. The Company elected a practical expedient to not separate non-lease components from lease components for office space leases. The Company did not elect this practical expedient for vehicle leases.
Asset Retirement Obligations
Asset retirement obligations relate to the future costs associated with the plugging, dismantlement, remediation, and abandonment (“P&A”) of oil and natural gas wells and locations. Estimates are based on projected remaining lives of those wells based on reserve estimates and internal estimates of the future cost to P&A the wells at the end of their remaining lives. The Company records the discounted present value of those anticipated costs as its asset retirement obligation liability.
Future periodic accretion of the discount on asset retirement obligations will be recorded as an expense in the accompanying condensed consolidated statements of operations.
F-11
Revenue Recognition
Upstream Revenues
The Company disaggregates revenues from contracts with customers by type of commodity. Upstream revenues include the sale of oil, gas and NGL production which are recognized at a point in time when control is transferred to the purchaser upon delivery of contract-specified production volumes at a specified point. The transaction price used to recognize revenue is a function of the contract billing terms. Revenue is invoiced, if required, by calendar month based on volumes at contractually based rates with payment typically received within
The Company also evaluates its contracts for the principal/agent provisions. If the Company is determined to be the principal, it would recognize revenue at the gross purchase price and record an expense for certain fees charged by the customer (such as transportation and fractionation fees) incurred prior to the transfer of control, as the Company would still have control of the product when these activities take place. Alternatively, when the Company is determined to be the agent, it recognizes the revenues based on the net price received from the purchaser, as control is determined to have transferred prior to the activities. During this evaluation, the Company concluded that it acts as the agent in all current contracts. Accordingly, revenue is recognized based on the net proceeds received from the purchaser.
Oil Sales
The Company sells its crude oil production at the wellhead for a contractually-specified index price, net of pricing differentials. The Company recognizes revenue when control transfers to the purchaser at the delivery point based on the price received from the purchaser. Oil revenues are recorded net of any third-party transportation fees and other applicable differentials in the Company’s condensed consolidated statements of operations.
Natural Gas and NGL Sales
Under the Company’s natural gas processing contracts, natural gas is delivered to a midstream processing entity at the wellhead or the inlet of the midstream processing entity’s system. The midstream processing entity gathers and processes the natural gas and remits proceeds for the resulting sales of NGLs and residue gas. The Company has determined that it is the agent in these transactions and recognizes revenue on a net basis, with transportation, gathering, processing, treating and compression fees as a reduction to revenues in the condensed consolidated statements of operations.
Satisfaction of Performance Obligation and Revenue Recognition
Because the Company has a right to consideration from its customers in amounts that correspond directly to the value that the customer receives from the performance completed on each contract, the Company recognizes revenue for sales at the time the crude oil, natural gas or NGLs are delivered at a fixed or determinable price.
Transaction Price Allocated to Remaining Performance Obligations
The Company’s upstream product sales contracts do not originate until production occurs and, therefore, are not considered to exist beyond each day’s production. Therefore, there are no remaining performance obligations under any of its product sales contracts.
Under the Company’s revenue agreements, each delivery generally represents a separate performance obligation; therefore, future volumes delivered are wholly unsatisfied and disclosure of the transaction price allocated to remaining performance obligations is not required.
Contract Balances
Under the Company’s commodity sales contracts, the Company recognizes revenue after its performance obligations have been satisfied, at which point the Company has an unconditional right to receive payment. Accordingly, the Company’s commodity sales contracts generally do not give rise to contract assets or contract liabilities under ASC 606. Instead, the Company’s unconditional rights to receive consideration are presented as a receivable within accounts receivable attributable to oil and gas sales in its condensed consolidated balance sheets. The Company has not recognized any contract assets or liabilities as of June 30, 2026 or December 31, 2025.
The opening balance of accounts receivable attributable to oil and natural gas sales was $
F-12
Field Services Revenues
The Company provides field services through its Trail Dust subsidiary, including compression, forward-looking infrared (“FLIR”) surveys, emissions reduction equipment, tubing scanning, and line locating services, with compression and FLIR surveys representing the Company’s most significant service lines. When these services are provided to third party customers, including its third-party working interest partners, the Company generates supplemental, other revenues.
Revenue from compression services is recognized as earned in the month the work is performed in accordance with the contractual obligations. Revenue from FLIR surveys, tubing scanning, and line locating services is recognized at the point in time when the service is completed and the customer has accepted the work performed. Revenue from the sale of emissions reduction equipment is recognized upon delivery.
Fair Value Measurement
The Company utilizes a fair value hierarchy established by ASC 820, Fair Value Measurement (“ASC 820”) to categorize its assets and liabilities based on inputs to the valuation techniques used to measure fair value. The hierarchy gives the highest priority to unadjusted quoted prices in active markets for identical assets or liabilities (Level 1 measurements) and lowest priority to unobservable inputs (Level 3 measurements). The three levels of the fair value hierarchy are described below:
Level 1 — Inputs to the valuation methodology are unadjusted quoted prices for identical assets or liabilities in active markets that the Company has the ability to access.
Level 2 — Inputs to the valuation methodology include:
| ● | Quoted prices for similar assets or liabilities in active markets; |
| ● | Quoted prices for identical or similar assets or liabilities in inactive markets; |
| ● | Inputs other than quoted prices that are observable for the asset or liability; |
| ● | Inputs that are derived principally from or corroborated by observable market data by correlation or other means. |
If the asset or liability has a specified (contractual) term, the Level 2 input must be observable for substantially the full term of the asset or liability.
Level 3 — Inputs to the valuation methodology are unobservable and significant to the fair value measurements.
Financial assets and liabilities are classified based on the lowest level of input that is significant to the fair value measurement.
General and Administrative
General and administrative (“G&A”) expenses primarily consist of employee compensation and related benefits, professional services, and other corporate overhead costs incurred in the normal course of business. Compensation and benefits represent the largest component of G&A.
For the three months ended June 30, 2026 (Successor) and the period from March 4, 2026 through June 30, 2026 (Successor), G&A included $
For the period from January 1, 2026 through March 3, 2026 (Predecessor), G&A included $
For the three and six months ended June 30, 2025 (Predecessor), G&A included $
In addition, the Company provides administrative services to non-operated working interest owners under Council of Petroleum Accountants Societies (“COPAS”) joint operating agreements. Reimbursements received for such services are recorded as an offset to G&A expenses in the condensed consolidated statements of operations.
F-13
Income Taxes
The Company accounts for income taxes under ASC Topic 740, Income Taxes (“ASC 740”), which requires an asset and liability approach to financial accounting and reporting for income taxes. Deferred tax assets and liabilities are computed for differences between the financial statement and tax bases of assets and liabilities that will result in future taxable or deductible amounts, based on enacted tax laws and rates applicable to the periods in which the differences are expected to affect taxable income. Valuation allowances are established, when necessary, to reduce deferred tax assets to the amount expected to be realized.
ASC 740 prescribes a recognition threshold and a measurement attribute for the financial statement recognition and measurement of tax positions taken or expected to be taken in a tax return. For those benefits to be recognized, a tax position must be more likely than not to be sustained upon examination by taxing authorities. Recognized tax positions are measured as the largest amount of tax benefit that is greater than
Prior to the closing of the Business Combination, the Predecessor was a partnership for income tax purposes. Any taxable income or loss was passed through to its owners and was recognized by the owners on their respective income tax returns. Accordingly, no federal, state, or local income taxes have been reflected in the accompanying condensed consolidated financial statements of the Predecessor. Significant differences may exist between the results of operations reported in these condensed consolidated financial statements and those determined for income tax purposes primarily due to the use of different asset valuation methods for tax purposes.
Net Income (Loss) Per Share
Successor
Basic net income (loss) per share of common stock is computed by dividing net income (loss) available to common stockholders by the weighted average number of shares of common stock outstanding during the period, including any common shares issuable for nominal consideration for which all contingencies have been satisfied and excluding any legally outstanding common shares subject to forfeiture. Net income (loss) attributable to non-controlling interests is excluded from net income (loss) available to common stockholders. Dividends on Series A Redeemable Preferred Stock (as defined in Note 3 — Business Combinations), whether payable in cash or in-kind, and adjustments to the carrying amount of the redeemable preferred stock, as applicable, reduce net income, or increase net loss, available to common stockholders. Allocations of undistributed earnings to participating securities under the two-class method reduce net income available to common stockholders.
Diluted net income (loss) per share reflects the potential dilution from outstanding instruments that may be exercised, converted, exchanged, or settled in shares of the Company’s Class A Common Stock. The Company applies the treasury stock method, the if-converted method, the contingently issuable share method, and the two-class method, as applicable, and includes only those potential common shares whose effect is dilutive. Potential common shares are excluded from the diluted net income (loss) per share calculation when their effect would be antidilutive.
The Company’s Class B Common Stock has no economic rights to the undistributed earnings of the Company and is not considered a participating security under ASC 260, Earnings Per Share (“ASC 260”). Accordingly, the Company does not present net income (loss) per share for the Class B Common Stock, and shares of Class B Common Stock are excluded from the calculation of net income (loss) per share for the Class A Common Stock.
Predecessor
Basic net income (loss) per share is computed by dividing net income (loss) by the weighted-average number of PIH Class A units outstanding during the period. Diluted net income (loss) per share is calculated to give effect to potentially issuable dilutive common shares. PIH did not have additional instruments or other substantive classes of equity to create a dilutive effect on net income (loss) per share during the period.
F-14
Mezzanine Equity
Series A Redeemable Preferred Stock and Series B Convertible Redeemable Preferred Stock (as defined in Note 3 — Business Combinations) are presented within the condensed consolidated balance sheet as of June 30, 2026 as mezzanine equity as both instruments are contingently redeemable upon the occurrence of events not solely within the Company’s control. The Series A Redeemable Preferred Stock was issued in connection with freestanding equity-classified warrants; as such, net proceeds from the issuance were allocated between the two instruments on a relative fair value basis, creating a discount on the Series A Redeemable Preferred Stock. The Series B Convertible Redeemable Preferred Stock was recorded at fair value upon issuance, net of issuance costs and discounts.
In addition, certain embedded features (“embedded derivatives”) included in the Series A Redeemable Preferred Stock required bifurcation under the authoritative guidance in ASC 815-15, Derivatives and Hedging, Embedded Derivatives (“ASC 815-15”) and were classified as derivative liabilities. The embedded derivative is measured at fair value at inception, creating a discount on the host preferred stock instrument, and subsequently remeasured at fair value each reporting date thereafter, with changes in fair value recognized in the condensed consolidated statement of operations in the period of change. Embedded features deemed not clearly and closely related to the host preferred stock instrument at inception are reassessed under ASC 815-15 each subsequent reporting date while the host instrument is outstanding. However, as of the issuance date and June 30, 2026, the Company determined the embedded derivative had a minimal fair value and, as such, was not recorded.
As of June 30, 2026, both the Series A Redeemable Preferred Stock and Series B Convertible Redeemable Preferred Stock were neither currently redeemable nor probable of becoming redeemable in the future based on an evaluation of the likelihood of the events that would trigger redemption occurring. As such, the carrying values were not adjusted during the period from March 4, 2026 through June 30, 2026 (Successor). The Company accrues for the mandatory, unconditional dividend obligations on the Series A Redeemable Preferred Stock as they become contractually payable, regardless of whether any dividends are declared.
Warrant Instruments
The Company accounts for warrants as either equity-classified or liability-classified instruments based on an assessment of the warrant’s specific terms and applicable authoritative guidance in ASC 480, Distinguishing Liabilities from Equity (“ASC 480”) and ASC 815-40, Derivatives and Hedging, Contracts in an Entity’s Own Equity (“ASC 815-40”). The assessment considers whether the warrants are freestanding financial instruments pursuant to ASC 480, meet the definition of a liability pursuant to ASC 480, and, if not, whether the warrants meet all of the requirements for equity classification under ASC 815-40, including whether the warrants are indexed to the Company’s own common stock and meet all other conditions for equity classification. This assessment is conducted at the time of warrant issuance and as of each subsequent reporting date while the warrants are outstanding.
In accordance with ASC 815-40, the Company has classified all its warrant instruments as equity. Warrant instruments are recorded and measured at fair value at the time of issuance, net of issuance costs, as applicable.
Earnout Shares
In connection with the Business Combination, EQV Ventures Sponsor LLC, a Delaware limited liability company (the “Sponsor”), agreed to subject certain of its founder shares to vesting (or forfeiture) on the basis of achieving certain trading price thresholds during the first five years following the closing of the Business Combination pursuant to an earnout program (“Earnout Shares”) (see Note 3 — Business Combinations for further information). The Earnout Shares do not contain dividend or voting rights prior to vesting. The Earnout Shares represent freestanding equity-linked contracts and are assessed for either liability or equity classification under the authoritative guidance in ASC 480 and ASC 815-40.
In accordance with ASC 815-40, the Earnout Shares are reported as liabilities within the Company’s condensed consolidated balance sheet because they do not qualify as being indexed to the Company’s own equity. The Earnout Shares are measured at fair value at inception and at each reporting date thereafter, with changes in fair value recognized in the condensed consolidated statement of operations in the period of change.
F-15
Members’ Deficit and Share-Based Compensation (Predecessor)
PIH’s equity in the Predecessor period consisted of membership interests in the form of (i) Class A units issued and held by PIH’s former private-equity sponsor and certain members of management in exchange for capital contributions, and (ii) Class B units held by certain members of PIH which represented non-voting, equity compensation awards intended to constitute profit interests within the meaning of IRS guidelines. Distributions to holders of Class A units and Class B units were made in accordance with the PIH Amended and Restated Limited Liability Company Agreement (“PIH LLC Agreement”).
The Class B units vested
On January 6, 2025, the Board of Representatives of PIH approved a cash distribution totaling $
As a result of the Business Combination, all PIH Class A and Class B units were exchanged at the unitholders’ election for either (i) cash or (ii) equity in either (a) Presidio Class A Common Stock or (b) EQV Holdings Common Units and an equal number of shares of Presidio Class B Common Stock. No Class A or Class B units remained issued or outstanding following the Business Combination. See “General and Administrative” in this Note 2 — Basis of Presentation and Summary of Significant Accounting Policies for settlement of the PIH Class B units in connection with the Business Combination.
Share-based Compensation (Successor)
The Company accounts for share-based compensation in accordance with ASC 718. Share-based awards are measured at their grant-date fair value and recognized as compensation expense on a straight-line basis over the requisite service period, which generally corresponds to the vesting period of the award.
For restricted stock units, which are equity-classified, fair value is determined based on the closing stock price of the Company’s Class A common stock on the grant date. The Company accounts for forfeitures as they occur. See Note 10 — Share-based Compensation (Successor) for further discussion.
Adoption of New Accounting Standards
In July 2025, the FASB issued Accounting Standards Update No. 2025-05, “Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses for Accounts Receivable and Contract Assets” (“ASU 2025-05”). ASU 2025-05 provides a practical expedient that all entities can use when estimating expected credit losses for current accounts receivable and current contract assets arising from transactions accounted for under ASC 606, Revenue from Contracts with Customers. The Company adopted ASU 2025-05 effective January 1, 2026 and elected to apply the guidance prospectively. Based on the short-term nature of the Company’s accounts receivable and contract assets, historical loss experience, and current credit risk management practices, the adoption of ASU 2025-05 did not have a material impact on the Company’s consolidated financial statements or related disclosures.
In April 2026, the FASB issued ASU 2026-01, “Equity (Topic 505): Initial Measurement of Paid-in-Kind Dividends on Equity-Classified Preferred Stock.” The ASU requires that PIK dividends on equity-classified preferred stock be initially measured on the basis of the PIK dividend rate stated in the preferred stock agreement. The standard is effective for all entities for annual reporting periods beginning after December 15, 2026, and interim reporting periods within those annual reporting periods, with early adoption permitted. The Company elected to early adopt ASU 2026-01 effective March 4, 2026 (the Closing Date of the Business Combination), using the prospective transition method. The Company has applied the guidance to the initial measurement of PIK dividends on its Series A Redeemable Preferred Stock, under which the PIK dividend rate is applied to the then-current investment amount (defined as the subscription amount plus accrued but unpaid dividends) in accordance with the Series A Certificate of Designation. The adoption of ASU 2026-01 did not have a material impact on the Company’s condensed consolidated financial statements.
F-16
Accounting Standards Not Yet Adopted
In November 2024 and January 2025, the FASB issued ASU 2024-03 and ASU 2025-01, “Income Statement — Reporting Comprehensive Income — Expense Disaggregation Disclosures (Subtopic 220-40).” The amendments require disclosure, in the notes to financial statements, of specified information about certain costs and expenses included in each relevant expense caption on the face of the income statement, including the amounts of employee compensation, depreciation, depletion and amortization, and other prescribed categories. ASU 2025-01 clarified the effective date to be annual reporting periods beginning after December 15, 2026, and interim reporting periods within annual periods beginning after December 15, 2027, with early adoption permitted. The Company is currently assessing the impact this update will have on its financial statement disclosures.
In September 2025, the FASB issued ASU 2025-06, “Intangibles — Goodwill and Other — Internal-Use Software (Subtopic 350-40): Targeted Improvements.” The amendments make targeted improvements to the guidance on accounting for costs incurred in connection with internal-use software, including clarification of which development costs should be capitalized versus expensed. The standard is effective for annual reporting periods beginning after December 15, 2027, with early adoption permitted. The Company is currently assessing the impact this update will have on its financial statements.
NOTE 3. BUSINESS COMBINATIONS
In accordance with ASC 810, Consolidation (“ASC 810”), Opco is a variable interest entity (“VIE”) for which the Company is the primary beneficiary. The Company, through its wholly-owned subsidiary, EQV Surviving Subsidiary, has power over the activities most significant to the VIE’s economic performance. The Company also indirectly holds Opco Common Units and participates significantly in the VIE’s benefits and losses. The PIH Rollover Holders that directly hold the other Opco Common Units have neither substantive kick-out rights nor substantive participating rights. As such, because the Company has both power and benefits in Opco, the Company determined it is the primary beneficiary of Opco. Therefore, the Company is deemed to be the accounting acquirer in the Business Combination and EQVR Acquisition. EQV represents the Company in the accounting acquirer determination. As the accounting acquirer, EQV’s net assets and stockholders’ equity retain their carrying value.
Pursuant to ASC 805, Business Combinations (“ASC 805”), PIH and EQVR did not meet the definition of a business due to each individually meeting the screen test. The Business Combination and EQVR Acquisition are both accounted for as acquisitions of VIEs that are not a business in accordance with ASC 810. The assets acquired and liabilities assumed are estimated at their acquisition-date fair values under the acquisition method.
In connection with the Business Combination and pursuant to the rollover agreements dated August 5, 2025, certain unitholders of PIH (“PIH Rollover Holders”) exchanged their outstanding equity interests in PIH for
Concurrently with the execution of the Business Combination Agreement, EQV and the Company entered into subscription agreements on August 5, 2025 with certain investors (“PIPE Investors”) pursuant to which, among other things, the PIPE Investors subscribed for and purchased an aggregate of
Concurrently with the execution of the Business Combination Agreement, EQV, the Company and PIH entered into a Series A Preferred Securities Purchase Agreement (the “Series A Securities Purchase Agreement”) on August 5, 2025 with certain investors (the “Series A Preferred Investors”) providing for the purchase, in private placements, of an aggregate of
F-17
Certain shareholders entered into a Sponsor Letter Agreement and agreed to be bound by certain restrictions on transfer with respect to their equity interests in EQV prior to the Closing Date and waived any adjustments, including anti-dilution or similar protection, to existing conversion ratios with respect to any equity interests in EQV. The Sponsor also agreed to subject
In connection with the Business Combination and pursuant to the Securities Contribution and Transfer Agreements, the Sponsor forfeited
For the three months ended June 30, 2026 (Successor) and the period from March 4, 2026 through June 30, 2026 (Successor), the Company incurred $
Presidio Investment Holdings LLC
The following table summarizes the total consideration transferred to the PIH unitholders:
| (in thousands) | ||||
| Purchase price: | ||||
| Cash | $ | |||
| Total purchase consideration | $ | |||
F-18
The fair value of the Class A Common Stock and Opco Common Units has been determined by equating their value to the closing trading price of the Class A Common Stock, which was $
The following table summarizes the recognized amounts of identified assets acquired and liabilities assumed:
| (in thousands) | ||||
| Assets acquired | ||||
| Cash and cash equivalents | $ | |||
| Restricted cash | ||||
| Accounts receivable, oil and gas | ||||
| Accounts receivable, joint interest owners | ||||
| Derivative assets - current | ||||
| Prepaid expenses and other current assets | ||||
| Oil and natural gas properties, successful efforts | ||||
| Other property and equipment, net | ||||
| Derivative assets - noncurrent | ||||
| Right-of-use assets | ||||
| Other noncurrent assets | ||||
| Total assets acquired | $ | |||
| Liabilities assumed | ||||
| Accounts payable | ||||
| Production taxes payable | ||||
| Revenue and royalties payable | ||||
| Derivative liabilities - current | ||||
| Current portion of long-term debt | ||||
| Lease liabilities, current | ||||
| Other current liabilities | ||||
| Long-term debt, net | ||||
| Asset retirement obligations | ||||
| Derivative liabilities - noncurrent | ||||
| Deferred tax liabilities - noncurrent | ||||
| Total liabilities assumed | $ | |||
| Total net assets acquired | $ | |||
EQV Resources LLC
The following table summarizes the total consideration transferred to the EQVR unitholders:
| (in thousands) | ||||
| Purchase price: | ||||
| Cash | $ | |||
| Total purchase consideration | $ | |||
The fair value of the
F-19
The following table summarizes the recognized amounts of identified assets acquired and liabilities assumed:
| (in thousands) | ||||
| Assets acquired | ||||
| Cash and cash equivalents | $ | |||
| Accounts receivable, oil and gas | ||||
| Accounts receivable, joint interest owners | ||||
| Derivative assets - current | ||||
| Oil and natural gas properties, successful efforts | ||||
| Other property and equipment, net | ||||
| Derivative assets - noncurrent | ||||
| Total assets acquired | $ | |||
| Liabilities assumed | ||||
| Accounts payable | ||||
| Revenue and royalties payable | ||||
| Derivative liabilities - current | ||||
| Other current liabilities | ||||
| Asset retirement obligations | ||||
| Derivative liabilities - noncurrent | ||||
| Deferred tax liabilities - noncurrent | ||||
| Total liabilities assumed | $ | |||
| Total net assets acquired | $ | |||
NOTE 4. DERIVATIVE FINANCIAL INSTRUMENTS
Set forth below are the summarized amounts, terms and gross fair values of outstanding commodity derivative instruments as of June 30, 2026 (Successor):
| Volumes | Weighted Average Price | Fair Value | ||||||||||
| (in Bbls) | ($ per Bbl) | (in thousands) | ||||||||||
| Oil Swaps: | ||||||||||||
| July - December 2026 | $ | ( | ) | |||||||||
| January - December 2027 | ||||||||||||
| January - December 2028 | ( | ) | ||||||||||
| January - December 2029 | ||||||||||||
| January - December 2030 | ||||||||||||
| Thereafter | ||||||||||||
| Total | ||||||||||||
| Volumes | Weighted Average Price | Fair Value | ||||||||||
| (in MMBtu) | ($ per MMBtu) | (in thousands) | ||||||||||
| Natural Gas Swaps: | ||||||||||||
| July - December 2026 | $ | |||||||||||
| January - December 2027 | ||||||||||||
| January - December 2028 | ( | ) | ||||||||||
| January - December 2029 | ( | ) | ||||||||||
| January - December 2030 | ||||||||||||
| Thereafter | ||||||||||||
| Total | $ | |||||||||||
F-20
| Volumes | Basis Differential | Fair Value | ||||||||||
| (in MMBtu) | ($ per MMBtu) | (in thousands) | ||||||||||
| Natural Gas Basis Swaps: | ||||||||||||
| July - December 2026 | ( | ) | $ | |||||||||
| January - December 2027 | ( | ) | ||||||||||
| January - December 2028 | ( | ) | ( | ) | ||||||||
| January - December 2029 | ( | ) | ( | ) | ||||||||
| Total | ||||||||||||
| Volumes | Weighted Average Price | Fair Value | ||||||||||
| (in Bbls) | ($ per Bbl) | (in thousands) | ||||||||||
| Natural Gas Liquids Swaps: | ||||||||||||
| July - December 2026 | $ | ( | ) | |||||||||
| January - December 2027 | ( | ) | ||||||||||
| January - December 2028 | ( | ) | ||||||||||
| January - December 2029 | ( | ) | ||||||||||
| January - December 2030 | ( | ) | ||||||||||
| Thereafter | ( | ) | ||||||||||
| Total | $ | ( | ) | |||||||||
Set forth below are the summarized amounts, terms and gross fair values of outstanding commodity derivative instruments as of December 31, 2025 (Predecessor):
| Volumes | Weighted Average Price | Fair Value | ||||||||||
| (in Bbls) | ($ per Bbl) | (in thousands) | ||||||||||
| Oil Swaps: | ||||||||||||
| January - December 2026 | $ | |||||||||||
| January - December 2027 | ||||||||||||
| January - December 2028 | ( | ) | ||||||||||
| Total | $ | |||||||||||
| Volumes | Weighted Average Price | Fair Value | ||||||||||
| (in MMBtu) | ($ per MMBtu) | (in thousands) | ||||||||||
| Natural Gas Swaps: | ||||||||||||
| January - December 2026 | $ | ( | ) | |||||||||
| January - December 2027 | ( | ) | ||||||||||
| January - December 2028 | ( | ) | ||||||||||
| January - December 2029 | ( | ) | ||||||||||
| January - December 2030 | ( | ) | ||||||||||
| Thereafter | ||||||||||||
| Total | $ | ( | ) | |||||||||
| Volumes | Basis Differential | Fair Value | ||||||||||
| (in MMBtu) | ($ per MMBtu) | (in thousands) | ||||||||||
| Natural Gas Basis Swaps: | ||||||||||||
| January - December 2026 | ( | ) | $ | |||||||||
| January - December 2027 | ( | ) | ||||||||||
| Total | $ | |||||||||||
F-21
| Volumes | Weighted Average Price | Fair Value | ||||||||||
| (in Bbls) | ($ per Bbl) | (in thousands) | ||||||||||
| Natural Gas Liquids Swaps: | ||||||||||||
| January - December 2026 | $ | ( | ) | |||||||||
| January - December 2027 | ( | ) | ||||||||||
| January - December 2028 | ||||||||||||
| Total | $ | ( | ) | |||||||||
Below is a reconciliation of the gross open positions by commodity to the net open positions presented on the condensed consolidated balance sheet as of June 30, 2026 (Successor):
| Current | Noncurrent | |||||||||||||||
| (in thousands) | Assets | Liabilities | Assets | Liabilities | ||||||||||||
| Commodity | ||||||||||||||||
| Oil | $ | $ | ( | ) | $ | $ | ( | ) | ||||||||
| Gas | ( | ) | ( | ) | ||||||||||||
| NGL | ( | ) | ( | ) | ||||||||||||
| Total | $ | $ | ( | ) | $ | $ | ( | ) | ||||||||
| Effects of netting arrangements | ( | ) | ( | ) | ||||||||||||
| Total | $ | $ | ( | ) | $ | $ | ( | ) | ||||||||
Below is a reconciliation of the gross open positions by commodity to the net open positions presented on the condensed consolidated balance sheet as of December 31, 2025 (Predecessor):
| Current | Noncurrent | |||||||||||||||
| (in thousands) | Assets | Liabilities | Assets | Liabilities | ||||||||||||
| Commodity | ||||||||||||||||
| Oil | $ | $ | ( | ) | $ | $ | ( | ) | ||||||||
| Gas | ( | ) | ( | ) | ||||||||||||
| NGL | ( | ) | ( | ) | ||||||||||||
| Total | $ | $ | ( | ) | $ | $ | ( | ) | ||||||||
| Effects of netting arrangements | ( | ) | ( | ) | ||||||||||||
| Total | $ | $ | ( | ) | $ | $ | ( | ) | ||||||||
The Company has entered into derivative contracts with counterparties that the Company believes are creditworthy. All of the Company’s counterparties are investment grade and no collateral has been required. The Company’s maximum exposure to loss due to credit risk if all counterparties failed to perform is limited to the net fair value of derivative assets by counterparty as reflected on the condensed consolidated balance sheets.
For the three months ended June 30, 2026 (Successor) and the period from March 4, 2026 through June 30, 2026 (Successor), the Company incurred a realized gain of $
For the period from January 1, 2026 through March 3, 2026 (Predecessor), the Company incurred a realized loss of $
For the three and six months ended June 30, 2025 (Predecessor), the Company incurred a realized loss of $
F-22
Derivative Contract Modifications
Concurrent with the Business Combination, the Company entered into an amendment agreement with a counterparty to modify the strike price of certain natural gas derivative contracts. The Company modified the fixed price of these natural gas swap contracts with a commodity reference price of NYMEX as actively traded at the Closing Date. The Company paid $
Concurrent with the ABS III Notes issuance described in Note 7 — Debt, the Company entered into amendment agreements with two counterparties to modify the strike prices of certain existing commodity derivatives. The Company modified the fixed price of these natural gas swap contracts with a commodity reference price of NYMEX as actively traded at the Closing Date. The Company paid $
NOTE 5. PROPERTY, PLANT AND EQUIPMENT
Oil and Natural Gas Properties
The Company has recorded oil and natural gas properties of $
Other Property and Equipment
Below is a summary of other property and equipment as of June 30, 2026 and December 31, 2025:
| Successor | Predecessor | |||||||||
| (in thousands) | Useful Life (in years) | June 30, 2026 | December 31, 2025 | |||||||
| Furniture and fixtures | $ | $ | ||||||||
| Software and licenses | ||||||||||
| Computers and other hardware | ||||||||||
| Vehicles | ||||||||||
| Machinery and equipment | ||||||||||
| Leasehold improvements | ||||||||||
| Compressors | ||||||||||
| Total other property and equipment | $ | $ | ||||||||
| Accumulated depreciation and amortization | ( | ) | ( | ) | ||||||
| Total other property and equipment, net | $ | $ | ||||||||
For the three months ended June 30, 2026 (Successor), the period from March 4, 2026 through June 30, 2026 (Successor) and the period from January 1, 2026 through March 3, 2026 (Predecessor), depreciation expense related to property and equipment was $
For the three and six months ended June 30, 2025 (Predecessor), depreciation expense related to property and equipment was $
F-23
2026 Divestitures
During the three months ended June 30, 2026 (Successor) and the period from March 4, 2026 through June 30, 2026 (Successor), the Company sold leasehold and mineral interests in various oil and gas properties located in Oklahoma in exchange for $
During the period from January 1, 2026 through March 3, 2026 (Predecessor), the Company sold leasehold and mineral interests in various oil and gas properties located in Oklahoma in exchange for $
2025 Divestitures
During the three and six months ended June 30, 2025 (Predecessor), the Company sold leasehold and mineral interests in various oil and gas properties located in Oklahoma in exchange for $
NOTE 6. OTHER CURRENT LIABILITIES
As of June 30, 2026 and December 31, 2025, other current liabilities were comprised of the following:
| Successor | Predecessor | |||||||
| (in thousands) | June 30, 2026 | December 31, 2025 | ||||||
| Accrued lease operating expenses | $ | $ | ||||||
| Ad Valorem payable | ||||||||
| Accrued interest | ||||||||
| Excise tax payable | ||||||||
| Dividends payable | ||||||||
| General and administrative | ||||||||
| Other | ||||||||
| Total other current liabilities | $ | $ | ||||||
NOTE 7. DEBT
A summary of outstanding debt obligations as of June 30, 2026 and December 31, 2025 is as follows:
| Successor | ||||||||
| Interest | June 30, 2026 | |||||||
| Description | Term Range | Rate Range | (in thousands) | |||||
| ABS III Securitization | $ | |||||||
| ABS II Securitization | ||||||||
| Trail Dust Financing | ||||||||
| Citizens RBL | ||||||||
| Equipment financing obligations | ||||||||
| ABS III debt issuance costs, net | ( | ) | ||||||
| Total debt | $ | |||||||
| Current portion | ( | ) | ||||||
| Total long-term portion | $ | |||||||
F-24
| Predecessor | ||||||||
| Interest | December 31, 2025 | |||||||
| Description | Term Range | Rate Range | (in thousands) | |||||
| ABS II Securitization | $ | |||||||
| Trail Dust Financing | ||||||||
| WAB RBL | ||||||||
| Equipment financing obligations | ||||||||
| ABS II Debt issuance costs, net | ( | ) | ||||||
| Trail Dust Debt issuance costs, net | ( | ) | ||||||
| WAB RBL Debt issuance costs, net | ( | ) | ||||||
| Total debt | $ | |||||||
| Current portion | ( | ) | ||||||
| Total long-term portion | $ | |||||||
ABS III Securitization
On June 9, 2026, the Company undertook a refinancing of its outstanding asset-backed securities to optimize its capital structure and extend its debt maturity profile. As part of this effort, the Company, through Presidio Finance LLC, issued the ABS III Notes and used the proceeds to redeem the ABS II Notes in full, repay the outstanding balance under the Citizens RBL, fund derivative contract modifications, pay transaction costs, and for general corporate purposes.
The Company issued $
The ABS III Notes are subject to a series of covenants and restrictions customary for transactions of this type, including (i) that the Issuer maintains specified reserve accounts, including a liquidity reserve account targeted at six months of note interest and senior transaction fees (the initial deposit at closing was $
The ABS III Notes are also subject to customary early amortization events provided for in the indenture, including events tied to failure to maintain stated debt service coverage ratios, failure to maintain certain production metrics, certain management termination events, and event of default and the failure to repay or refinance the ABS III Notes on the applicable scheduled maturity date.
The ABS III Notes are subject to certain customary events of default, including events relating to non-payment of required interest, principal or other amounts due on or with respect to the ABS III Notes, failure to comply with covenants within certain time frames, certain bankruptcy events, breaches of specified representations and warranties, and failure of security interests to be effective.
F-25
The Company incurred debt issuance costs of $
Total interest expense related to the ABS III Notes for the period from June 9, 2026 through June 30, 2026 was $
The outstanding balance of the ABS III Notes was $
ABS II Securitization
On July 18, 2023, Presidio Investment Holdings LLC undertook a strategic initiative to optimize its capital structure and enhance financial flexibility. As part of this effort, the Company, through Presidio Finance LLC, issued ABS II debt and used the proceeds to repay the previously outstanding ABS I notes.
The Company issued $
The Company incurred debt issuance costs of $
On June 9, 2026, the Company redeemed the ABS II Notes in full using a portion of the proceeds from the ABS III Notes. The total redemption price of $
Amortization of debt premium related to the ABS II Notes, included in interest expense, for the period from March 4, 2026 through the June 9, 2026 (Successor) redemption date was $
The outstanding balance of the ABS II Notes was $
Total interest expense related to the ABS II Notes for the three and six months ended June 30, 2025 (Predecessor) was $
F-26
Trail Dust Financing
On January 31, 2024, Trail Dust LLC (“Trail Dust”), a subsidiary of Presidio Investment Holdings LLC, entered into a loan agreement with Independent Bank. Independent Bank doing business as Independent Financial has since merged with SouthState Bank. Under this agreement, the lender agreed to provide an advancing term loan facility with a maximum principal amount of $
Advances under the Trail Dust Loan are subject to borrowing base limitations, which restrict the maximum loan amounts based on the type of equipment financed. Advances for used compressors are limited to
The Trail Dust Loan bears interest at a fluctuating rate equal to the Prime Rate (as defined in the loan agreement) subject to a minimum interest rate of
The obligations under the Trail Dust Loan are secured by a first-priority lien on substantially all of Trail Dust’s assets, including all compressors acquired with loan proceeds, as well as Trail Dust’s rights under its Master Rental Agreement. Additionally, Presidio Investment Holdings LLC serves as a guarantor of the debt.
The loan agreement includes customary covenants and reporting requirements, including the obligation for Trail Dust and its guarantor, Presidio Investment Holdings LLC, to furnish quarterly financial statements to the lender.
Total interest expense related to the Trail Dust Loan for the three months ended June 30, 2026 (Successor), the period from March 4, 2026 through June 30, 2026 (Successor) and the period from January 1, 2026 through March 3, 2026 (Predecessor), was less than $
Total interest expense related to the Trail Dust Loan for the three and six months ended June 30, 2025 (Predecessor), was less than $
The outstanding balance of the Trail Dust Loan as of June 30, 2026 and December 31, 2025 was $
F-27
Secured Revolving Credit Facility
On March 4, 2026, Presidio Borrower LLC, a wholly owned subsidiary of the Company (“Presidio Borrower”), entered into a senior secured revolving credit agreement (the “Credit Agreement”) among Presidio Borrower, as borrower, Citizens Bank, N.A., as administrative agent, and the lenders from time to time party thereto. The Credit Agreement provides for, as of the closing date of the Credit Agreement, aggregate commitments of $
The Credit Agreement is guaranteed by the restricted subsidiaries of Presidio Borrower and is secured by first priority mortgages and security interest in substantially all assets of Presidio Borrower and its restricted subsidiaries.
Borrowings under the Credit Agreement may be base rate loans or secured overnight financing rate (“SOFR”) loans. Interest is payable quarterly for base rate loans and at the end of the applicable interest period for SOFR loans. SOFR loans bear interest at Term SOFR plus an applicable margin ranging from 300 to 400 basis points, depending on the percentage of the borrowing base utilized. Base rate loans bear interest at a rate per annum equal to the greatest of: (i) the prime rate announced by Citizens Bank, N.A. or its parent; (ii) the federal funds effective rate plus 50 basis points; and (iii) the Term SOFR rate for a one-month interest period plus 100 basis points, plus an applicable margin ranging from 200 to 300 basis points, depending on the percentage of the borrowing base utilized. Presidio Borrower also pays a commitment fee on unused elected commitment amounts under its facility of 50 basis points. Presidio Borrower may repay any amounts borrowed under the Credit Agreement prior to the maturity date without any premium or penalty (other than customary breakage costs).
The Credit Agreement also contains certain financial covenants, including the maintenance of the following financial ratios: (i) a current ratio, which is the ratio of Presidio Borrower’s consolidated current assets (including unused commitments under the Credit Agreement) to its consolidated current liabilities (excluding the current portion of long-term debt under the Credit Agreement), of not less than 1.00 to 1.00; and (ii) a total net leverage ratio, which is the ratio of Presidio Borrower’s Consolidated Total Net Indebtedness to Consolidated EBITDAX (each as defined in the Credit Agreement) for the prior four fiscal quarters (with Consolidated EBITDAX annualized in a customary manner for the first three quarterly reporting periods after the closing date of the Credit Agreement), of not greater than 3.00 to 1.00.
The Credit Agreement contains additional restrictive covenants that limit the ability of Presidio Borrower and its restricted subsidiaries to, among other things, incur additional indebtedness, incur additional liens, enter into mergers and acquisitions, make or declare dividends, repurchase or redeem junior debt, make investments and loans, engage in transactions with affiliates, sell assets and enter into certain hedging transactions. In addition, the Credit Agreement is subject to customary events of default, including a change in control. If an event of default occurs and is continuing, the administrative agent may or shall at the request of majority lenders accelerate any amounts outstanding and terminate lender commitments.
On June 9, 2026, in connection with the ABS refinancing described above, the Company repaid in full the $
F-28
The Company incurred debt issuance costs of $
Total interest expense related to the Citizens RBL for the three months ended June 30, 2026 (Successor) and the period from March 4, 2026 through June 30, 2026 (Successor) was $
The outstanding balance of the Citizens RBL was $
Predecessor Revolving Credit Facility
On July 2, 2025, the Predecessor, through Presidio WAB LLC as borrower and Presidio Investment Holdings LLC as guarantor, entered into a reserve-based revolving credit facility with SouthState Bank (“WAB RBL”). The facility provided for borrowings up to $
The Predecessor incurred debt issuance costs of less than $
Total interest expense related to the WAB RBL for the period from January 1, 2026 through March 3, 2026 (Predecessor) was less than $
The WAB RBL was assumed by the Company at the time of the Business Combination and was settled at the Closing. The outstanding balance of the WAB RBL as of December 31, 2025 was $
Future Maturities of Long-term Debt
The future amounts of required principal payments of long-term debt after June 30, 2026 are as follows:
| (in thousands) | ABS III | Trail Dust | ||||||
| Years Ending December 31, | ||||||||
| 2026 (remainder) | $ | $ | ||||||
| 2027 | ||||||||
| 2028 | ||||||||
| 2029 | ||||||||
| 2030 | ||||||||
| Thereafter | ||||||||
| Total | $ | $ | ||||||
F-29
NOTE 8. FAIR VALUE MEASUREMENTS
The following table sets forth the Company’s assets and liabilities which are measured at fair value on a recurring basis:
| Successor | ||||||||||||||||
| June 30, 2026 | ||||||||||||||||
| (in thousands) | Level 1 | Level 2 | Level 3 | Total | ||||||||||||
| Assets | ||||||||||||||||
| Current: | ||||||||||||||||
| Commodity derivatives | $ | $ | $ | $ | ||||||||||||
| Noncurrent: | ||||||||||||||||
| Commodity derivatives | ||||||||||||||||
| Liabilities | ||||||||||||||||
| Current: | ||||||||||||||||
| Commodity derivatives | ( | ) | ( | ) | ||||||||||||
| Noncurrent: | ||||||||||||||||
| Earnout shares | ( | ) | ( | ) | ||||||||||||
| Commodity derivatives | ( | ) | ( | ) | ||||||||||||
| Series A embedded derivative (a) | ||||||||||||||||
| Total, net | $ | $ | $ | ( | ) | $ | ||||||||||
| (a) |
| Predecessor | ||||||||||||||||
| December 31, 2025 | ||||||||||||||||
| (in thousands) | Level 1 | Level 2 | Level 3 | Total | ||||||||||||
| Assets | ||||||||||||||||
| Current: | ||||||||||||||||
| Commodity derivatives | $ | $ | $ | $ | ||||||||||||
| Noncurrent: | ||||||||||||||||
| Commodity derivatives | ||||||||||||||||
| Liabilities | ||||||||||||||||
| Current: | ||||||||||||||||
| Commodity derivatives | ( | ) | ( | ) | ||||||||||||
| Noncurrent: | ||||||||||||||||
| Commodity derivatives | ( | ) | ( | ) | ||||||||||||
| Total, net | $ | $ | ( | ) | $ | $ | ( | ) | ||||||||
All commodity derivatives recorded on the condensed consolidated balance sheets are classified within Level 2 as they are generally based on quoted prices for similar assets as determined by independent brokers. See Note 4 — Derivative Financial Instruments for further information pertaining to derivatives.
F-30
The fair value of the Earnout Shares is estimated using a Monte Carlo simulation using Level 3 fair value inputs. The Monte Carlo simulation considers daily simulated stock prices as a proxy for the Company’s daily volume-weighted average share price. The estimated equity volatility assumption is based on a blended average of asset and equity volatility measurements, respectively, of publicly traded companies within the Company’s peer group.
| Successor | Successor | |||||||
| June 30, 2026 | March 4, 2026 | |||||||
| Stock price | $ | $ | ||||||
| Risk-free interest rate | % | % | ||||||
| Expected term (in years) | ||||||||
| Expected volatility | % | % | ||||||
| Dividend yield | % | % | ||||||
The following table provides a reconciliation for the change in fair value of the Earnout Shares categorized within Level 3 of the fair value hierarchy:
| (in thousands) | Earnout Liabilities | |||
| Fair value as of March 4, 2026 | $ | |||
| Change in fair value | ||||
| Fair value as of June 30, 2026 | $ | |||
The change in fair value of the Earnout Shares resulted in other expenses of $
The initial recognition of an asset retirement obligation is determined using Level 3 fair value inputs as the Company uses an expected present value technique to measure fair value upon initial recognition of the obligation. The carrying value of the Company’s cash and cash equivalents, accounts receivable, and accounts payable approximate fair value due to the short maturity of those instruments.
NOTE 9. REDEEMABLE PREFERRED STOCK AND STOCKHOLDERS’ EQUITY (SUCCESSOR)
The Company is authorized to issue a total of
Series A Redeemable Preferred Stock
As of June 30, 2026, the Company had
F-31
The Series A Redeemable Preferred Stock is subject to customary trigger events provided for in the Series A COD, including events tied to an event of default under any debt document that accelerates indebtedness, failure to maintain a collateral ratio at or below
Dividends – Holders of Series A Redeemable Preferred Stock are entitled to receive cumulative quarterly dividends on their then-current investment amount (defined as the subscription amount plus accrued but unpaid dividends), payable on February 28, May 31, August 31, and November 30 of each year. Dividends are mandatory and accrue whether or not declared by the Board of Directors. The dividend rate is
On May 31, 2026, the Company paid $
Redemption – The redemption price of the Series A Redeemable Preferred Stock is the greater of (i) 1.25 times the aggregate subscription amount or (ii) an amount equal to a
Board of Directors / Voting – Holders of Series A Redeemable Preferred Stock, voting as a separate class, are entitled to elect one member of the Company’s Board of Directors for so long as any shares of Series A Redeemable Preferred Stock remain outstanding. Upon the occurrence and continuation of a Trigger Event, the holders of a majority of the outstanding shares of Series A Redeemable Preferred Stock have the right to appoint two additional designees to the Company’s Board of Directors. The preferred shares do not carry ordinary voting rights with respect to matters submitted to common stockholders generally, except as required by Delaware law.
Liquidation – The Series A Redeemable Preferred Stock ranks senior to the Series B Convertible Redeemable Preferred Stock, Class A Common Stock, and Class B Common Stock (the “Junior Securities”). In the event of voluntary or involuntary liquidation, dissolution, or winding up of the Company, after payment of liabilities, holders of Series A Redeemable Preferred Stock are entitled to receive their full liquidation preference, which is equal to the redemption price, from available assets before any distribution is made to holders of Junior Securities. Once paid in full, holders of Junior Securities are entitled to receive all remaining assets of the Company in accordance with their respective rights and preferences, and holders of Series A Redeemable Preferred Stock have no further claim to the Company’s assets.
Series B Convertible Redeemable Preferred Stock
As of June 30, 2026, the Company had
F-32
Conversion – Each share of Series B Convertible Redeemable Preferred Stock is convertible, at any time and from time to time, at the option of the holder, into
Dividends – Holders of Series B Convertible Redeemable Preferred Stock are entitled to receive dividends when, as, and if declared by the Board of Directors, in an amount equal to the dividends the holder would receive if the Series B Convertible Redeemable Preferred Stock had been converted into shares of Class A Common Stock immediately prior to the applicable record date (the as-converted basis). Dividends on the Series B Convertible Redeemable Preferred Stock are non-cumulative and are payable concurrently with any dividend or distribution paid to holders of Class A Common Stock, subject to the rights of Series A Redeemable Preferred Stock.
Redemption – Upon the occurrence of events defined as Fundamental Transactions (as defined in the Series B COD), some of which are not solely within the control of the Company, holders of Series B Convertible Redeemable Preferred Stock are entitled to receive the same consideration that holders of Class A Common Stock receive, calculated on an as-converted basis, and such consideration could result in the holders receiving cash in exchange for settlement of their shares. The Series B Convertible Redeemable Preferred Stock is otherwise not redeemable.
Voting – Except as otherwise required by Delaware law, holders of Series B Convertible Redeemable Preferred Stock have no voting, consent, or approval rights.
Liquidation – In the event of voluntary or involuntary liquidation, dissolution, or winding up of the Company, Series B Convertible Redeemable Preferred Stock is entitled to receive ratably, on an as-converted basis with Class A Common Stock, the assets available for distribution to the stockholders after payment of liabilities and the liquidation preference of Series A Redeemable Preferred Stock. Series B Convertible Redeemable Preferred Stock ranks pari passu to all of the Class A Common Stock.
Class A Common Stock
As of June 30, 2026, the Company had
Holders of Class A Common Stock are entitled to
On April 14, 2026, the Company’s Board of Directors declared a special cash dividend of $
Class B Common Stock
As of June 30, 2026, the Company had
The aggregate number of shares of Class B Common Stock held by any owner at any time must equal the aggregate number of Opco Common Units held by that same owner. Upon the exchange of Opco Common Units for Class A Common Stock, as further discussed in Note 3 — Business Combinations, the corresponding shares of Class B Common Stock are simultaneously cancelled and retired without the payment of additional consideration.
Holders of Class B Common Stock are entitled to
F-33
Non-controlling Interest
As further discussed in Note 3 — Business Combinations, certain unit holders of PIH elected to receive Opco Common Units representing an economic interest in the Company’s subsidiary, EQV Holdings, along with an equal number of shares of the Company’s non-economic voting Class B Common Stock, in connection with the Business Combination. Opco Common Units not owned by the Company represent and are accounted for as non-controlling interests in EQV Holdings. The non-controlling interest is presented as a separate component of stockholders’ equity on the condensed consolidated balance sheet, and the portion of net income (loss) attributable to the non-controlling interest is presented separately on the condensed consolidated statement of operations. Holders of Opco Common Units are entitled to receive pro rata distributions from EQV Holdings, if and when declared by the Company in its capacity as managing member of EQV Holdings.
The Company made distributions to non-controlling interest of $
Equity-Classified Warrants
Presidio Public and Private Placement Warrants
In connection with the Business Combination, the Company assumed
The Company was not obligated to deliver any Class A Common Stock pursuant to the exercise of a warrant and had no obligation to settle such warrant exercise unless a registration statement under the Securities Act with respect to the Class A Common Stock underlying the warrants was then effective and a prospectus relating thereto was current and available for use. No warrant was exercised and the Company was not obligated to issue shares of Class A Common Stock upon exercise of a warrant unless the Class A Common Stock issuable upon such warrant exercise had been registered, qualified or deemed to be exempt under the securities laws applicable to the jurisdiction of the registered holder of the warrant.
On March 16, 2026, the Company filed with the SEC a registration statement for the registration, under the Securities Act, of the shares of Class A Common Stock issuable upon exercise of the Presidio Public Warrants and Presidio Private Placement Warrants, which the SEC declared effective on March 23, 2026. The Company will use its commercially reasonable efforts to maintain the effectiveness of such registration statement, and a current prospectus relating thereto, until the expiration or redemption of the warrants in accordance with the provisions of the warrant agreement. In addition, if the shares of Class A Common Stock are at the time of any exercise of a warrant not listed on a national securities exchange such that they satisfy the definition of a “covered security” under Section 18(b)(1) of the Securities Act, the Company may, at its option, require holders of the Presidio Public Warrants who exercise their warrants to do so on a “cashless basis” in accordance with Section 3(a)(9) of the Securities Act and, in the event the Company elects to do so, the Company will not be required to file or maintain in effect a registration statement, but it will use its best efforts to register or qualify the shares under applicable blue sky laws to the extent an exemption is not available.
Once the warrants become exercisable, the Company may redeem the Public Warrants:
| ● | in whole and not in part; |
| ● | at a price of $ |
| ● | upon not less than 30 days’ prior written notice of redemption given after the warrants become exercisable to each warrant holder; and |
| ● | if, and only if, the closing price of the Company’s Class A Common Stock equals or exceeds $ |
F-34
The Presidio Private Placement Warrants are identical to the Presidio Public Warrants, except that the Presidio Private Placement Warrants and the Class A Common Stock shares issuable upon the exercise of the warrants are not transferable, assignable or salable until 30 days after the closing of the Business Combination, subject to certain limited exceptions. Additionally, the Presidio Private Placement Warrants are exercisable on a cashless basis and are non-redeemable.
If the Company calls the Presidio Public Warrants for redemption, management will have the option to require all holders that wish to exercise the Presidio Public Warrants to do so on a “cashless basis,” as described in the warrant agreement. The exercise price and number of shares of Class A Common Stock issuable upon exercise of the warrants may be adjusted in certain circumstances including in the event of a share dividend, or recapitalization, reorganization, merger or consolidation. However, the warrants will not be adjusted for issuances of Class A Common Stock at a price below its exercise price. Additionally, in no event will the Company be required to net cash settle the warrants.
Preferred Investor Warrants
In connection with the issuance of Series A Redeemable Preferred Stock, the Company issued warrants to the Series A Preferred Investors (“Preferred Investor Warrants”) to purchase
On March 16, 2026, the Company filed with the SEC a registration statement for the registration, under the Securities Act, of the shares of Class A Common Stock issuable upon exercise of the Preferred Investor Warrants (“Preferred Investor Warrant Shares”), which the SEC declared effective on March 23, 2026. The Company will use its commercially reasonable efforts to maintain the effectiveness of such registration statement, and a current prospectus relating thereto, until the earliest of: (i) the second anniversary of the closing of the Business Combination; (ii) the date on which the Series A Preferred Investors cease to hold any Preferred Investor Warrants or Preferred Investor Warrant Shares; or (iii) the date on which all Preferred Investor Warrant Shares may be sold by the Series A Preferred Investor under Rule 144 without the public information, volume, or manner-of-sale limitations of such rule. The Company may temporarily suspend the use of the prospectus included in such registration statement for up to 90 consecutive calendar days or 120 total calendar days in any 360-day period under certain circumstances, including where an amendment to the registration statement is required to prevent a material misstatement or omission or where use of the prospectus could materially affect a bona fide business or financing transaction of the Company.
NOTE 10. SHARE-BASED COMPENSATION (SUCCESSOR)
2026 Equity Incentive Plan
In connection with the closing of the Business Combination, the Company adopted the Presidio Production Company 2026 Equity Incentive Plan (the “Plan”). The Plan is designed to align the interests of eligible participants with those of the Company’s stockholders by providing long-term incentive compensation tied to the performance of the Company and its Class A Common Stock. The Plan authorizes the grant of stock options, stock appreciation rights, restricted stock awards, restricted stock units (“RSUs”), stock awards, and cash awards. As of June 30, 2026, only RSUs have been granted under the Plan.
The Plan authorizes the issuance of up to
F-35
Restricted Stock Units
During the period from March 4, 2026 through June 30, 2026 (Successor), the Company granted
Participants holding RSUs have no voting rights and no stockholder rights with respect to the underlying shares until the shares are issued upon settlement. However, if the Company declares and pays a dividend on its Class A Common Stock, each outstanding RSU (whether vested or unvested) will be credited with a dividend equivalent equal to the per-share dividend amount paid and such dividend equivalents are paid to participants in cash at the same time dividends are paid to holders of Class A Common Stock. As the dividends on the equity-classified RSUs are non-forfeitable and the Company accounts for forfeitures as they occur, such dividends, if any, are charged to retained earnings initially but reclassified as share-based compensation expense in the event of forfeiture.
The following table summarizes the RSU activity for the period from March 4, 2026 through June 30, 2026 (Successor):
| RSUs | Weighted-average grant date fair value | |||||||
| Unvested as of March 4, 2026 | ||||||||
| Granted | $ | |||||||
| Vested and settled | ||||||||
| Canceled/Forfeited | ( | ) | $ | |||||
| Unvested as June 30, 2026 | $ | |||||||
The Company recognized compensation expense for RSUs of $
As of June 30, 2026, unrecognized compensation expense related to unvested RSU awards was $
NOTE 11. NET INCOME (LOSS) PER SHARE (SUCCESSOR)
Basic net income (loss) per share for the three months ended June 30, 2026 and the period from March 4, 2026 through June 30, 2026 is calculated by dividing net income (loss) available to Class A common stockholders by the weighted average number of shares of Class A common stock outstanding during the period. Net income (loss) available to Class A common stockholders excludes net income (loss) attributable to non-controlling interests, dividends on Series A Redeemable Preferred Stock, dividends on Series B Convertible Redeemable Preferred Stock, dividends on unvested RSUs, and allocations of undistributed earning to participating securities. Weighted average shares outstanding includes
Unvested RSUs and Series B Convertible Redeemable Preferred Stock constitute participating securities under ASC 260. For the three months ended June 30, 2026, undistributed earnings were allocated to the participating securities under the two-class method based on their contractual rights to participate in distributions. For the period from March 4, 2026 through June 30, 2026, no losses were allocated to the participating securities under the two-class method as the securities are not contractually obligated to share in losses.
F-36
The following potential common shares were excluded from the calculation of diluted net income (loss) per share for the three months ended June 30, 2026 and the period from March 4, 2026 through June 30, 2026 because their inclusion would have been antidilutive:
| ● | the assumed exchange of EQV Holdings Common Units for Class A Common Stock; |
| ● | the assumed vesting and issuance of Class A Common Stock underlying unvested RSUs; |
| ● | the assumed exercise of Presidio Public Warrants and Presidio Private Warrants for Class A Common Stock; |
| ● | the assumed conversion of Series B Convertible Redeemable Preferred Stock into Class A Common Stock. |
The contingently returnable Earnout Shares were also excluded from the diluted net income (loss) per share calculation because the conditions for vesting would not have been satisfied if the reporting period were the end of the contingency period.
The following table summarizes the calculation of basic and diluted net income (loss) per share of Class A Common Stock:
| Successor | ||||||||
| Three Months Ended | March 4, 2026 to | |||||||
| (in thousands, except per share amounts) | June 30, 2026 | June 30, 2026 | ||||||
| Net income (loss) attributable to Presidio Production Company | $ | $ | ( | ) | ||||
| Less: Series A redeemable preferred stock dividends | ( | ) | ( | ) | ||||
| Less: Series B convertible redeemable preferred stock dividends | ( | ) | ( | ) | ||||
| Less: Unvested RSU dividends | ( | ) | ( | ) | ||||
| Less: Allocation to participating securities (two-class method) | ( | ) | ||||||
| Net income (loss) available to Class A common stockholders | $ | $ | ( | ) | ||||
| Weighted average Class A common stock outstanding: | ||||||||
| Basic | ||||||||
| Diluted | ||||||||
| Net income (loss) per Class A common stock | ||||||||
| Basic | $ | $ | ( | ) | ||||
| Diluted | $ | $ | ( | ) | ||||
NOTE 12. SEGMENT INFORMATION
The Company is managed on a consolidated basis as
The Company’s chief operating decision maker (“CODM”) is the collective .
The CODM is presented with gross revenues and revenue deductions broken out separately for review. As such, the CODM reviews gross oil sales, gross natural gas sales, and gross natural gas liquid sales separately from oil deductions, natural gas deductions, and natural gas liquid deductions as described in Note 2 — Basis of Presentation and Summary of Significant Accounting Policies. The CODM is also presented with commodity derivative gains (losses) broken out into realized gain/(loss) from derivatives and unrealized gain (loss) from derivatives as described in Note 4 — Derivative Financial Instruments.
F-37
The CODM uses consolidated net income as a measure of profitability to evaluate segment performance to allocate the appropriate resources to drive efficiencies and develop growth strategies.
Interest income for the three months ended June 30, 2026 (Successor), the period from March 4, 2026 through June 30, 2026 (Successor) and the period from January 1, 2026 through March 3, 2026 (Predecessor) was $
Interest income for the three and six months ended June 30, 2025 (Predecessor) was $
NOTE 13. INCOME TAXES
The Company recognized an income tax expense of $
The Company recognized an income tax expense of $
In calculating the provision for income taxes on an interim basis, the Company uses an estimate of the annual effective tax rate based upon currently known facts and circumstances and applies that rate to its year-to-date earnings or losses. The tax effect of discrete items, such as changes in estimates, changes in enacted tax laws or rates or tax status, and unusual or infrequently occurring events, is recognized in the interim period in which the discrete item occurs. The accounting estimates used to compute the provision for income taxes may change as new events occur, additional information is obtained or as the result of new judicial interpretations or regulatory or tax law changes. The Company’s interim effective tax rate, inclusive of any discrete items, was
Our Predecessor, PIH, was a limited liability company treated as a partnership for U.S. federal income tax purposes and, therefore, has not been subject to U.S. federal or state and local income tax at an entity level. As a result, the consolidated net income or loss in our historical financial statements for periods prior to the Business Combination does not reflect the income tax expense or benefit we would have incurred if we were subject to U.S. federal or state and local income tax at an entity level during those periods. After the Business Combination, the Company is organized in an Up-C structure in which substantially all assets and operations of PIH are held indirectly through Opco. Also on the Closing Date, the Company acquired all of the issued and outstanding equity interests of EQVR, a Delaware limited liability company, through a series of transactions, whereas EQVR was ultimately contributed down to Opco in exchange for shares of the Company. Refer to Note 3 — Business Combinations for further discussion on the EQVR Acquisition. After the Business Combination, all assets and operations of EQVR are held indirectly through Opco.
The Company holds the managing member interest in Opco. Opco is a partnership for U.S. federal income tax purposes and, as such, is not subject to U.S. federal income tax. Instead, taxable income is allocated to its members, including the Company, and any taxable income of Opco is reported in the respective tax returns of its partners. The Company is subject to U.S. federal and state and local income taxes as a corporation after the Business Combination. The Company had no activity or holdings prior to the Business Combination.
In connection with the Business Combination, the Company recorded an opening deferred tax liability of $
The Company recognizes deferred tax assets to the extent it believes these assets are more likely than not to be realized. In making such a determination, the Company considers all available positive and negative evidence, including future reversals of existing taxable temporary differences, projected future taxable income, tax planning strategies and recent results of operations. Based on these factors, we determined that the deferred tax assets are more likely than not to be realized.
As of both June 30, 2026 and December 31, 2025, there were unrecognized tax benefits and amounts accrued for interest and penalties. The Company is currently not aware of any issues under review that could result in significant payments, accruals or material deviation from its position.
F-38
NOTE 14. COMMITMENTS AND CONTINGENCIES
Litigation
In the opinion of management, any claims and legal actions that may arise, or may have arisen in the ordinary course of business will not have a material adverse effect on the Company’s consolidated financial position, results of operations, or liquidity based on the information and status of existing claims or actions as of June 30, 2026.
Environmental Remediation
Various federal, state, and local laws and regulations covering the discharge of materials into the environment, or otherwise relating to the protection of the environment, may affect the Company’s operations and the costs of its crude oil and natural gas exploration, development, and production operations. The Company does not anticipate that it will be required in the near future to expend significant amounts in relation to the condensed consolidated financial statements taken as a whole by reason of environmental laws and regulations, and appropriately no reserves have been recorded.
Casualties and Other Risks
The Company maintains coverage in various insurance programs underwritten by highly rated carriers. The Company’s policies provide for property damage and other customary coverages for the nature and scope of its operations. The Company believes it has adequate coverage, although insurance will not cover every type of loss that might occur. As a result of insurance market conditions, coverage could become significantly more costly or even unavailable.
If the Company were to incur a significant loss for which it was inadequately covered, the loss could have a material impact the results of its operations, cash flow or financial condition. Additionally, if proceeds from available insurance were not to be paid in a timely manner, the Company’s financial condition could be affected. Any event that interrupts the Company’s revenues or which causes the Company to make a significant expenditure not covered by insurance could reduce the Company’s ability to meet future financial obligations.
NOTE 15. RELATED PARTY TRANSACTIONS
Prior to the Business Combination completed on March 4, 2026, the Company was a related party of NH Presidio Investments LLC, which owned a majority interest in PIH. NH Presidio Investments LLC is majority-owned by various investment vehicles that are managed by MS Capital Partners Adviser Inc. and for which MS Energy Partners GP LP serves as general partner. Morgan Stanley is the ultimate parent of MS Capital Partners Adviser Inc. and MS Energy Partners GP LP.
From time to time, MS Energy Partners GP LP paid certain advisory expenses on behalf of PIH, creating reimbursement obligations. As of December 31, 2025, amounts due to related parties were $
Subsequent to the Business Combination, NH Presidio Investments LLC and its affiliates are no longer considered related parties.
NOTE 16. SUBSEQUENT EVENTS
In preparing the accompanying condensed consolidated financial statements, management has evaluated all subsequent events and transactions for potential recognition or disclosure through the date of filing.
On July 1, 2026, Presidio Acquisitions LLC, as borrower (the “Borrower”), and Presidio Intermediate Holding Company II LLC, as a guarantor (“PIHC II”), each a wholly-owned indirect subsidiary of the Company, entered into a Loan and Security Agreement with Goldman Sachs Bank USA (“GS”), as administrative and collateral agent, providing for a senior secured warehouse credit facility with aggregate commitments of up to $
On July 1, 2026 and July 21, 2026, the Company completed the acquisition of oil and gas properties located in Oklahoma from various parties pursuant to seven separate purchase and sale agreements dated May 7, 2026. Total consideration paid consisted of approximately $
On August 11, 2026, the Company’s Board of Directors declared a quarterly cash dividend of $
On August 7, 2026, the borrowing base under the Citizens RBL was redetermined and decreased from $
There were no other material subsequent events that required recognition or disclosure in these condensed consolidated financial statements.
F-39
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
Board of Representatives and Members
Presidio Investment Holdings LLC
Opinion on the financial statements
We have audited the accompanying consolidated balance sheets of Presidio Investment Holdings LLC (a Delaware limited liability company) and subsidiaries (the “Company”) as of December 31, 2025 and 2024, the related consolidated statements of operations, members’ deficit, and cash flows for each of the two years in the period ended December 31, 2025, and the related notes (collectively referred to as the “consolidated financial statements”). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2025 and 2024, and the results of its operations and its cash flows for each of the two years in the period ended December 31, 2025, in conformity with accounting principles generally accepted in the United States of America.
Basis for opinion
These consolidated financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s consolidated financial statements based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (“PCAOB”) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud. The Company is not required to have, nor were we engaged to perform, an audit of its internal control over financial reporting. As part of our audits we are required to obtain an understanding of internal control over financial reporting but not for the purpose of expressing an opinion on the effectiveness of the Company’s internal control over financial reporting. Accordingly, we express no such opinion.
Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion.
/s/ GRANT THORNTON LLP
We have served as the Company’s auditor since 2018.
Dallas, Texas
March 9, 2026
F-40
Presidio Investment Holdings LLC
CONSOLIDATED BALANCE SHEETS
December 31,
(in thousands)
| 2025 | 2024 | |||||||
| ASSETS | ||||||||
| Current assets | ||||||||
| Cash and cash equivalents | $ | 4,119 | $ | 88,815 | ||||
| Restricted cash | 11,222 | 13,472 | ||||||
| Accounts receivable, oil and natural gas | 16,666 | 20,094 | ||||||
| Accounts receivable, joint interest owners, net | 11,815 | 11,219 | ||||||
| Prepaid expenses and other current assets | 1,927 | 1,932 | ||||||
| Total current assets | 45,749 | 135,532 | ||||||
| Oil and natural gas properties, successful efforts method | 529,096 | 534,872 | ||||||
| Less accumulated depletion, depreciation, and amortization | (204,639 | ) | (176,221 | ) | ||||
| Oil and natural gas properties, net | 324,457 | 358,651 | ||||||
| Other property and equipment, net of accumulated depreciation of $10,090 and $7,784 | 5,457 | 6,024 | ||||||
| Right-of-use asset | 135 | 339 | ||||||
| Other noncurrent assets | 2,119 | 1,517 | ||||||
| Total assets | $ | 377,917 | $ | 502,063 | ||||
| LIABILITIES AND MEMBERS’ DEFICIT | ||||||||
| Current liabilities | ||||||||
| Accounts payable | $ | 17,706 | $ | 20,463 | ||||
| Production taxes payable | 3,188 | 3,227 | ||||||
| Revenue and royalties payable | 20,223 | 20,466 | ||||||
| Commodity derivative liabilities, current portion | 7,465 | 43,123 | ||||||
| Current portion of long-term debt | 45,363 | 45,044 | ||||||
| Current operating lease liabilities | 144 | 217 | ||||||
| Related party payable | 1,383 | 1,083 | ||||||
| Other current liabilities | 23,032 | 18,214 | ||||||
| Total current liabilities | 118,504 | 151,837 | ||||||
| Non-current liabilities | ||||||||
| Long-term debt, net (Note G) | 225,143 | 264,640 | ||||||
| Asset retirement obligations | 59,519 | 66,232 | ||||||
| Non-current operating lease liabilities | - | 135 | ||||||
| Commodity derivative liabilities | 6,734 | 47,077 | ||||||
| Commitments and contingencies (Note J) | ||||||||
| Members’ deficit | (31,983 | ) | (27,858 | ) | ||||
| Total liabilities and members’ deficit | $ | 377,917 | $ | 502,063 | ||||
The accompanying notes are an integral part of these consolidated financial statements.
F-41
Presidio Investment Holdings LLC
CONSOLIDATED STATEMENTS OF OPERATIONS
Years ended December 31,
(in thousands, except share and per share data)
| 2025 | 2024 | |||||||
| Revenue | ||||||||
| Oil sales | $ | 81,640 | $ | 106,854 | ||||
| Natural gas sales | 50,309 | 26,478 | ||||||
| Natural gas liquids sales | 45,864 | 56,410 | ||||||
| Field services revenue | 1,243 | 2,474 | ||||||
| Total revenues | 179,056 | 192,216 | ||||||
| Expenses | ||||||||
| Lease operating expenses | 73,016 | 70,702 | ||||||
| Production taxes | 9,795 | 10,347 | ||||||
| Ad valorem taxes | 5,500 | 5,236 | ||||||
| Depletion, oil and natural gas properties | 28,418 | 34,153 | ||||||
| Depreciation and amortization, other property and equipment | 3,279 | 3,032 | ||||||
| Accretion of asset retirement obligation | 4,134 | 3,765 | ||||||
| General and administrative | 28,372 | 7,995 | ||||||
| Cost of field services revenue | 823 | 1,960 | ||||||
| Gain on sale of assets | (8,455 | ) | (85,573 | ) | ||||
| Total operating expenses | 144,882 | 51,617 | ||||||
| Income from operations | 34,174 | 140,599 | ||||||
| Commodity derivative gains (losses), net | 47,161 | (12,465 | ) | |||||
| Other income | 23 | 150 | ||||||
| Interest expense | (24,491 | ) | (27,153 | ) | ||||
| Net income before income taxes | 56,867 | 101,131 | ||||||
| Income tax expense | 992 | 233 | ||||||
| NET INCOME | $ | 55,875 | $ | 100,898 | ||||
| Net income per Class A unit | $ | 482.60 | $ | 871.48 | ||||
| Class A units outstanding, basic and diluted | 115,778 | 115,778 | ||||||
| Class A weighted-average units outstanding, basic and diluted | 115,778 | 115,778 | ||||||
The accompanying notes are an integral part of these consolidated financial statements.
F-42
Presidio Investment Holdings LLC
CONSOLIDATED STATEMENTS OF MEMBERS’ DEFICIT
Years ended December 31, 2025 and 2024
(in thousands)
| Members’ Deficit | ||||
| Balance, December 31, 2023 | $ | (128,756 | ) | |
| Net income | 100,898 | |||
| Balance, December 31, 2024 | $ | (27,858 | ) | |
| Capital distributions | (60,000 | ) | ||
| Net income | 55,875 | |||
| Balance, December 31, 2025 | $ | (31,983 | ) | |
The accompanying notes are an integral part of these consolidated financial statements.
F-43
Presidio Investment Holdings LLC
CONSOLIDATED STATEMENTS OF CASH FLOWS
Years ended December 31,
(in thousands)
| 2025 | 2024 | |||||||
| Cash flows from operating activities: | ||||||||
| Net income | $ | 55,875 | $ | 100,898 | ||||
| Adjustments to reconcile net income to net cash provided by operating activities: | ||||||||
| Depletion of oil and natural gas properties | 28,418 | 34,153 | ||||||
| Depreciation of other property and equipment | 3,279 | 3,032 | ||||||
| Accretion of asset retirement obligation | 4,134 | 3,765 | ||||||
| ARO liabilities settled | (863 | ) | (291 | ) | ||||
| Amortization of debt issuance costs | 1,693 | 1,984 | ||||||
| Unrealized gain from derivative transactions | (76,001 | ) | (2,549 | ) | ||||
| Credit losses | 1,433 | — | ||||||
| Gain on sale of assets | (8,455 | ) | (85,573 | ) | ||||
| Other, net | (4 | ) | 733 | |||||
| Changes in operating assets and liabilities: | ||||||||
| Accounts receivable | 1,399 | (5,967 | ) | |||||
| Prepaid expenses and other current assets | 5 | (1,066 | ) | |||||
| Accounts payable | (2,757 | ) | 11,514 | |||||
| Related party payable | 300 | (467 | ) | |||||
| Other current liabilities | 4,644 | (6,593 | ) | |||||
| Net cash provided by operating activities | 13,100 | 53,573 | ||||||
| Cash flows from investing activities: | ||||||||
| Capital expenditures for oil and natural gas properties | (4,208 | ) | (3,493 | ) | ||||
| Purchase of property and equipment | (2,729 | ) | (3,082 | ) | ||||
| Proceeds from sale of assets | 8,455 | 87,013 | ||||||
| Net cash provided by investing activities | 1,518 | 80,438 | ||||||
| Cash flows from financing activities: | ||||||||
| Proceeds from Trail Dust debt | 343 | 2,451 | ||||||
| Proceeds from WAB RBL debt | 3,500 | — | ||||||
| Repayment of ABS II debt | (44,013 | ) | (55,957 | ) | ||||
| Repayment of finance lease liabilities | (1,341 | ) | (1,024 | ) | ||||
| Member distributions | (60,000 | ) | — | |||||
| Deferred loan costs | (53 | ) | (22 | ) | ||||
| Net cash used in financing activities | (101,564 | ) | (54,552 | ) | ||||
| NET INCREASE (DECREASE) IN CASH, CASH EQUIVALENTS, AND RESTRICTED CASH | (86,946 | ) | 79,459 | |||||
| Cash, cash equivalents, and restricted cash, beginning of period | 102,287 | 22,828 | ||||||
| Cash, cash equivalents, and restricted cash, end of period | $ | 15,341 | $ | 102,287 | ||||
| Supplemental cash flow information: | ||||||||
| Revisions to asset retirement obligations | $ | 303 | $ | (18,891 | ) | |||
| Reduction of AROs related to divested properties | $ | (10,609 | ) | $ | 0 | |||
| Cash paid for interest | $ | 24,082 | $ | 27,782 | ||||
| Cash paid for amounts included in the measurement of lease liabilities: | ||||||||
| Operating cash flows from operating leases | $ | 246 | $ | 240 | ||||
| Noncash activities: | ||||||||
| Lease assets obtained in exchange for finance lease liabilities | $ | 693 | $ | 373 | ||||
The accompanying notes are an integral part of these consolidated financial statements.
F-44
Presidio Investment Holdings LLC
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
December 31, 2025 and 2024
(Dollar amounts in thousands, except as separately indicated)
NOTE A – ORGANIZATION AND NATURE OF BUSINESS
Presidio Investment Holdings LLC (together with its consolidated subsidiaries, “Company” or “Presidio”), a Delaware limited liability company, was formed on March 29, 2018. The Company was formed by capital contributions from NH Presidio Investments LLC, and certain members of management from the Company. The accompanying consolidated financial statements also include the accounts of wholly owned subsidiaries Presidio Intermediate Holding Company LLC, Presidio Holding Company LLC, Presidio Petroleum LLC, Presidio MPO LLC, Presidio WAB LLC, Presidio Petroleum Operating LLC, Presidio Employee Holdings Co. LLC, Presidio Employee Co. LLC, and Presidio Finance LLC.
Presidio Finance LLC was formed as a limited-purpose, bankruptcy-remote, wholly-owned subsidiary of Presidio Investment Holdings LLC to effectuate the closing and issuance of asset-backed securities as discussed in Note G.
The Company’s principal business is oil and natural gas exploration and production with operations primarily in Texas and Oklahoma. Presidio is an independent energy company focused on the acquisition and subsequent application of engineering efficiency principles to optimize the output of existing properties.
NOTE B – SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES
Basis of Accounting
The consolidated financial statements include the Company’s accounts and the accounts of its consolidated subsidiaries. All intercompany transactions have been eliminated in consolidation. The consolidated financial statements were prepared in accordance with accounting principles generally accepted in the United States of America (“GAAP”).
Use of Estimates
The preparation of financial statements in conformity with GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. Actual results could differ from these estimates. Additionally, the prices received for crude oil, natural gas, and natural gas liquids (“NGL”) production can heavily influence our assumptions, judgments and estimates, and continued volatility of crude oil and natural gas prices could have a significant impact on our estimates.
The Company’s financial statements are based on a number of significant estimates including oil and natural gas reserve quantities that are the basis for the calculations of depletion and impairment of oil and natural gas properties, as well as the estimate of asset retirement obligations. The Company’s oil and natural gas reserves estimates, which are inherently imprecise, are prepared in accordance with guidelines established by the Securities and Exchange Commission (“SEC”) and accepted petroleum engineering and evaluation principles. Other significant estimates include, but are not limited to, accrued revenues, which typically include one to two months of production activity as an estimate in our period end financial statements and expenses incurred but not yet invoiced by our vendors and service providers at period end.
Cash and Cash Equivalents
The Company considers all highly liquid investments with original maturities of three months or less to be cash equivalents. The Company had no cash equivalents as of December 31, 2025 and 2024.
F-45
Restricted Cash
At the closing date of the ABS II securitization transaction (see Note G), the Company was required to deposit $15.7 million into a separate Liquidity Reserve account. At each note payment date, a portion of the Liquidity Reserve account balance is used to fund the priority of payments as required by the securitized note agreements as long as the balance exceeds the expected note interest for the six payment dates following such payment date for controlling securities, and senior transaction fees. The account is also used to fund the required principal and interest payments associated with the ABS debt if available funds are insufficient. Following the payment in full of the aggregate outstanding amount of the Notes and of all other amounts owed, any amount remaining on deposit in the Liquidity Reserve Account shall be distributed back to the Company.
The following table provides a reconciliation of cash, cash equivalents and restricted cash reported within the consolidated balance sheets as of the years ended December 31:
| (in thousands) | 2025 | 2024 | ||||||
| Cash and cash equivalents | $ | 4,119 | $ | 88,815 | ||||
| Restricted cash | 11,222 | 13,472 | ||||||
| Total cash, cash equivalents, and restricted cash presented in the statement of cash flows | $ | 15,341 | $ | 102,287 | ||||
Concentrations of Credit Risk
Financial instruments that potentially subject the Company to a concentration of credit risk consist principally of cash and accounts receivable. The Company maintains deposits at financial institutions, which at times may exceed amounts covered by insurance provided by the U.S. Federal Deposit Insurance Corporation (“FDIC”). The Company has not experienced any losses related to amounts in excess of FDIC limits and believes the counter party risks are minimal based on the reputation and history of the institutions in which the funds are deposited and held.
During 2025, oil, natural gas and NGL revenues from four purchasers totaled approximately 27%, 13%, 11%, and 10% of gross oil, natural gas and NGL revenues. These significant customers’ accounts receivable balances totaled approximately 33%, 11%, 11%, and 10% of oil and natural gas receivables as of December 31, 2025. During 2024, oil, natural gas and NGL revenues from four purchasers totaled approximately 33%, 11%, 11%, and 8% of gross oil, natural gas and NGL revenues. These significant customers’ accounts receivable balances totaled approximately 40%, 13%, 7%, and 7% of oil and natural gas receivables as of December 31, 2024.
No other customer balance represented greater than 10% of total accounts receivable as of December 31, 2025 and 2024. We believe that sufficient alternative purchasers exist for the Company’s oil, natural gas and NGL production and that the loss of any single purchaser is not considered a significant interruption or business risk to the Company.
Accounts Receivable
The Company sells oil and natural gas to various customers. Oil and natural gas sales receivables related to these operations are generally unsecured and most payments for production are received within three months after the production date. Joint interest receivables are generally secured pursuant to the operating agreement between the operator and the joint interest owner. The Company regularly evaluates the collectability of joint interest receivables, including an assessment of expected credit losses. When appropriate based on credit risk considerations, the Company has the ability to settle receivables through netting of anticipated future production revenues. Accounts receivable amounts due from joint interest owners are stated net of an allowance for credit losses.
During the year ended December 31, 2025, the Company changed its estimates of the allowance for credit losses related to its joint interest receivables, primarily based on a deterioration in the aging profile compared to prior years indicating an increased risk of non-collection and probable credit loss. Accordingly, the Company’s revised methodology establishes allowances for credit losses by applying an aged-based loss-rate to estimate expected lifetime credit losses on its joint interest receivables. This change in estimate resulted in an increase to the credit loss allowance on joint interest receivables of $1.4 million for the year ended December 31, 2025. There were no write-offs of joint interest receivables during the years ended December 31, 2025 and December 31, 2024.
F-46
Fair Value of Financial Instruments
Cash and cash equivalents, accounts receivable, and accounts payable approximate fair value due to the short maturity of those instruments.
Derivative Activities
The Company has entered into derivative instruments to mitigate a portion of its exposure to market changes in hydrocarbon prices and basis differentials. Swap instruments require a sale of the hedged commodity at a fixed price and a purchase at a floating market price, as defined in each instrument, to a counterparty. The Company recognizes all price risk management instruments as either assets or liabilities measured at fair value. The Company has presented the fair value of derivative assets and liabilities on a net basis by counterparty in the accompanying consolidated balance sheet where the right of offset exists.
The ABS II securitization transaction included certain hedging requirements. At the close date of the ABS II securitization transaction, the Company was required to hedge 85% of the projected production of natural gas, NGLs, and oil following the close date for eight years, four years, and five years, respectively. Natural gas basis differential swaps are required to be hedged 85% for three years following the close date. These initial hedging requirements have been satisfied. Following the third anniversary of the ABS II securitization closing date, the Company shall maintain at all times 24 months of commodity hedges in an amount not less than 85% of the projected production of oil, natural gas and NGLs until the earlier of (x) the Final Scheduled Payment Date or (y) the redemption of the Notes.
The Company has not designated any price risk management instruments as fair value or cash flow hedges during the years ended December 31, 2025 and 2024.
Oil and Natural Gas Properties
The Company utilizes the successful efforts method of accounting for its oil and natural gas properties. Under this method, costs of acquiring properties, drilling successful exploration wells, development costs, and workover costs result in additions to proved properties that are capitalized. The costs of exploratory wells are initially capitalized pending a determination of whether proved reserves have been found. At the completion of drilling activities, the costs of exploratory wells remain capitalized if the determination is made that proved reserves have been found. If no proved reserves have been found, the costs of each of the related exploratory wells are charged to expense. In some cases, a determination of proved reserves cannot be made at the completion of drilling, requiring additional testing and evaluation of the wells. The costs of such exploratory wells are expensed if a determination of proved reserves has not been made within a twelve-month period after drilling is complete. Exploration costs such as geological, geophysical and seismic costs are expensed as incurred.
The capitalized costs of proved properties are depleted using the unit-of-production method based on proved developed or total proved reserves as applicable. Costs of significant non-producing properties, wells in the process of being drilled and prepaid development costs are excluded from depletion until proved reserves are established or, if unsuccessful, impairment is determined.
Producing property is considered impaired when the carrying cost of property exceeds its undiscounted future net cash flows. When a property is impaired the carrying value is reduced to the discounted future net cash flows and an impairment charge of the difference between cost and discounted future net cash flows is recorded. Non-producing properties are considered impaired when the Company considers it likely that the associated leasehold will expire without plans to renew or extend the lease.
Other Property and Equipment
Other property and equipment are carried at cost less accumulated depreciation. Major renovations and improvements are capitalized while expenditures for maintenance and repairs are expensed as incurred. Upon sale or abandonment, the cost of the equipment and related accumulated depreciation are removed from the accounts and any gain or loss is recognized. Depreciation is calculated using the straight-line method over the estimated useful lives of the various assets. See Note E.
F-47
Impairment of Long-Lived Assets
The carrying value of proved oil and natural gas properties, salt water disposal wells and related facilities, and other property and equipment is periodically evaluated for impairment whenever events or changes in circumstances indicate that the carrying amount of an asset may not be recoverable. When it is determined that the estimated future net cash flows of an asset will not be sufficient to recover its carrying amount, an impairment loss must be recorded to reduce the carrying amount to its estimated fair value.
Under FASB ASC Topic 360, the Company evaluates impairment of proved and unproved oil and natural gas properties based on expected future net cash flows from the asset group. As the Company’s properties are managed and evaluated as a single field, impairment testing is performed on that basis. No impairment was recorded during the years ended December 31, 2025 and 2024.
Leases
The Company leases office space and vehicles. Right-of-use assets and lease liabilities are initially recorded at the commencement date based on the present value of lease payments over the lease term. The Company uses its incremental borrowing rate to discount future lease payments. Certain leases contain variable costs above the minimum required payments and are not included in the right-of-use assets or lease liabilities. Options to extend or terminate a lease are included in the lease term when it is reasonably certain the Company will exercise that option. For operating leases, lease cost is recognized on a straight-line basis over the term of the lease. Leases with an initial term of 12 months or less are not included on the consolidated balance sheet. The Company elected a practical expedient to not separate non-lease components from lease components for office space leases. The Company did not elect this practical expedient for vehicle leases. See Note I for further lease disclosures.
Asset Retirement Obligations
Asset retirement obligations relate to the future costs associated with the plugging, dismantlement, remediation, and abandonment (“P&A”) of oil and natural gas wells and locations. Estimates are based on projected remaining lives of those wells based on reserve estimates and internal estimates of the future cost to P&A the wells at the end of their remaining lives. The Company records the discounted present value of those anticipated costs as its asset retirement obligation liability.
Future periodic accretion of the discount on asset retirement obligations will be recorded as an expense in the accompanying consolidated statements of operations. See Note C for further discussion of the Company’s asset retirement obligations.
Revenue Recognition
Upstream Revenues
The Company disaggregates revenues from contracts with customers by type of commodity. Upstream revenues include the sale of oil, natural gas, and NGL production which are recognized at a point in time when control is transferred to the purchaser upon delivery of contract-specified production volumes at a specified point. The transaction price used to recognize revenue is a function of the contract billing terms. Revenue is invoiced, if required, by calendar month based on volumes at contractually based rates with payment typically received within 30 days of the end of the production month. Taxes assessed by governmental authorities on oil, natural gas and NGL sales are presented separately from such revenues in the accompanying consolidated statements of operations.
The Company also evaluates its contracts for the principal/agent provisions. If the Company is determined to be the principal, it would recognize revenue at the gross purchase price and record an expense for certain fees charged by the customer (such as transportation and fractionation fees) incurred prior to the transfer of control, as the Company would still have control of the product when these activities take place. Alternatively, when the Company is determined to be the agent, it recognizes the revenues based on the net price received from the purchaser, as control is determined to have transferred prior to the activities. During this evaluation, the Company concluded that it transfers control of its produced oil, natural gas and NGLs to the customer prior to the performance of any gathering, transportation or midstream processing activities being performed. Accordingly, revenue is recognized based on the net proceeds received from the purchaser, which represents the sales price net of gathering, transportation, and other similar midstream service deductions incurred after control of the product has transferred to the purchaser.
F-48
Oil Sales
The Company sells its crude oil production at the wellhead for a contractually-specified index price, net of pricing differentials. The Company recognizes revenue when control transfers to the purchaser at the delivery point based on the price received from the purchaser. Oil revenues are recorded net of any third-party transportation fees and other applicable differentials in the Company’s consolidated statements of operations.
Natural Gas and NGL Sales
Under the Company’s natural gas processing contracts, natural gas is delivered to a midstream processing entity at the wellhead or the inlet of the midstream processing entity’s system. The midstream processing entity gathers and processes the natural gas and remits proceeds for the resulting sales of NGLs and residue gas. The Company has determined that it is the agent in these transactions and recognizes revenue on a net basis, with transportation, gathering, processing, treating and compression fees as a reduction to revenues in the consolidated statements of operations.
Satisfaction of Performance Obligation and Revenue Recognition
Because the Company has a right to consideration from its customers in amounts that correspond directly to the value that the customer receives from the performance completed on each contract, the Company recognizes revenue for sales at the time the crude oil, natural gas, or NGLs are delivered at a fixed or determinable price.
Transaction Price Allocated to Remaining Performance Obligations
The Company’s upstream product sales contracts do not originate until production occurs and, therefore, are not considered to exist beyond each days’ production. Therefore, there are no remaining performance obligations under any of its product sales contracts.
Under the Company’s revenue agreements, each delivery generally represents a separate performance obligation; therefore, future volumes delivered are wholly unsatisfied and disclosure of the transaction price allocated to remaining performance obligations it not required.
Contract Balances
Aside from accounts receivable attributable to oil and natural gas sales, the Company has not recognized any contract assets as of December 31, 2025 or 2024.
The opening balance of accounts receivable attributable to oil and natural gas sales was $13.5 million as of January 1, 2024 and $20.1 million as of January 1, 2025.
Prior-period Performance Obligations
The Company records revenue in the month production is delivered to the purchaser. However, purchaser and settlement statements for certain natural gas and NGL sales may not be received for 30 to 90 days after the date production is delivered. At the end of each month, the Company estimates the amount of production that was delivered to the purchaser and the price that will be received for the sale of the product. Variances between estimates and the actual amounts received, if any, are recorded in the month payment is received from the purchaser. For the years ended December 31, 2025 and 2024 revenue recognized in the reporting period related to performance obligations satisfied in prior reporting periods was not material. The Company believes that the pricing provisions of its oil, natural gas and NGL contracts are customary in the industry.
F-49
Below is a summary of the gross revenues and costs that comprise the net revenues recognized on the consolidated statements of operations for the years ended December 31:
| (in thousands) | 2025 | 2024 | ||||||
| Oil sales, gross | $ | 81,771 | $ | 107,023 | ||||
| Natural gas sales, gross | 82,136 | 60,170 | ||||||
| Natural gas liquids sales, gross | 46,010 | 56,592 | ||||||
| Total oil, natural gas, and natural gas liquids sales, gross | $ | 209,917 | $ | 223,785 | ||||
| Oil deductions | $ | 131 | $ | 169 | ||||
| Natural gas deductions | 31,827 | 33,692 | ||||||
| Natural gas liquids deductions | 146 | 182 | ||||||
| Total oil, natural gas, and natural gas liquids deductions | $ | 32,104 | $ | 34,043 | ||||
| Total oil, natural gas, and natural gas liquids sales, net | $ | 177,813 | $ | 189,742 | ||||
Field Services Revenues
The Company provides various field services for the primary purpose of supporting its field operations. When the Company offers these services to third party customers, including its third-party working interest partners, it generates supplemental, other revenues. These services primarily include rental compression, oilfield construction and reclamation, emissions surveying, and sales of emissions reduction equipment.
Revenue from rental compression is recognized as earned in the month the work is performed in accordance with the contractual obligations. Revenue from oilfield construction and reclamation is recognized each month based on a time and materials basis. Revenue from emission surveying is recognized at the point in time when the service is completed, and the customer has accepted the work performed. Revenue from the sale of emissions reduction equipment is recognized upon delivery.
Fair Value Measurement
The Company utilizes a fair value hierarchy to categorize its assets and liabilities based on inputs to the valuation techniques used to measure fair value. The hierarchy gives the highest priority to unadjusted quoted prices in active markets for identical assets or liabilities (Level 1 measurements) and lowest priority to unobservable inputs (Level 3 measurements). The three levels of the fair value hierarchy are described below:
| Level 1 - | Inputs to the valuation methodology are unadjusted quoted prices for identical assets or liabilities in active markets that the Company has the ability to access. |
| Level 2 - | Inputs to the valuation methodology include: |
| ● | Quoted prices for similar assets or liabilities in active markets; |
| ● | Quoted prices for identical or similar assets or liabilities in inactive markets; |
| ● | Inputs other than quoted prices that are observable for the asset or liability; |
| ● | Inputs that are derived principally from or corroborated by observable market data by correlation or other means. |
If the asset or liability has a specified (contractual) term, the Level 2 input must be observable for substantially the full term of the asset or liability.
| Level 3 - | Inputs to the valuation methodology are unobservable and significant to the fair value measurements. |
F-50
Financial assets and liabilities are classified based on the lowest level of input that is significant to the fair value measurement. As of December 31, 2025 and 2024, all price risk management assets and liabilities recorded on the consolidated balance sheets are classified within Level 2 as they are generally based on quoted prices for similar assets as determined by independent brokers. See Note D for further information pertaining to derivatives.
The initial recognition of an asset retirement obligation is determined using Level 3 fair value inputs as the Company uses an expected present value technique to measure fair value upon initial recognition of the obligation. See Note C for the summary of changes of the asset retirement obligations for the years ended December 31, 2025 and 2024.
The following table sets forth the Company’s gross assets and liabilities which are measured at fair value on a recurring basis by level within the fair value hierarchy:
| (in thousands) | December 31, 2025 | |||||||||||||||
| Level 1 | Level 2 | Level 3 | Total | |||||||||||||
| Assets | ||||||||||||||||
| Current: | ||||||||||||||||
| Commodity derivatives | $ | - | $ | 9,660 | $ | - | $ | 9,660 | ||||||||
| Noncurrent: | ||||||||||||||||
| Commodity derivatives | - | 6,810 | - | 6,810 | ||||||||||||
| Liabilities | ||||||||||||||||
| Current: | ||||||||||||||||
| Commodity derivatives | $ | - | $ | (17,125 | ) | $ | - | (17,125 | ) | |||||||
| Noncurrent: | ||||||||||||||||
| Commodity derivatives | - | (13,544 | ) | - | (13,544 | ) | ||||||||||
| Net derivative instruments | $ | - | $ | (14,199 | ) | $ | - | $ | (14,199 | ) | ||||||
| (in thousands) | December 31, 2024 | |||||||||||||||
| Level 1 | Level 2 | Level 3 | Total | |||||||||||||
| Assets | ||||||||||||||||
| Current: | ||||||||||||||||
| Commodity derivatives | $ | - | $ | 3,725 | $ | - | $ | 3,725 | ||||||||
| Noncurrent: | ||||||||||||||||
| Commodity derivatives | - | 4,025 | - | 4,025 | ||||||||||||
| Liabilities | ||||||||||||||||
| Current: | ||||||||||||||||
| Commodity derivatives | $ | - | $ | (46,848 | ) | $ | - | (46,848 | ) | |||||||
| Noncurrent: | ||||||||||||||||
| Commodity derivatives | - | (51,102 | ) | - | (51,102 | ) | ||||||||||
| Net derivative instruments | $ | - | $ | (90,200 | ) | $ | - | $ | (90,200 | ) | ||||||
General and Administrative
General and administrative (“G&A”) expenses primarily consist of employee compensation and related benefits, professional services, and other corporate overhead costs incurred in the normal course of business. Compensation and benefits represent the largest component of G&A. For the year ended December 31, 2025, a non-recurring compensation expense of $15.0 million related to incentive unit distributions was recognized. No non-recurring compensation expense related to incentive unit distributions was recognized for the year ended December 31, 2024.
F-51
In addition, the Company provides administrative services to non-operated working interest owners under Council of Petroleum Accountants Societies (“COPAS”) joint operating agreements. Reimbursements received for such services are recorded as income and presented as an offset to G&A expenses in the consolidated statements of operations.
Income Taxes
The Company is organized as a limited liability company and taxed as a partnership for federal income tax purposes. As a result, income or losses are taxable or deductible to the member rather than at the Company level; accordingly, no provision has been made for federal income taxes in the accompanying consolidated financial statements. In certain instances, the Company is subject to state taxes on income arising in or derived from the state tax jurisdictions in which it operates.
State income tax positions are evaluated in a two-step process. The Company first determines whether it is more likely than not that a tax position will be sustained upon examination. If a tax position meets the more likely than not threshold, it is then measured to determine the amount of expense to record in the consolidated financial statements. The tax expense recorded would equal the largest amount of expense related to the outcome that is 50% or greater likely to occur. The Company classifies any potential accrued interest recognized on an underpayment of income taxes as interest expense and classifies any statutory penalties recognized on a tax position taken as operating expense.
Management of the Company has not taken a tax position that, if challenged, would be expected to have a material effect on the financial statements as of or for the years ended December 31, 2025 or 2024.
The Company did not incur any penalties or interest related to its state tax returns during the years December 31, 2025 and December 31, 2024.
Earnings (Loss) Per Share
Basic earnings (loss) per share are computed by dividing net income (loss) by the weighted-average number of Class A units outstanding during the year. Diluted earnings (loss) per share are calculated to give effect to potentially issuable dilutive common shares. The Company did not have additional instruments or other substantive classes of equity to create a dilutive effect on earnings per share as of the years ended December 31, 2025 and December 31, 2024.
Recently issued and adopted accounting pronouncements
In March 2024, the FASB issued ASU 2024-01, Compensation — Stock Compensation: Scope Application of Profits Interest and Similar Awards (Topic 718), which clarifies how an entity determines whether a profits interest or similar award is within the scope of ASC 718 or under other applicable guidance. This update provides illustrative examples that are intended to improve the overall clarity and reduce complexity in interpreting the guidance for profit interest awards. The guidance was effective for fiscal periods beginning after December 15, 2024, and resulted in no impact to the consolidated financial statements for all periods presented. See Note H for additional information on the Company’s awards within scope of ASC 718.
Recently issued accounting pronouncements not yet adopted
In November 2024, the FASB issued ASU 2024-03, Income Statement – Reporting Comprehensive Income – Expense Disaggregation Disclosures (“Subtopic 220-40”), which expands disclosures around a public entity’s costs and expenses of specific items (i.e., employee compensation, DD&A), requires the inclusion of amounts that are required to be disclosed under GAAP in the same disclosure as other disaggregation requirements, requires qualitative descriptions of amounts remaining in expense captions that are not separately disaggregated quantitatively, and requires disclosure of total selling expenses, and in annual periods, the definition of selling expenses. The amendment does not change or remove existing disclosure requirements. The amendment is effective for fiscal years beginning after December 15, 2026, and interim periods with fiscal years beginning after December 15, 2027. Early adoption is permitted, and the amendment can be adopted prospectively or retrospectively to any or all periods presented in the financial statements. The Company has not early adopted the standard and is currently assessing the effect that ASU 2024-03 will have on its disclosures.
F-52
NOTE C - ASSET RETIREMENT OBLIGATIONS
The Company’s asset retirement obligations represent the estimated present value of the estimated cash flows the Company will incur to plug, abandon and remediate its producing properties at the end of their productive lives, in accordance with applicable state laws. Market risk premiums associated with asset retirement obligations are estimated to reflect the Company’s credit-adjusted risk-free rate that is utilized in the calculations of asset retirement obligations.
The Company’s asset retirement obligation transactions during the years ended December 31, 2025 and 2024 are summarized in the table below.
| (in thousands) | 2025 | 2024 | ||||||
| Asset retirement obligations at beginning of year | $ | 66,232 | $ | 81,287 | ||||
| Additions to asset retirement obligations | 322 | 362 | ||||||
| Revisions to asset retirement obligations | 303 | (18,891 | ) | |||||
| Reduction of AROs related to divested properties | (10,609 | ) | - | |||||
| Accretion expense | 4,134 | 3,765 | ||||||
| ARO liability settled upon plugging and abandoning wells | (863 | ) | (291 | ) | ||||
| Asset retirement obligations at end of year | $ | 59,519 | $ | 66,232 | ||||
As of December 31, 2025, we performed normal revisions to our asset retirement obligations which resulted in a $0.3 million increase in the liability. The revisions were primarily attributed to estimated timing of abandonment.
As of December 31, 2024, we performed normal revisions to our asset retirement obligations which resulted in an $18.9 million decrease in the liability. The revisions were due to cost revisions based on our recent asset retirement experiences and due to revisions attributed to timing.
NOTE D - DERIVATIVE ACTIVITIES
Set forth below are the summarized amounts, terms and gross fair values of outstanding commodity derivative instruments as of December 31, 2025 (in thousands):
| Weighted | ||||||||||||
| Average Strike | ||||||||||||
| Total Volumes | Price | |||||||||||
| Description and Production Period | (Barrels) | (Per Barrel) | Fair Value | |||||||||
| Oil Swaps: | ||||||||||||
| January – December 2026 | 990 | $ | 57.45 | $ | 395 | |||||||
| January – December 2027 | 902 | $ | 58.22 | $ | 698 | |||||||
| January – December 2028 | 422 | $ | 56.67 | $ | (662 | ) | ||||||
F-53
| Weighted | ||||||||||||
| Average Strike | ||||||||||||
| Total Volumes | Price | |||||||||||
| Description and Production Period | (Mmbtu) | (Per Mmbtu) | Fair Value | |||||||||
| Natural Gas Swaps: | ||||||||||||
| January – December 2026 | 21,071 | $ | 3.19 | $ | (11,117 | ) | ||||||
| January – December 2027 | 19,133 | $ | 3.68 | $ | (3,676 | ) | ||||||
| January – December 2028 | 17,664 | $ | 3.57 | $ | (2,267 | ) | ||||||
| January – December 2029 | 16,454 | $ | 3.55 | $ | (899 | ) | ||||||
| January – December 2030 | 15,340 | $ | 3.55 | $ | (783 | ) | ||||||
| Thereafter | 7,314 | $ | 3.63 | $ | 852 | |||||||
| Basis | ||||||||||||
| Total Volumes | Differential | |||||||||||
| Description and Production Period | (Mmbtu) | (Per Mmbtu) | Fair Value | |||||||||
| Natural Gas Basis Swaps: | ||||||||||||
| January – December 2026 | 21,071 | $ | (0.32 | ) | $ | 6,807 | ||||||
| January – December 2027 | 18,944 | $ | (0.30 | ) | $ | 741 | ||||||
| Weighted | ||||||||||||
| Average Strike | ||||||||||||
| Total Volumes | Price | |||||||||||
| Description and Production Period | (Barrels) | (Per Barrel) | Fair Value | |||||||||
| Natural Gas Liquids Swaps: | ||||||||||||
| January – December 2026 | 1,894 | $ | 22.10 | $ | (3,550 | ) | ||||||
| January – December 2027 | 1,671 | $ | 22.69 | $ | (2,105 | ) | ||||||
| January – December 2028 | 1,295 | $ | 25.66 | $ | 1,367 | |||||||
Set forth below are the summarized amounts, terms and gross fair values of outstanding commodity derivative instruments as of December 31, 2024 (in thousands):
| Weighted | ||||||||||||
| Average Strike | ||||||||||||
| Total Volumes | Price | |||||||||||
| Description and Production Period | (Barrels) | (Per Barrel) | Fair Value | |||||||||
| Oil Swaps: | ||||||||||||
| January – December 2025 | 1,093 | $ | 57.29 | $ | (13,204 | ) | ||||||
| January – December 2026 | 990 | $ | 57.45 | $ | (8,423 | ) | ||||||
| January – December 2027 | 902 | $ | 58.22 | $ | (5,328 | ) | ||||||
| January – December 2028 | 422 | $ | 56.67 | $ | (2,680 | ) | ||||||
F-54
| Weighted | ||||||||||||
| Average Strike | ||||||||||||
| Total Volumes | Price | |||||||||||
| Description and Production Period | (Mmbtu) | (Per Mmbtu) | Fair Value | |||||||||
| Natural Gas Swaps: | ||||||||||||
| January – December 2025 | 22,880 | $ | 2.76 | $ | (17,063 | ) | ||||||
| January – December 2026 | 21,072 | $ | 3.19 | $ | (14,451 | ) | ||||||
| January – December 2027 | 19,133 | $ | 3.68 | $ | (2,889 | ) | ||||||
| January – December 2028 | 17,664 | $ | 3.57 | $ | (2,410 | ) | ||||||
| January – December 2029 | 16,454 | $ | 3.55 | $ | (549 | ) | ||||||
| Thereafter | 22,654 | $ | 3.59 | $ | 2,645 | |||||||
| Total | Basis | |||||||||||
| Volumes | Differential | |||||||||||
| Description and Production Period | (Mmbtu) | (Per Mmbtu) | Fair Value | |||||||||
| Natural Gas Basis Swaps: | ||||||||||||
| January – December 2025 | 22,880 | $ | (0.27 | ) | $ | 1,603 | ||||||
| January – December 2026 | 21,072 | $ | (0.32 | ) | $ | (956 | ) | |||||
| January – December 2027 | 3,355 | $ | 0.60 | $ | 11 | |||||||
| Weighted | ||||||||||||
| Total | Average Strike | |||||||||||
| Volumes | Price | |||||||||||
| Description and Production Period | (Barrels) | (Per Barrel) | Fair Value | |||||||||
| Natural Gas Liquids Swaps: | ||||||||||||
| January – December 2025 | 2,061 | $ | 22.82 | $ | (11,767 | ) | ||||||
| January – December 2026 | 1,894 | $ | 22.10 | $ | (9,740 | ) | ||||||
| January – December 2027 | 892 | $ | 20.67 | $ | (4,997 | ) | ||||||
Below is a reconciliation of the gross open positions by commodity to the net open positions presented on the consolidated balance sheet as of December 31, 2025:
| (in thousands) | Current | Noncurrent | ||||||||||||||
| Commodity | Assets | Liabilities | Assets | Liabilities | ||||||||||||
| Oil | $ | 2,056 | $ | (1,661 | ) | $ | 793 | $ | (757 | ) | ||||||
| Natural Gas | 7,428 | (11,738 | ) | 3,691 | (9,723 | ) | ||||||||||
| NGL | 177 | (3,727 | ) | 2,326 | (3,064 | ) | ||||||||||
| Total | $ | 9,661 | $ | (17,126 | ) | $ | 6,810 | $ | (13,544 | ) | ||||||
| Effects of netting arrangements | (9,661 | ) | 9,661 | (6,810 | ) | 6,810 | ||||||||||
| Total | $ | - | $ | (7,465 | ) | $ | - | $ | (6,734 | ) | ||||||
F-55
Below is a reconciliation of the gross open positions by commodity to the net open positions presented on the consolidated balance sheet as of December 31, 2024:
| (in thousands) | Current | Noncurrent | ||||||||||||||
| Commodity | Assets | Liabilities | Assets | Liabilities | ||||||||||||
| Oil | $ | - | $ | (13,204 | ) | $ | - | $ | (16,430 | ) | ||||||
| Natural Gas | 3,618 | (21,769 | ) | 4,025 | (19,934 | ) | ||||||||||
| NGL | 107 | (11,875 | ) | - | (14,738 | ) | ||||||||||
| Total | $ | 3,725 | $ | (46,848 | ) | $ | 4,025 | $ | (51,102 | ) | ||||||
| Effects of netting arrangements | (3,725 | ) | 3,725 | (4,025 | ) | 4,025 | ||||||||||
| Total | $ | - | $ | (43,123 | ) | $ | - | $ | (47,077 | ) | ||||||
The Company has entered into derivative contracts with counterparties who the Company believes are creditworthy counterparties. All of the Company’s counterparties are investment grade and no collateral has been required. As of December 31, 2025, the maximum amount of loss due to credit risk that the Company would incur if the counterparties failed to perform according to the terms of the derivative instrument contracts would be zero.
The total net gain on derivatives for the year ended December 31, 2025, comprised of a realized loss of $28.8 million and an unrealized gain of $76.0 million, for a total gain on commodity derivatives of $47.2 million. The total net loss on derivatives for the year ended December 31, 2024, comprised of a realized loss of $15.0 million and an unrealized gain of $2.5 million, for a total loss on commodity derivatives of $12.5 million.
NOTE E - OIL AND NATURAL GAS PROPERTIES AND PROPERTY AND EQUIPMENT
The Company has recorded oil and natural gas properties of $529.1 million and $534.9 million at December 31, 2025 and 2024, partially offset by accumulated depletion of $204.6 million and $176.2 million, respectively. Oil and natural gas properties recorded on the consolidated balance sheets consist entirely of proved properties for both periods presented. For the years ended December 31, 2025 and 2024, depletion expense related to the Company’s oil and natural gas properties was $28.4 million and $34.2 million, respectively.
Below is a summary of other property and equipment as of December 31:
| (in thousands) | Useful Life in Years | 2025 | 2024 | |||||||||
| Furniture and fixtures | 7 | $ | 92 | $ | 92 | |||||||
| Software and licenses | 3 | 8,612 | 7,022 | |||||||||
| Computers and other hardware | 3 | 11 | 12 | |||||||||
| Vehicles | 5 | 1,905 | 2,190 | |||||||||
| Machinery and equipment | 5 | 225 | 225 | |||||||||
| Leasehold improvements | 6 | 443 | 443 | |||||||||
| Compressors | 5 | 4,259 | 3,824 | |||||||||
| Total other property and equipment | $ | 15,547 | $ | 13,808 | ||||||||
| Accumulated depreciation and amortization | (10,090 | ) | (7,784 | ) | ||||||||
| Total other property and equipment, net | $ | 5,457 | $ | 6,024 | ||||||||
F-56
For the years ended December 31, 2025 and 2024, depreciation expense related to property and equipment was $3.3 million and $3.0 million, respectively.
2025 Divestitures
During the year ended December 31, 2025, the Company sold leasehold and mineral interests in various oil and natural gas properties located primarily in Oklahoma in exchange for $8.2 million in proceeds, resulting in a gain for an equal amount as no book value remained for the properties. Additionally, the Company sold various other property and equipment that resulted in a $0.3 million gain.
In addition, the Company entered into various agreements to divest approximately 300 properties. No cash consideration was exchanged as the associated plugging and abandonment (“P&A”) obligations offset the positive economic value of the divestment packages, resulting in no net proceeds to the Company. As a result of the divestitures, approximately $10.6 million of asset retirement obligation (“ARO”) liabilities were removed from the Company’s balance sheet along with the carrying value of the disposed properties. No material gain or loss was recognized upon derecognition.
2024 Divestitures
On September 5, 2024, pursuant to the terms and conditions of the Purchase and Sale Agreement, Presidio WAB LLC closed on the sale of its Cherokee leasehold at its full net revenue interest (NRI) along with approximately 5,800 net acres of Virgilian leasehold to Upland Exploration, LLC et al for total consideration of $83.7 million.
Presidio assigned no value to the leasehold at the time of its acquisition, which resulted in a gain on sale of $83.7 million.
NOTE F - OTHER CURRENT LIABILITIES
As of December 31, 2025 and 2024, other current liabilities were comprised of the following:
| (in thousands) | 2025 | 2024 | ||||||
| Accrued lease operating expenses | $ | 8,017 | $ | 8,358 | ||||
| Ad Valorem payable | 4,106 | 4,232 | ||||||
| Accrued interest | 3,750 | 4,193 | ||||||
| General and administrative | 7,022 | 1,418 | ||||||
| Other | 137 | 13 | ||||||
| Total other current liabilities | $ | 23,032 | $ | 18,214 | ||||
F-57
NOTE G - LONG-TERM DEBT
A summary of outstanding debt obligations as of December 31, 2025 and 2024 is as follows:
| (in thousands) | Interest | |||||||||
| Description | Term Range | Rate Range | 2025 | |||||||
| ABS II Securitization | Jul 2023-Mar 2038 | 7.8% - 8.4 | % | $ | 266,892 | |||||
| Trail Dust Financing | Jan 2024-Jan 2029 | 7.3 | % | 2,266 | ||||||
| WAB RBL | Jul 2025-Dec 2026 | 7.3 | % | 3,500 | ||||||
| Equipment financing obligations | 1,831 | |||||||||
| ABS II Debt issuance costs, net | (3,918 | ) | ||||||||
| WAB RBL Debt issuance costs, net | (49 | ) | ||||||||
| Trail Dust Debt issuance costs, net | (16 | ) | ||||||||
| Total debt | $ | 270,506 | ||||||||
| Current portion | (45,363 | ) | ||||||||
| Total long-term portion | $ | 225,143 | ||||||||
| (in thousands) | Interest | |||||||||
| Description | Term Range | Rate Range | 2024 | |||||||
| ABS II Securitization | July 2023-Mar 2038 | 7.8% - 8.4% | $ | 310,378 | ||||||
| Trail Dust Financing | Jan 2024-Jan 2029 | 6.9 | % | 2,451 | ||||||
| Equipment financing obligations | 2,482 | |||||||||
| ABS II Debt issuance costs, net | (5,605 | ) | ||||||||
| Trail Dust Debt issuance costs, net | (22 | ) | ||||||||
| Total debt | $ | 309,684 | ||||||||
| Current portion | (45,044 | ) | ||||||||
| Total long-term portion | $ | 264,640 | ||||||||
ABS II Securitization
On July 18, 2023, Presidio Investment Holdings LLC undertook a strategic initiative to optimize its capital structure and enhance financial flexibility. As part of this effort, the Company, through Presidio Finance LLC, issued ABS II debt and used the proceeds to repay the $340.6 million outstanding ABS I notes. This refinancing resulted in the elimination of the B notes and the continuation of the A-1 and A-2 tranches with a different investor group.
The Company issued $380.0 million in term asset-backed securities, hereafter referred to as the “ABS II Notes.” The ABS II Notes include two investment-grade rated tranches. The issuance included $190.0 million aggregate principal amount of its 7.806% Class A-1 Notes due December 25, 2038, and $190.0 million aggregate principal amount of its 8.418% Class A-2 Notes due December 25, 2038.
The ABS II Notes are subject to a series of covenants and restrictions customary for transactions of this type, including (i) that the Issuer maintains specified reserve accounts to be used to make required interest payments, (ii) premium payments in the case of an optional prepayment before certain dates, (iii) certain indemnification payments in the event, among other things, that all the assets that were securitized as part of the ABS I transaction pledged as collateral for the ABS II Notes are used in stated ways defective or ineffective, and (iv) covenants related to recordkeeping, access to information and similar matters.
The ABS II Notes are also subject to customary early amortization events provided for in the indenture, including events tied to failure to maintain stated debt service coverage ratios, failure to maintain certain production metrics, certain management termination events, and event of default and the failure to repay or refinance the ABS II Notes on the applicable scheduled maturity date.
F-58
The ABS II Notes are subject to certain customary events of default, including events relating to non-payment of required interest, principal or other amounts due on or with respect to the ABS II Notes, failure to comply with covenants within certain time frames, certain bankruptcy events, breaches of specified representations and warranties, failure of security interests to be effective and certain judgments against the issuer.
As of December 31, 2025 and 2024, the Company was in compliance with all financial covenants.
The Company incurred debt issuance costs of $8.9 million related to the issuance of the ABS II Notes. These costs are recorded as a reduction to “Long-term debt” on the Company’s consolidated balance sheet. Amortization of debt issuance costs related to the ABS II Notes, included in interest expense in the consolidated statements of operations, for the years ended December 31, 2025 and 2024 was $1.7 million and $2.0 million, respectively.
Trail Dust Financing
On January 31, 2024, Trail Dust LLC (“Trail Dust”), a subsidiary of Presidio Investment Holdings LLC, entered into a loan agreement with Independent Bank. Independent Bank doing business as Independent Financial has since merged with SouthState Bank. Under this agreement, the lender agreed to provide an advancing term loan facility with a maximum principal amount of $8.7 million (the “Trail Dust Loan”). The purpose of the loan is to finance the acquisition of new and used compressors.
Advances under the Trail Dust Loan are subject to borrowing base limitations, which restrict the maximum loan amounts based on the type of equipment financed. Advances for used compressors are limited to 75% of the lesser of cost or fair market value, while advances for new compressors are limited to 80% of the cost. The aggregate principal amount of advances under the loan cannot exceed $8.7 million.
The Trail Dust Loan bears interest at a fluctuating rate equal to the Prime Rate subject to a minimum interest rate of 4.5% per annum. The advance period, during which Trail Dust may request draws under the loan agreement, remained open as of December 31, 2024. The advance period continues until the “Termination Date,” as defined in the loan agreement, which is expected to occur on or around January 31, 2025, at which point no additional draws may be made. Upon the Termination Date any outstanding principal converts to a term loan with equal monthly principal and interest payments through the maturity date of January 31, 2029. Upon the termination of the advance period, any outstanding balance converts to a term loan bearing interest at a fixed rate equal to the 5-Year Treasury Rate plus 3.0%, with a minimum interest rate of 4.5% per annum.
The obligations under the Trail Dust Loan are secured by a first-priority lien on substantially all of Trail Dust’s assets, including all compressors acquired with loan proceeds, as well as Trail Dust’s rights under its Master Rental Agreement. Additionally, Presidio Investment Holdings LLC serves as a guarantor of the debt.
The loan agreement includes customary covenants and reporting requirements, including the obligation for Trail Dust and its guarantor, Presidio Investment Holdings LLC, to furnish quarterly financial statements to the lender.
During the year ended December 31, 2025, the Company incurred debt issuance costs of $16 thousand related to the Trail Dust Loan. The Company incurred debt issuance costs of $0.2 million related to the Trail Dust Loan during the year ended December 31, 2024. These costs are recorded as a reduction to “Long-term debt” on the Company’s consolidated balance sheet. Amortization of debt issuance costs related to the Trail Dust Loan included in interest expense in the consolidated statements of operations was $4.0 thousand for each of the years ended December 31, 2025 and 2024.
Total interest expense related to the Trail Dust Loan for the years ended December 31, 2025 and 2024 was $0.2 million and $0.1 million, respectively.
As of December 31, 2025 and 2024, the outstanding balance of the Trail Dust Loan was $2.3 million and $2.5 million, respectively. Trail Dust was in compliance with all financial covenants as of both dates.
F-59
Revolving Credit Facility
On July 2, 2025, the Company, through Presidio WAB LLC as borrower and Presidio Investment Holdings LLC as guarantor, entered into a reserve-based revolving credit facility with SouthState Bank (“WAB RBL”). The facility provides for borrowings up to $20.0 million, subject to a borrowing base initially set at $7.5 million, with a maturity date of July 2, 2028. Borrowings under the facility bear interest at a rate equal to the Prime Rate and are secured by substantially all of the Company’s oil and natural gas properties and related assets not already encumbered by the ABS. Proceeds from the facility may be used for acquisitions and development of oil and natural gas properties, letters of credit, working capital, and other general corporate purposes.
The Company incurred debt issuance costs of $49 thousand related to the WAB RBL. These costs are recorded as a reduction to “current portion of long-term debt” on the Company’s condensed consolidated balance sheet.
Total interest expense related to the WAB RBL for the year ended December 31, 2025 was $0.2 million.
The outstanding balance of the WAB RBL as of December 31, 2025 was $3.5 million. The Company was in compliance with all financial and non-financial covenants as of that date.
The future amounts of required principal payments of long-term debt after December 31, 2025 are as follows:
| (in thousands) | ||||||||||||
| Years Ending December 31, | ABS II | Trail Dust | WAB RBL | |||||||||
| 2026 | $ | 40,190 | $ | 685 | $ | 3,500 | ||||||
| 2027 | 49,878 | 729 | - | |||||||||
| 2028 | 52,890 | 784 | - | |||||||||
| 2029 | 53,254 | 68 | - | |||||||||
| 2030 | 51,409 | |||||||||||
| Thereafter | 19,271 | - | - | |||||||||
| Total | $ | 266,892 | $ | 2,266 | $ | 3,500 | ||||||
NOTE H - MEMBERS’ EQUITY
On March 29, 2018 the Company entered into an amended and restated LLC agreement, with certain members of Company management (“Management Group”) and NH Presidio Investments LLC (“PE Sponsor”) whereby the PE Sponsor and the Management Group made initial capital contributions to the Company in the form of Class A units and entered into commitments to make additional Class A equity capital contributions to the Company, subject to approval of the Board of the Company.
The LLC agreement also authorizes the Company to issue Class B units, which are intended to constitute profit interests within the meaning of IRS guidelines. The Class B units vest 20% annually over four years, with the final 20% vesting upon the occurrence of a change of control event. Holders of the Class B units are entitled to cash payouts upon the return of contributed capital plus a rate of return to specified holders of Class A units and the Class B units are forfeited upon termination of employment with the Company at the discretion of Management. The achievement of these payouts is a performance condition that requires the Company to assess, at each reporting period, the probability that an event of payout will occur. Compensation cost is required to be recognized at such time that the payout terms are probable of being met. The incentive units are accounted for as liability-classified awards pursuant to ASC Topic 718, “Compensation-Stock Compensation,” as the achievement of the payout conditions requires the settlement of such awards by transferring cash to the incentive unit holders. On January 6, 2025, the Board of Representatives of Presidio Investment Holdings LLC approved a cash distribution totaling $75.0 million to its members, including $15.0 million to the Class B unit holders which was recorded as compensation expense for the year ended December 31, 2025. The distribution was paid on January 8, 2025, and was allocated among equity holders in accordance with the Company’s LLC Agreement. Because the distribution was neither declared nor approved as of December 31, 2024, it was not reflected in the consolidated financial statements for the year ended December 31, 2024. As of December 31, 2025, there were 994 Class B units that remained outstanding and there were no declared distributions which would trigger payout to the Class B unitholders and no such distributions were pending or contemplated for the near future. Therefore, no additional amounts have been accrued as of December 31, 2025 related to the Class B units.
F-60
NOTE I - LEASES
A summary of leasing activities for the years ending December 31, 2025 and 2024 is as follows:
| (in thousands) | ||||||||||
| Cost | Classification | 2025 | 2024 | |||||||
| Operating lease cost | General and administrative | $ | 239 | $ | 239 | |||||
| Finance lease cost | Amortization and interest expense | 1,081 | 1,120 | |||||||
| Total cost | $ | 1,320 | $ | 1,359 | ||||||
| (in thousands) | ||||||||||
| Account | Balance Sheet Classification | 2025 | 2024 | |||||||
| Right of use asset - financing | Other property and equipment | $ | 1,724 | $ | 2,010 | |||||
| Right of use asset - operating | Right of use - operating lease | 135 | 339 | |||||||
| Financing lease ST | Current portion of long-term debt | 996 | 1,104 | |||||||
| Operating lease ST | Current operating lease liabilities | 144 | 217 | |||||||
| Financing lease LT | Long-term debt, net | 835 | 1,347 | |||||||
| Operating lease LT | Non-current operating lease liabilities | - | 135 | |||||||
The cash paid amounts related to operating leases were $0.2 million for the each of the years ended December 31, 2025 and 2024, and the financing lease cash paid amounts were $1.3 million for each year.
There were no right-of-use asset amounts obtained in exchange for lease obligations relating to operating leases during the years ended December 31, 2025 and 2024. The right-of-use asset amounts obtained in exchange for lease obligations relating to financing leases during the years ended December 31, 2025 and 2024 were $0.7 million and $0.4 million, respectively.
F-61
As of December 31, 2025 and 2024, the remaining lease terms for operating leases were 1.0 years and 2.0 years, respectively, with a weighted average discount rate of 6.93%. As of December 31, 2025 and 2024, the weighted average remaining lease terms for financing leases were 2.4 years and 1.9 years, respectively, with a weighted average discount rate of 6.93%. The following table represents future minimum lease commitments under operating leases and financing leases:
| (in thousands) | Operating Leases | Financing Leases | ||||||
| 2026 | $ | 166 | $ | 1,085 | ||||
| 2027 | - | 500 | ||||||
| 2028 | - | 288 | ||||||
| 2029 | - | 113 | ||||||
| Total lease payments | $ | 166 | $ | 1,986 | ||||
| Less: interest | (22 | ) | (155 | ) | ||||
| Present value of lease liabilities | $ | 144 | $ | 1,831 | ||||
NOTE J - COMMITMENTS AND CONTINGENCIES
Litigation
In the opinion of management, any claims and legal actions that may arise, or may have arisen in the ordinary course of business will not have a material adverse effect on the Company’s consolidated financial position, results of operations, or liquidity for the years ended December 31, 2025 and 2024.
Environmental Remediation
Various federal, state, and local laws and regulations covering the discharge of materials into the environment, or otherwise relating to the protection of the environment, may affect the Company’s operations and the costs of its crude oil and natural gas exploration, development, and production operations. The Company does not anticipate that it will be required in the near future to expend significant amounts in relation to the consolidated financial statements taken as a whole by reason of environmental laws and regulations, and appropriately no reserves have been recorded.
Casualties and Other Risks
The Company maintains coverage in various insurance programs underwritten by highly rated carriers. The Company’s policies provide for property damage and other customary coverages for the nature and scope of its operations. The Company believes it has adequate coverage, although insurance will not cover every type of loss that might occur. As a result of insurance market conditions, coverage could become significantly more costly or even unavailable.
If the Company were to incur a significant loss for which it was inadequately covered, the loss could have a material impact the results of its operations, cash flow or financial condition. Additionally, if proceeds from available insurance were not to be paid in a timely manner, the Company’s financial condition could be affected. Any event that interrupts the Company’s revenues or which causes the Company to make a significant expenditure not covered by insurance could reduce the Company’s ability to meet future financial obligations.
F-62
NOTE K - RETIREMENT PLAN
The Company provides a 401(k) retirement plan covering all eligible employees. The plan provides for discretionary employer contributions as determined by the Company or its management in addition to a Company match of up to 6% of an employee’s salary. The Company contributed $0.7 million for the match to the 401(k) retirement plan for each of the years ended December 31, 2025 and 2024.
Note L – Segment Information
The Company is managed on a consolidated basis as one operating segment and one reportable segment, which is engaged in the acquisition, development, exploration, and production of oil and natural gas properties (“Operating segment”). The Company’s operations are conducted primarily in one geographic area of the United States. The Operating segment derives its revenue from customers through the sale of oil, natural gas, and NGLs as well as other immaterial service contracts. See Note B – Summary of Significant Accounting Policies for further discussion of the Company’s sources of revenue.
The Company’s chief operating decision maker (“CODM”) is the collective Co-Chief Executive Officers. The CODM uses the Company’s consolidated financial results to make key operating decisions, assess performance, and to allocate resources. The measures of segment profit or loss and total assets utilized by the CODM are net income and total assets as reported on the consolidated statements of operations and the consolidated balance sheets, respectively. The significant expense categories, their amounts and other segment items that are regularly provided to the CODM are the same amounts that comprise the Company’s consolidated statements of operations in total.
The CODM is presented with gross revenues and revenue deductions broken out separately for review. As such, the CODM reviews gross oil sales, gross natural gas sales, and gross natural gas liquid sales separately from oil deductions, natural gas deductions, and natural gas liquid deductions as described in Note B – Summary of Significant Accounting Policies. The CODM is also presented with commodity derivative gains (losses) broken out into realized gain/(loss) from derivatives and unrealized gain(loss) from derivatives as described in Note D – Derivative Activities.
The CODM uses consolidated net income as a measure of profitability to evaluate segment performance to allocate the appropriate resources to drive efficiencies and develop growth strategies.
Interest income for the years ended December 31, 2025 and 2024 was $0.9 million and $2.1 million, respectively.
NOTE M - SUBSEQUENT EVENTS
In preparing the accompanying consolidated financial statements, management has evaluated all subsequent events and transactions for potential recognition or disclosure through March 9, 2026.
On March 4, 2026 (the “Closing Date”), Presidio Production Company (f/k/a Presidio PubCo Inc.), a Delaware corporation (the “Company”) consummated the previously announced business combination (the “Closing”) pursuant to the Business Combination Agreement, dated August 5, 2025 (the “Business Combination Agreement”), by and among EQV Ventures Acquisition Corp., a Cayman Islands exempted company (“EQV”), the Company, Prometheus PubCo Merger Sub Inc., a Delaware corporation a (“EQV Merger Sub”), Prometheus Holdings LLC, a Delaware limited liability company (“EQV Holdings”), Prometheus Merger Sub LLC, a Delaware limited liability company (“Presidio Merger Sub”) and Presidio Investment Holdings LLC, a Delaware limited liability company (“PIH”). The transactions contemplated by the Business Combination Agreement are collectively referred to herein as the “Business Combination.” The Business Combination Agreement and related transactions were approved at an extraordinary general meeting of EQV’s shareholders held on February 27, 2026 (the “Extraordinary General Meeting”).
F-63
Previously on August 5, 2025, the Company entered into a Business Combination Agreement (“BCA”) by and among the Company, and EQV Ventures Acquisition Corp., an exempted company incorporated in the Cayman Islands (“EQV”). The BCA provided for a series of mergers pursuant to which the Company survived as a wholly owned subsidiary of EQV Holdings LLC (“EQV Holdings”), a Delaware corporation and wholly owned subsidiary of EQV, and EQV survived as a wholly owned subsidiary of Presidio PubCo Inc., a Delaware corporation (“Presidio PubCo”), where Presidio PubCo and its subsidiaries, as the combined company, will be organized in an “Up C” structure. Upon Closing, Presidio PubCo was renamed Presidio Production Company and listed on the New York Stock Exchange under the ticker “FTW.”
In connection with the closing of the BCA, Presidio PubCo acquired all the issued and outstanding equity interests of EQV Resources LLC, a Delaware limited liability company (“EQVR”), pursuant to the terms and conditions set forth in the agreement and plan of merger, dated as of August 5, 2025. EQVR, an affiliate of EQV, is an oil and gas operating company that owns proved properties in the Texas Panhandle.
Concurrently with the execution of the BCA, on August 5, 2025, the Company, EQV and Presidio PubCo entered into Subscription Agreements with certain investors (“PIPE Investors”) pursuant to which, among other things, the PIPE Investors have agreed to subscribe for and purchase an aggregate of 8,750,000 shares of Presidio PubCo Class A Common Stock for a purchase price of $10.00 per share, on the terms and subject to the conditions set forth therein. Each Subscription Agreement contained customary representations and warranties of EQV and Presidio PubCo, on the one hand, and the PIPE Investor, on the other hand, and customary conditions to Closing, including the consummation of the Business Combination immediately following the consummation of the PIPE Financing.
Concurrently with the execution of the BCA, on August 5, 2025, the Company, EQV and Presidio PubCo entered into the Securities Purchase Agreement with certain investors (“Preferred Investors”), pursuant to which and subject to the satisfaction of the closing conditions contained therein, the Preferred Investors purchased in a private placement from Presidio PubCo an aggregate of 125,000 Preferred Shares and 937,500 Preferred Investor Warrants for a cash purchase price of $123,750,000 (net of all applicable original issue discounts). The Preferred Shares have the rights, preferences, and privileges set forth in Presidio’s Certificate of Designation and certain holders of the Preferred Shares have certain rights pursuant to the Preferred Stockholders’ Agreement.
In connection with the Business Combination, on February 23, 2026, the Company, EQV and Presidio PubCo entered into a Series B Preferred Securities Purchase Agreement (the “Series B Securities Purchase Agreement”) with Adage Capital Partners, L.P. (the “Series B Preferred Investor”), pursuant to which, immediately prior to or substantially concurrently with the Closing, the Series B Preferred Investor purchased in a private placement from Presidio an aggregate of 27,173 Series B Perpetual Participating Convertible Preferred Stock of Presidio PubCo Inc., par value $0.0001 per share (the “Series B Preferred Shares”), with each Series B Preferred Share convertible into 100 shares of Presidio Class A Common Stock and entitled to participate in dividends declared on shares of Presidio Class A Common Stock on an as-converted basis, for an aggregate cash purchase price of $25,000,000 (the “Series B Preferred Financing”). The Series B Preferred Shares have the rights, preferences, and privileges set forth in Presidio’s Certificate of Designation of Preferences, Rights and Limitations of Series B Perpetual Participating Convertible Preferred Stock (the “Series B Certificate of Designation”).
A full description of the Business Combination and the terms of the Business Combination Agreement are included in the final prospectus and definitive proxy statement filed with the U.S Securities and Exchange Commission (the “SEC”), dated January 30, 2026 (the “Proxy Statement/Prospectus”) in the section entitled “The Business Combination Proposal” beginning on page 92.
Subsequent to the closing of the EQVR Acquisition on March 4, 2026, the Company paid $60 million to modify the strike prices on EQVR’s natural gas commodity hedges.
On February 24, 2026, the Company entered into a letter of intent to acquire certain producing assets in the Arkoma Basin, including assets operated by Canyon Creek Energy-Arkoma LLC, from companies controlled by Vortus Investments (“the Seller”) for approximately $80 million (the “Acquisition”). The Acquisition assets consist of 56 producing wells with net PDP production of approximately 22.6 Mmcfe/d (70% gas and 30% NGLs), net PDP reserves of approximately 100 Bcfe, and a PDP PV-10 of approximately $100 million.
The Acquisition is subject to confirmatory due diligence, negotiation of definitive agreements, board approval, financing arrangements, and customary closing conditions. The Company anticipates that definitive documentation could be signed and the transaction closed within the second quarter of 2026.
Subsequent to the reporting date and through the date of this report, the Company borrowed an additional $4.0 million under its WAB RBL credit facility to support funding for its operations.
There were no other material subsequent events that required recognition or disclosure in these consolidated financial statements.
F-64
Note N – Supplemental information of oil and natural gas producing activities (unaudited)
The following reserve estimates present the Company’s estimate of the proved natural gas and oil reserves and net cash flow of the Company’s properties, in accordance with the guidelines established by the Securities and Exchange Commission. The Company emphasizes that reserve estimates are inherently imprecise and that estimates of new discoveries are more imprecise than those of producing natural gas and oil properties. Accordingly, the estimates are expected to change as future information becomes available. All the oil and natural gas reserves are located in Kansas, Oklahoma, and Texas.
Capitalized oil and natural gas costs
Aggregate capitalized costs related to oil and natural gas production activities with applicable accumulated depreciation, depletion, and amortization are as follows:
| As of December 31, | ||||||||
| (in thousands) | 2025 | 2024 | ||||||
| Proved properties | $ | 529,096 | $ | 534,872 | ||||
| Unproved properties | — | — | ||||||
| Total oil and gas properties | 529,096 | 534,872 | ||||||
| Accumulated depreciation and depletion | (204,639 | ) | (176,221 | ) | ||||
| Net capitalized costs | $ | 324,457 | $ | 358,651 | ||||
Costs incurred in oil and natural gas activities
Costs incurred in oil and natural gas property acquisition, exploration and development activities are as follows:
| For the year ended December 31, | ||||||||
| (in thousands) | 2025 | 2024 | ||||||
| Development costs | $ | 3,437 | $ | 709 | ||||
| Proved property acquisition costs | 771 | 2,784 | ||||||
| Unproved property acquisition costs | — | — | ||||||
| Total costs incurred | $ | 4,208 | $ | 3,493 | ||||
F-65
Reserve quantity information
Proved oil and natural gas reserves are those quantities of oil and natural gas, which by analysis of geoscience and engineering data, can be estimated with reasonable certainty to be economically producible from a given date forward, from known reservoirs, and under existing economic conditions, operating methods, and government regulations. Proved developed reserves are proved reserves that can be expected to be recovered through existing wells with existing equipment and operating methods or in which the cost of the required equipment is relatively minor compared to the cost of a new well. Proved undeveloped reserves are proved reserves that are expected to be recovered from new wells on undrilled acreage, or from existing wells where a relatively major expenditure is required for recompletion. Below are the net quantities of net proved developed reserves of the Company’s properties:
| (in thousands) Proved Developed and Undeveloped Reserves | Oil and Condensate (MBbl) | Natural Gas (MMcf) | NGLs (MBbl) | Total Equivalents (MBOE) | ||||||||||||
| December 31, 2023 | 15,909 | 354,039 | 31,556 | 106,471 | ||||||||||||
| Revisions of previous estimates | (496 | ) | (25,642 | ) | (2,180 | ) | (6,948 | ) | ||||||||
| Extensions, discoveries and other additions | 84 | 464 | 8 | 169 | ||||||||||||
| Production | (1,424 | ) | (28,013 | ) | (2,460 | ) | (8,553 | ) | ||||||||
| Purchase of reserves | 121 | 853 | 187 | 450 | ||||||||||||
| Sale of reserves in place | — | — | — | — | ||||||||||||
| December 31, 2024 | 14,194 | 301,701 | 27,111 | 91,589 | ||||||||||||
| Revisions of previous estimates | (249 | ) | 37,074 | 91 | 6,021 | |||||||||||
| Extensions, discoveries and other additions | 36 | 278 | 6 | 88 | ||||||||||||
| Production | (1,290 | ) | (25,778 | ) | (2,093 | ) | (7,679 | ) | ||||||||
| Purchase of reserves | - | - | - | - | ||||||||||||
| Sale of reserves in place | (10 | ) | (370 | ) | (44 | ) | (116 | ) | ||||||||
| December 31, 2025 | 12,681 | 312,905 | 25,071 | 89,903 | ||||||||||||
| Proved Developed Reserves: | ||||||||||||||||
| December 31, 2024 | 14,144 | 301,318 | 27,111 | 91,475 | ||||||||||||
| December 31, 2025 | 12,681 | 312,905 | 25,071 | 89,903 | ||||||||||||
| Proved Undeveloped Reserves: | ||||||||||||||||
| December 31, 2024 | 50 | 383 | - | 114 | ||||||||||||
| December 31, 2025 | — | — | — | — | ||||||||||||
Notable changes in proved reserves for the year ended December 31, 2025 included the following:
| ● | Extensions and Discoveries: In 2025, total extensions and discoveries increased proved reserves by 88 MBoe. The primary driver was successful partner-operated activity within the basin. |
| ● | Revisions of Previous Estimates: In 2025, revisions of previous estimates resulted in a net increase of 6.0 MMBoe. Approximately 7.1 MMBoe of this change was attributable to higher prices utilized for the year ended December 31, 2025. While year-end SEC pricing increased compared to December 31, 2024, revisions to other economic assumptions, including forward pricing considerations, contributed to changes in the timing of certain workover activities. These factors, together with updates to cost estimates, deduct modeling, and midstream election assumptions, resulted in an offsetting decrease of approximately 1.1 MMBoe. |
Notable changes in proved reserves for the year ended December 31, 2024 included the following:
| ● | Extensions and Discoveries: In 2024, total extensions and discoveries increased proved reserves by 169 MBoe. The primary driver was the addition of proved undeveloped (PUD) locations acquired through a farmout agreement, contributing approximately 114 MBoe. The remaining additions resulted from changes in well utilization and successful partner-operated activity within the basin. |
| ● | Revisions of Previous Estimates: In 2024, revisions of previous estimates resulted in a net decrease of 6.9 MMBoe. Of this reduction, 5.8 MMBoe was attributable to lower SEC pricing, while 1.1 MMBoe reflected unfavorable economic conditions, including the refinement of workover program timing, midstream facility interruptions, and the restructuring of proved developed non-producing (PDNP) wells. |
| ● | Acquisition of reserves. In 2024, purchases of reserves totaled 450 MBoe due to acquisition of incremental interests in proved developed oil and natural gas properties primarily operated by the Company. |
F-66
Standardized measure of discounted future net cash flows relating to oil and natural gas reserves
The standardized measure of discounted future net cash flows relating to oil and natural gas reserves and associated changes in standard measure amounts were prepared in accordance with the provision of FASB ASC 932-235-55, Extractive Activities – Oil and Gas (“Topic 932”). Future cash inflows were computed by applying average prices of oil and natural gas for the last 12 months to estimated future production. Future production and development costs were computed by estimating the expenditures to be incurred in developing, producing, and plugging and abandoning the proved reserves at year-end, based on year-end costs and assuming continuation of existing economic conditions. Future net cash flows are discounted at the rate of 10% annually to derive the standardized measure of discounted cash flows. Actual future cash inflows may vary considerably, and the standardized measure does not necessarily represent the fair value of the acquired properties’ oil and natural gas reserves. Standard measure amounts are:
| Year Ended December 31, | ||||||||
| (in thousands) | 2025 | 2024 | ||||||
| Future cash inflows | $ | 2,385,532 | $ | 2,257,985 | ||||
| Future production costs | (1,390,660 | ) | (1,329,708 | ) | ||||
| Future development costs | (135,812 | ) | (148,324 | ) | ||||
| Future net cash flows before income tax | $ | 859,060 | $ | 779,953 | ||||
| Future income tax expense | (3,871 | ) | (1,807 | ) | ||||
| Future net cash flows | $ | 855,189 | $ | 778,146 | ||||
| 10% annual discount for estimated timing of cash flows | (341,090 | ) | (286,251 | ) | ||||
| Standardized measure of discounted future net cash flows | $ | 514,099 | $ | 491,895 | ||||
The 12-month average prices were adjusted to reflect applicable transportation and quality differentials on a well-by-well basis to arrive at realized sales prices used to estimate the properties’ reserves. The prices for the properties’ reserves were as follows:
| Year Ended December 31, | ||||||||||||
| 2025 | 2024 | 2023 | ||||||||||
| Oil (per Bbl) | $ | 63.84 | $ | 73.86 | $ | 76.16 | ||||||
| Natural gas (per Mcf) | $ | 3.20 | $ | 1.97 | $ | 2.55 | ||||||
| Natural gas liquids (per Bbl) | $ | 22.87 | $ | 22.64 | $ | 22.68 | ||||||
Changes in the Standardized Measure of Discounted Future Net Cash Flows at 10% per annum are as follows:
| Year Ended December 31, | ||||||||
| (in thousands) | 2025 | 2024 | ||||||
| Sales of oil and natural gas, net of production costs | $ | (89,621 | ) | $ | (103,457 | ) | ||
| Net changes in prices and production costs | 48,728 | (74,382 | ) | |||||
| Changes in future development costs | 235 | (371 | ) | |||||
| Extensions, discoveries and other additions | 1,525 | 3,139 | ||||||
| Development costs incurred during the period | 261 | — | ||||||
| Revisions of previous quantity estimates | 36,872 | (41,824 | ) | |||||
| Purchases of reserves-in-place | — | 3,968 | ||||||
| Sales of reserves-in-place | 27 | — | ||||||
| Accretion of discount | 49,190 | 63,940 | ||||||
| Net change in income taxes | (1,148 | ) | 349 | |||||
| Changes in timing and other | (23,865 | ) | 2,591 | |||||
| Net increase (decrease) | $ | 22,204 | $ | (146,047 | ) | |||
| Beginning of year | 491,895 | 637,942 | ||||||
| End of year | $ | 514,099 | $ | 491,895 | ||||
Estimates of economically recoverable natural gas and oil reserves and of future net revenues are based upon a number of variable factors and assumptions, all of which are to some degree subjective and may vary considerably from actual results. Therefore, actual production, revenues, development and operating expenditures may not occur as estimated. The reserve data are estimates only, are subject to many uncertainties, and are based on data gained from production histories and on assumptions as to geologic formations and other matters. Actual quantities of natural gas and oil may differ materially from the amounts estimated.
F-67
 | 2300 North Field Street, Suite 1000 | |
| Dallas, Texas 75201 | ||
| 972-490-1970 |
Independent Auditor’s Report
To the Member and Management of
EQV Resources LLC
Report on the Audit of the Financial Statements
Opinion
We have audited the financial statements of EQV Resources LLC (the Company), which comprise the balance sheets as of December 31, 2025 and 2024, and the related statements of operations, changes in member’s equity, and cash flows for the years then ended, and the related notes to the financial statements.
In our opinion, the accompanying financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2025 and 2024, and the results of its operations and its cash flows for the years then ended in accordance with accounting principles generally accepted in the United States of America.
Basis for Opinion
We conducted our audits in accordance with auditing standards generally accepted in the United States of America (GAAS). Our responsibilities under those standards are further described in the Auditor’s Responsibilities for the Audit of the Financial Statements section of our report. We are required to be independent of the Company and to meet our other ethical responsibilities, in accordance with the relevant ethical requirements relating to our audits. We believe that the audit evidence we have obtained is sufficient and appropriate to provide a basis for our audit opinion.
Emphasis-of-Matter
As discussed in Note 1 to the financial statements, on August 5, 2025, the Company entered into an agreement and plan of merger that is pending close. Our opinion is not modified with respect to this matter.
Responsibilities of Management for the Financial Statements
Management is responsible for the preparation and fair presentation of the financial statements in accordance with accounting principles generally accepted in the United States of America, and for the design, implementation, and maintenance of internal control relevant to the preparation and fair presentation of financial statements that are free from material misstatement, whether due to fraud or error.
In preparing the financial statements, management is required to evaluate whether there are conditions or events, considered in the aggregate, that raise substantial doubt about the Company’s ability to continue as a going concern for one year after the date that the financial statements are issued.
Weaver and Tidwell, L.L.P.
CPAs AND ADVISORS | WEAVER.COM
F-68
The Member and Management of
EQV Resources LLC
Auditor’s Responsibilities for the Audit of the Financial Statements
Our objectives are to obtain reasonable assurance about whether the financial statements as a whole are free from material misstatement, whether due to fraud or error, and to issue an auditor’s report that includes our opinion. Reasonable assurance is a high level of assurance but is not absolute assurance and therefore is not a guarantee that an audit conducted in accordance with GAAS will always detect a material misstatement when it exists. The risk of not detecting a material misstatement resulting from fraud is higher than for one resulting from error, as fraud may involve collusion, forgery, intentional omissions, misrepresentations, or the override of internal control. Misstatements are considered material if there is a substantial likelihood that, individually or in the aggregate, they would influence the judgment made by a reasonable user based on the financial statements.
In performing an audit in accordance with GAAS, we:
| ● | Exercise professional judgment and maintain professional skepticism throughout the audit. |
| ● | Identify and assess the risks of material misstatement of the financial statements, whether due to fraud or error, and design and perform audit procedures responsive to those risks. Such procedures include examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. |
| ● | Obtain an understanding of internal control relevant to the audit in order to design audit procedures that are appropriate in the circumstances, but not for the purpose of expressing an opinion on the effectiveness of the Company’s internal control. Accordingly, no such opinion is expressed. |
| ● | Evaluate the appropriateness of accounting policies used and the reasonableness of significant accounting estimates made by management, as well as evaluate the overall presentation of the financial statements. |
| ● | Conclude whether, in our judgment, there are conditions or events, considered in the aggregate, that raise substantial doubt about the Company’s ability to continue as a going concern for a reasonable period of time. |
We are required to communicate with those charged with governance regarding, among other matters, the planned scope and timing of the audit, significant audit findings, and certain internal control–related matters that we identified during the audit.
/s/ WEAVER AND TIDWELL, L.L.P.
WEAVER AND TIDWELL, L.L.P.
Dallas, Texas
March 3, 2026
F-69
EQV Resources LLC
Balance Sheets
| December 31, 2025 | December 31, 2024 | |||||||
| ASSETS | ||||||||
| CURRENT ASSETS | ||||||||
| Cash and cash equivalents | $ | 1,692,927 | $ | 1,499,244 | ||||
| Prepaid expenses and other current assets | 166,667 | 10,012 | ||||||
| Accounts receivable - oil and gas sales | 1,417,991 | 2,949,679 | ||||||
| Current derivative asset | 2,172,182 | 404,996 | ||||||
| TOTAL CURRENT ASSETS | 5,449,767 | 4,863,931 | ||||||
| OIL AND GAS PROPERTIES, successful efforts | ||||||||
| Proved properties | 57,512,710 | 56,459,549 | ||||||
| Less accumulated depletion | (10,921,512 | ) | (6,018,565 | ) | ||||
| TOTAL OIL AND GAS PROPERTIES, NET | 46,591,198 | 50,440,984 | ||||||
| OTHER ASSETS | ||||||||
| Long term derivative asset | 1,037,045 | 349,992 | ||||||
| Other property and equipment, net | 49,293 | 63,203 | ||||||
| TOTAL OTHER ASSETS | 1,086,338 | 413,195 | ||||||
| TOTAL ASSETS | $ | 53,127,303 | $ | 55,718,110 | ||||
| LIABILITIES AND MEMBER’S EQUITY | ||||||||
| CURRENT LIABILITIES | ||||||||
| Accounts payable and accrued liabilities | $ | 1,353,654 | $ | 1,343,789 | ||||
| Derivative liability | 1,412,544 | 1,982,488 | ||||||
| TOTAL CURRENT LIABILITIES | 2,766,198 | 3,326,277 | ||||||
| LONG-TERM LIABILITIES | ||||||||
| Asset retirement obligations | 9,270,138 | 7,469,856 | ||||||
| Gas imbalance payable | 446,899 | 446,899 | ||||||
| Derivative liability | 2,333,859 | 4,400,065 | ||||||
| Note payable, net | 28,253,612 | 31,674,450 | ||||||
| TOTAL LONG-TERM LIABILITIES | 40,304,508 | 43,991,270 | ||||||
| MEMBER’S EQUITY | 10,056,597 | 8,400,563 | ||||||
| TOTAL LIABILITIES AND MEMBER’S EQUITY | $ | 53,127,303 | $ | 55,718,110 | ||||
The Notes to Financial Statements are an integral part of these statements
F-70
EQV Resources LLC
Statements of Operations
Years ended December 31, 2025 and 2024
| 2025 | 2024 | |||||||
| REVENUES | ||||||||
| Oil sales | $ | 5,769,492 | $ | 7,994,552 | ||||
| Gas sales, net | 9,679,515 | 6,075,221 | ||||||
| NGL sales, net | 5,719,913 | 7,503,114 | ||||||
| TOTAL REVENUES | 21,168,920 | 21,572,887 | ||||||
| OPERATING EXPENSES | ||||||||
| Lease operating expense | 11,328,462 | 10,153,263 | ||||||
| Production taxes | 863,212 | 907,524 | ||||||
| Depletion and depreciation | 4,916,857 | 6,031,636 | ||||||
| Accretion expense | 747,122 | 1,420,900 | ||||||
| General and administrative expenses | 2,378,891 | 2,030,000 | ||||||
| TOTAL OPERATING EXPENSES | 20,234,544 | 20,543,323 | ||||||
| OPERATING INCOME | 934,376 | 1,029,564 | ||||||
| OTHER INCOME (EXPENSE) | ||||||||
| Realized derivative gains (losses) | (292,274 | ) | 2,517,463 | |||||
| Unrealized derivative gains (losses) | 5,090,390 | (2,560,364 | ) | |||||
| Interest expense | (4,048,458 | ) | (4,806,167 | ) | ||||
| Gain on sale of asset | 10,000 | – | ||||||
| Other income | – | 39,357 | ||||||
| TOTAL OTHER INCOME (EXPENSE) | 759,658 | (4,809,711 | ) | |||||
| NET INCOME (LOSS) | $ | 1,694,034 | $ | (3,780,147 | ) | |||
The Notes to Financial Statements are an integral part of these statements
F-71
EQV Resources LLC
Statements of Member’s Equity
Years ended December 31, 2025 and 2024
| Balance, December 31, 2023 | $ | 12,180,710 | ||
| Net loss | (3,780,147 | ) | ||
| Balance, December 31, 2024 | $ | 8,400,563 | ||
| Member distributions | (38,000 | ) | ||
| Net income | 1,694,034 | |||
| Balance, December 31, 2025 | $ | 10,056,597 |
The Notes to Financial Statements are an integral part of these statements
F-72
EQV Resources LLC
Statements of Cash Flows
Years ended December 31, 2025 and 2024
| 2025 | 2024 | |||||||
| CASH FLOWS FROM OPERATING ACTIVITIES: | ||||||||
| Net income (loss) | $ | 1,694,034 | $ | (3,780,147 | ) | |||
| Adjustments to reconcile net income (loss) to net cash provided by (used in) operating activities: | ||||||||
| Depletion and depreciation | 4,916,857 | 6,031,636 | ||||||
| Settlement of asset retirement obligations | - | (112,739 | ) | |||||
| Accretion of asset retirement obligations | 747,122 | 1,420,900 | ||||||
| Amortization of deferred issuance costs | 336,508 | 276,134 | ||||||
| Amortization of conveyance | 373,106 | 374,128 | ||||||
| Gain on sale of asset | (10,000 | ) | (37,101 | ) | ||||
| Unrealized gain (loss) on derivatives | (5,090,389 | ) | 2,560,364 | |||||
| Changes in operating assets and liabilities | ||||||||
| Accounts receivable - oil and gas | 1,531,688 | (1,870,984 | ) | |||||
| Prepaid expenses and other current assets | (156,655 | ) | 340,552 | |||||
| Accounts payable and accrued liabilities | 9,865 | 892,157 | ||||||
| Gas imbalance payable | - | (242,179 | ) | |||||
| NET CASH PROVIDED BY OPERATING ACTIVITIES | 4,352,136 | 5,852,721 | ||||||
| CASH FLOWS FROM INVESTING ACTIVITIES: | ||||||||
| Acquisition of oil and gas properties | - | (921,756 | ) | |||||
| Purchase of other property and equipment | - | (11,763 | ) | |||||
| Proceeds from sale of assets | 10,000 | 37,101 | ||||||
| NET CASH PROVIDED BY (USED IN) INVESTING ACTIVITIES | 10,000 | (896,418 | ) | |||||
| CASH FLOWS FROM FINANCING ACTIVITIES: | ||||||||
| Distributions to member | (38,000 | ) | - | |||||
| Payments on note payable | (4,055,453 | ) | (4,342,200 | ) | ||||
| Payments of deferred financing costs | (75,000 | ) | (75,000 | ) | ||||
| NET CASH USED IN FINANCING ACTIVITIES | (4,168,453 | ) | (4,417,200 | ) | ||||
| NET CHANGE IN CASH | 193,683 | 539,103 | ||||||
| CASH AND CASH EQUIVALENTS, BEGINNING OF YEAR | 1,499,244 | 960,141 | ||||||
| CASH AND CASH EQUIVALENTS, END OF YEAR | $ | 1,692,927 | $ | 1,499,244 | ||||
| SUPPLEMENTAL CASH FLOW DISCLOSURES | ||||||||
| Noncash change in oil & gas properties for asset retirement revisions | $ | 1,053,160 | $ | (8,047,423 | ) | |||
| Cash paid for interest | $ | 3,338,844 | $ | 4,384,845 | ||||
The Notes to Financial Statements are an integral part of these statements
F-73
EQV Resources LLC
Notes to Financial Statements
Note 1. Organization and Nature of Operations
EQV Resources LLC (the Company) is a Delaware Limited Liability Company formed on September 5, 2023 and is a wholly owned subsidiary of EQV Resources Intermediate, LLC (Member). The Company is an Oklahoma City, Oklahoma based oil and gas company focused on the acquisition, exploration and development of natural gas and crude oil properties as an operating interest owner. The properties are located in Texas.
Merger Agreements
On August 5, 2025, the Company entered into an Agreement and Plan of Merger with EQV Ventures Acquisition Corp. (“EQV”), Presidio PubCo Inc. (“Purchaser”), EQVR Merger Sub LLC (“Merger Sub”), and the Company’s sole unitholder. The agreement provides that Merger Sub will merge with and into the Company, with the Company continuing as the surviving entity and becoming a wholly owned subsidiary of Purchaser (the “Merger”). At the closing of the transaction, all outstanding equity interests of the Company will be cancelled and converted into the right to receive an aggregate of 3,422,260 shares of Purchaser Class A common stock. In connection with the closing, Purchaser will repay all amounts outstanding under the Company’s Cibolo Loan and will pay defined transaction expenses on behalf of the Company. The closing of the Merger is anticipated to occur in March 2026 and is subject to customary conditions, including the effectiveness of Purchaser’s registration statement, receipt of requisite EQV stockholder approval, and approval for listing of the Purchaser Class A shares to be issued.
Note 2. Summary of Significant Accounting Policies
Estimates and Uncertainties
The preparation of financial statements in conformity with GAAP requires management to make estimates and assumptions that affect the reported amounts of assets and liabilities and disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. Actual results could differ from those estimates. The Company’s financial statements are based on a number of significant estimates including oil and natural gas reserve quantities that are the basis for the calculations of depletion and impairment of oil and natural gas properties, accrued oil and natural gas revenues, and the estimate of asset retirement obligations.
The prices received for crude oil, natural gas, and natural gas liquids (“NGL”) production can heavily influence our assumptions, judgements and estimates, and continued volatility of crude oil and natural gas prices could have a significant impact on our estimates. It is possible these estimates could be revised in the near-term and these revisions could be material.
Accounts Receivable - Oil and Gas Sales
Accounts receivable - oil and gas sales include amounts due from oil and gas purchasers. Accounts receivable include accrued revenues due under normal trade terms, generally requiring payment within 30 days of production. No interest was charged on past due balances for the years ended December 31, 2025 and 2024, respectively. The Company’s accounts receivable balances are regularly reviewed for possible non-payment indicators and reserves are recorded for expected credit losses based on management’s estimate of collectability at the time of review. Actual balances are charged against the reserve when all collection efforts have been exhausted.
F-74
EQV Resources LLC
Notes to Financial Statements
Oil and Gas Properties
The Company utilizes the successful efforts method of accounting for its oil and gas properties. Under this method, costs of acquiring properties, drilling successful exploration wells, development costs, and workover costs result in additions to proved properties that are capitalized. The costs of exploratory wells are initially capitalized pending a determination of whether proved reserves have been found. At the completion of drilling activities, the costs of exploratory wells remain capitalized if the determination is made that proved reserves have been found. If no proved reserves have been found, the costs of each of the related exploratory wells are charged to expense. In some cases, a determination of proved reserves cannot be made at the completion of drilling, requiring additional testing and evaluation of the wells. The costs of such exploratory wells are expensed if a determination of proved reserves has not been made within a twelve-month period after drilling is complete. Exploration costs such as geological, geophysical and seismic costs are expensed as incurred.
The capitalized costs of proved properties are depleted using the unit-of-production method based on proved developed or total proved reserves as applicable. Costs of significant non-producing properties, wells in the process of being drilled and prepaid development costs are excluded from depletion until proved reserves are established or, if unsuccessful, impairment is determined.
The carrying value of proved oil and natural gas properties, salt water disposal wells and related facilities, and other property and equipment is periodically evaluated for impairment whenever events or changes in circumstances indicate that the carrying amount of an asset may not be recoverable. When it is determined that the estimated future net cash flows of an asset will not be sufficient to recover its carrying amount, an impairment loss must be recorded to reduce the carrying amount to its estimated fair value.
When a property is impaired the carrying value is reduced to the discounted future net cash flows and an impairment charge of the difference between cost and discounted future net cash flows is recorded. Non-producing properties are considered impaired when the Company considers it likely that the associated leasehold will expire without plans to renew or extend the lease.
Under the Financial Accounting Standards Board (“FASB”) Accounting Standards Codification (“ASC”) Topic 360, the Company evaluates impairment of proved and unproved oil and natural gas properties based on expected future net cash flows from the asset group. As the Company’s properties are managed and evaluated as a single field, impairment testing is performed on that basis. No impairment was recorded during the years ended December 31, 2025 and 2024, respectively.
Other Property, Plant, and Equipment
Other property and equipment consist primarily of vehicles and furniture and fixtures. These items are recorded at cost, and depreciable assets are depreciated under the straight-line method over expected useful lives ranging from three to seven years. Other property and equipment totaled $49,293 and $63,203 net of accumulated depreciation of $26,981 and $13,071 at December 31, 2025 and 2024, respectively. Depreciation expense for other property and equipment totaled $13,910 and $13,071 for the years ended December 31, 2025 and 2024, respectively.
Revenue Recognition
The Company disaggregates revenues from contracts with customers by type of commodity. Upstream revenues include the sale of oil, gas, and natural gas liquids production which are recognized at a point in time when control is transferred to the purchaser upon delivery of contract-specified production volumes at a specified point. Revenue is recognized net of royalties due to third parties in an amount that reflects the consideration the Company expects to receive in exchange for those products. The transaction price used to recognize revenue is a function of the contract billing terms. Revenue is invoiced, if required, by calendar month based on volumes at contractually based rates with payment typically received within 30 days of the end of the production month. Taxes assessed by governmental authorities on oil, gas and NGL sales are presented separately from such revenues in the accompanying statements of operations.
F-75
EQV Resources LLC
Notes to Financial Statements
The Company also evaluates its contracts for the principal/agent provisions. If the Company is determined to be the principal, it would recognize revenue at the gross purchase price and record an expense for certain fees charged by the customer (such as transportation and fractionation fees) incurred prior to the transfer of control, as the Company would still have control of the product when these activities take place. Alternatively, when the Company is determined to be the agent, it recognizes the revenues based on the net price received from the purchaser, as control is determined to have transferred prior to the activities. During this evaluation, the Company concluded that it acts as the agent in all current contracts. Accordingly, revenue is recognized based on the net proceeds received from the purchaser.
Oil Sales
The Company sells its crude oil production at the wellhead for a contractually-specified index price, net of pricing differentials. The Company recognizes revenue when control transfers to the purchaser at the delivery point based on the price received from the purchaser. Oil revenues are recorded net of any third-party transportation fees and other applicable differentials in the Company’s statements of operations.
Natural Gas and NGL Sales
Under the Company’s natural gas processing contracts, natural gas is delivered to a midstream processing entity at the wellhead or the inlet of the midstream processing entity’s system. The midstream processing entity gathers and processes the natural gas and remits proceeds for the resulting sales of NGLs and residue gas. The Company has determined that it is the agent in these transactions and recognizes revenue on a net basis, with transportation, gathering, processing, treating and compression fees as a reduction to revenues in the statements of operations.
Satisfaction of Performance Obligation and Revenue Recognition
Because the Company has a right to consideration from its customers in amounts that correspond directly to the value that the customer receives from the performance completed on each contract, the Company recognizes revenue for sales at the time the crude oil, natural gas, or NGLs are delivered at a fixed or determinable price.
Transaction Price Allocated to Remaining Performance Obligations
The Company’s upstream product sales contracts do not originate until production occurs and, therefore, are not considered to exist beyond each day’s production. Therefore, there are no remaining performance obligations under any of its product sales contracts.
Under the Company’s revenue agreements, each delivery generally represents a separate performance obligation; therefore, future volumes delivered are wholly unsatisfied and disclosure of the transaction price allocated to remaining performance obligations is not required.
Imbalances
The Company is involved in the transportation and sale of natural gas, and, as part of its operations, is subject to natural gas imbalances when pipeline or measurement fluctuations occur. Imbalances are recorded as either an asset or liability depending on the direction of the imbalance. An imbalance asset represents an over-delivery of natural gas relative to the Company’s consumption, while an imbalance liability represents an under-delivery or shortfall in the amount of gas delivered. At December 31, 2025 and December 31, 2024, the Company had a gas imbalance liability of $446,899. The Company anticipates that the imbalance will be settled in the normal course of business through physical delivery or financial settlement with counterparties.
F-76
EQV Resources LLC
Notes to Financial Statements
Contract Balances
Customers can be invoiced once the Company’s performance obligations have been satisfied. Payment terms and conditions vary by contact type, although terms generally include a requirement of payment within 30 days. There are no significant judgments that significantly affect the amount or timing of revenue from contracts with customers. Accordingly, the Company’s product sales contacts do not give rise to material contract assets or contract liabilities.
The Company sells oil and gas to various customers and participates with other parties in the operation of oil and gas wells. Accounts receivable – oil and gas is primarily from the sale of oil, natural gas and natural gas liquids.
The Company routinely assesses the financial strength of its customers and bad debts are recorded based on an account-by-account review specifically identifying receivables that the Company believes may be uncollectible after all means of collection have been exhausted and the potential recovery is considered remote. The Company had no allowance for credit losses at December 31, 2025 and 2024, respectively, based on the expectation that all receivables will be collected. The Company has not realized bad debt expense on accounts receivable during the years ended December 31, 2025 and 2024, respectively.
Debt Issuance Costs
Debt issuance costs incurred in connection with the Company’s borrowings are presented as a reduction of debt and amortized as interest expense using the straight-line method over the maturity of the related borrowings. For the years ended December 31, 2025 and 2024, the Company incurred debt issuance costs of $75,000 and $75,000, respectively, which are classified as a direct reduction from the carrying amount of debt. See Note 7.
Derivative Instruments
The Company’s derivative financial instruments are used to manage commodity price variability. There is risk that the financial benefit of rising commodity prices may not be captured, however, the Company believes the benefits of stable and predictable cash flows outweighs the potential risks.
The Company accounts for derivative financial instruments using fair value accounting and recognizes gains and losses in earnings as other income and expense during the period in which they occur. Unsettled derivative instruments are recorded in the accompanying balance sheets as either a current or non-current asset or liability measured at its fair value. The Company only offsets derivative assets and liabilities with the same counterparty when the right of offset exists. Derivative assets and liabilities with different counterparties are recorded gross on the balance sheets. Cash flows from derivative contract settlements are reflected in operating activities in the accompanying cash flows.
Income Taxes
The Company is organized as a limited liability company and taxed as a partnership for federal income tax purposes. As a result, income or losses are taxable or deductible to the member rather than at the Company level; accordingly, no provision has been made for federal income taxes in the accompanying financial statements. In certain instances, the Company is subject to state taxes on income arising in or derived from the state tax jurisdictions in which it operates.
In accordance with ASC 740, state income tax positions are evaluated in a two-step process. The Company first determines whether it is more likely than not that a tax position will be sustained upon examination. If a tax position meets the more likely than not threshold, it is then measured to determine the amount of expense to record in the financial statements. The tax expense recorded would equal the largest amount of expense related to the outcome that is 50% or greater likely to occur. The Company classifies any potential accrued interest recognized on an underpayment of income taxes as interest expense and classifies any statutory penalties recognized on a tax position taken as operating expense.
F-77
EQV Resources LLC
Notes to Financial Statements
Management of the Company has not taken a tax position that, if challenged, would be expected to have a material effect on the financial statements as of or for the years ended December 31, 2025 or 2024.
The Company did not incur any penalties or interest related to its state tax returns during the years ended December 31, 2025 or 2024.
Reclassifications
Certain historical amounts on the statements of cash flows and balance sheets have been reclassified to conform to the current period presentation.
Recently issued accounting pronouncements not yet adopted
In November 2024, the FASB issued ASU 2024-03, Income Statement – Reporting Comprehensive Income – Expense Disaggregation Disclosures (“Subtopic 220-40”), which expands disclosures around a public entity’s costs and expenses of specific items (i.e., employee compensation, DD&A), requires the inclusion of amounts that are required to be disclosed under GAAP in the same disclosure as other disaggregation requirements, requires qualitative descriptions of amounts remaining in expense captions that are not separately disaggregated quantitatively, and requires disclosure of total selling expenses, and in annual periods, the definition of selling expenses. The amendment does not change or remove existing disclosure requirements. The amendment is effective for fiscal years beginning after December 15, 2026, and interim periods with fiscal years beginning after December 15, 2027. Early adoption is permitted, and the amendment can be adopted prospectively or retrospectively to any or all periods presented in the financial statements. The Company has not early adopted the standard and is currently assessing the effect that ASU 2024-03 will have on its disclosures.
Note 3. Oil and Gas Properties
Oil and gas properties consist of the following at December 31, 2025 and December 31, 2024:
| December 31, | December 31, | |||||||
| 2025 | 2024 | |||||||
| Proved properties | $ | 57,512,710 | $ | 56,459,549 | ||||
| Total Oil and Gas Properties | 57,512,710 | 56,459,549 | ||||||
| Less accumulated depletion | (10,921,512 | ) | (6,018,565 | ) | ||||
| Oil and Gas Properties, Net | $ | 45,591,198 | $ | 50,440,984 | ||||
Note 4. Fair Value Measurements
We classify financial assets and liabilities that are measured and reported at fair value on a recurring basis using a hierarchy based on the inputs used in measuring fair value. GAAP defines fair value as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date (exit price).
F-78
EQV Resources LLC
Notes to Financial Statements
We classify the inputs used to measure fair value into the following hierarchy:
| Level 1 inputs: | Unadjusted, quoted prices in active markets that are accessible at the measurement date for identical, unrestricted assets or liabilities. An active market is defined as a market where transactions for the financial instrument occur with sufficient frequency and volume to provide pricing information on an ongoing basis. | |
| Level 2 inputs: | Inputs, other than quoted prices in active markets that are either directly or indirectly observable for the asset or liability through correlation with market data at the measurement date and for the duration of the instrument’s anticipated life. | |
| Level 3 inputs: | Prices or valuations that require unobservable inputs that are both significant to the fair value measurement and unobservable. Valuation under Level 3 generally involves a significant degree of judgment from management. |
A financial instrument’s level within the fair value hierarchy is based on the lowest level of any input that is significant to the fair value measurement. Where available, fair value is based on observable market prices or parameters or derived from such prices or parameters. Where observable prices or inputs are not available, valuation models are applied. These valuation techniques involve some level of management estimation and judgment, the degree of which is dependent on the price transparency for the instruments or market and the instrument’s complexity. The Company reflects transfers between the three levels at the beginning of the reporting period in which the availability of observable inputs no longer justifies classification in the original level. There were no transfers between fair value hierarchy levels for the years ended December 31, 2025 or 2024, respectively.
Recurring Fair Value Measurements
The following table represents the classification of assets and liabilities measured at fair value on a recurring basis by level:
| Fair Value Measurements at December 31, 2025 | ||||||||||||||||
| Quoted Prices In Active Markets for Identical Assets (Level 1) | Significant Other Observable Inputs (Level 2) | Significant Unobservable Inputs (Level 3) | Fair Value as of December 31, 2025 | |||||||||||||
| Assets | ||||||||||||||||
| Current | ||||||||||||||||
| Commodity Derivatives | - | 2,172,182 | - | 2,172,182 | ||||||||||||
| Assets | ||||||||||||||||
| Non-current | ||||||||||||||||
| Commodity Derivatives | - | 1,037,045 | - | 1,037,045 | ||||||||||||
| Liabilities | ||||||||||||||||
| Current | ||||||||||||||||
| Commodity Derivatives | - | 1,412,544 | - | 1,412,544 | ||||||||||||
| Liabilities | ||||||||||||||||
| Non-current | ||||||||||||||||
| Commodity Derivatives | - | 2,333,859 | - | 2,333,859 | ||||||||||||
| Fair Value Measurements at December 31, 2024 | ||||||||||||||||
| Quoted Prices In Active Markets for Identical Assets (Level 1) | Significant Other Observable Inputs (Level 2) | Significant Unobservable Inputs (Level 3) | Fair Value as of December 31, 2024 | |||||||||||||
| Assets | ||||||||||||||||
| Current | ||||||||||||||||
| Commodity Derivatives | - | 404,996 | - | 404,996 | ||||||||||||
| Assets | ||||||||||||||||
| Non-current | ||||||||||||||||
| Commodity Derivatives | - | 349,992 | - | 349,992 | ||||||||||||
| Liabilities | ||||||||||||||||
| Current | ||||||||||||||||
| Commodity Derivatives | - | 1,982,488 | - | 1,982,488 | ||||||||||||
| Liabilities | ||||||||||||||||
| Non-current | ||||||||||||||||
| Commodity Derivatives | - | 4,400,065 | - | 4,400,065 | ||||||||||||
F-79
EQV Resources LLC
Notes to Financial Statements
Fair value on a Nonrecurring Basis
Oil and gas properties are measured at fair value on a nonrecurring basis. The impairment charge reduces the oil and gas properties’ carrying values to their estimated fair values. These fair value measurements are classified as Level 3 measurements and include many unobservable inputs. Fair value is calculated as the estimated discounted future net cash flows attributable to the assets. The Company’s primary assumptions in preparing the estimated discounted future net cash flows to be recovered from oil and gas properties are based on (i) proved reserves, (ii) forward commodity prices and assumptions as to costs and expenses, and (iii) the estimated discount rate that would be used by potential purchasers to determine the fair value of the assets. For the years ended December 31, 2025 and 2024, the Company did not recognize an impairment on proved properties.
The asset retirement obligation estimates are derived from historical costs and management’s expectation of future cost environments and, therefore, the Company has designated these liabilities as Level 3 measurements. The significant inputs to this fair value measurement include estimates of plugging, abandonment and remediation costs, well life, inflation and credit-adjusted risk-free rate.
Note 5. Derivative Instruments
The Company manages exposure to changes in commodity prices by hedging the impact of market fluctuations by utilizing commodity financial instrument contracts. Commodity swaps are used to manage price risk related to these market exposures. ASC Topic 815, Derivatives and Hedging, requires the Company to recognize all derivative instruments as either assets or liabilities at fair value on the balance sheets. The Company’s swaps were not designated as a hedging instrument and do not qualify for hedge accounting treatment. Gains and losses from adjusting these derivative contracts to fair value are included in the current period income or loss.
Swaps
The Company receives a fixed price or pays a floating market price to the counterparty for the hedged commodity. In exchange for the higher fixed prices on certain swap trades, the Company may sell call options and swap options by the chosen instruments. The Company has entered into swaps with maturities into 2028.
Basis Swaps
These instruments are arrangements that guarantee a fixed price differential to NYMEX or OPIS from a specified delivery point. The Company receives the fixed price differential and pays the floating market price differential to the counterparty for the hedged commodity. The Company has entered basis swaps with maturities through 2026.
F-80
EQV Resources LLC
Notes to Financial Statements
The Company’s amount and fair value of swaps, are summarized as follows:
| As of December 31, 2025 | ||||||||||||||
| Description | Period | Volume | Weighted Average Price | Net Fair Value | ||||||||||
| Oil Swaps (Bbl) | Current | 103,200 | $ | 66.66 | $ | 976,720 | ||||||||
| Non-current | 117,150 | $ | 66.15 | $ | 989,067 | |||||||||
| Natural Gas Swaps (Mbtu) | Current | 3,000,000 | $ | 3.33 | $ | (1,169,303 | ) | |||||||
| Non-current | 5,100,000 | $ | 3.33 | $ | (2,285,881 | ) | ||||||||
| Natural Gas Basis Swaps (Mbtu) | Current | 2,700,000 | $ | (0.26 | ) | $ | 1,026,316 | |||||||
| Non-current | - | $ | - | $ | - | |||||||||
| NGL Swaps (Gal) | Current | 8,001,000 | $ | 0.40 | $ | (74,096 | ) | |||||||
| Non-current | - | $ | - | $ | - | |||||||||
| As of December 31, 2024 | ||||||||||||||
| Description | Period | Volume | Weighted Average Price | Net Fair Value | ||||||||||
| Oil Swaps (Bbl) | Current | 72,000 | $ | 69.43 | $ | (14,016 | ) | |||||||
| Non-current | 220,350 | $ | 66.39 | $ | 159,578 | |||||||||
| Natural Gas Swaps (Mbtu) | Current | 3,075,000 | $ | 3.33 | $ | (595,378 | ) | |||||||
| Non-current | 8,400,000 | $ | 3.33 | $ | (3,816,857 | ) | ||||||||
| Natural Gas Basis Swaps (Mbtu) | Current | 2,800,000 | $ | (0.36 | ) | $ | 124,286 | |||||||
| Non-current | 2,975,000 | $ | (0.19 | ) | $ | 82,340 | ||||||||
| NGL Swaps (Gal) | Current | 11,844,000 | $ | 0.59 | $ | (1,078,034 | ) | |||||||
| Non-current | 8,001,000 | $ | 0.40 | $ | (489,484 | ) | ||||||||
F-81
EQV Resources LLC
Notes to Financial Statements
Note 6. Asset Retirement Obligation
The following are changes in the asset retirement obligation for the years ended December 31, 2025 and December 31, 2024:
| Balance, December 31, 2023 | 14,209,118 | |||
| Revisions of estimate | (8,047,423 | ) | ||
| Settlements | (112,739 | ) | ||
| Accretion expense | 1,420,900 | |||
| Balance, December 31, 2024 | 7,469,856 | |||
| Revisions of estimate | 1,053,160 | |||
| Accretion expense | 747,122 | |||
| Balance, December 31, 2025 | $ | 9,270,138 |
During the year ended December 31, 2025, changes to the Company’s estimates of costs to plug and abandon certain assets and changes in the estimated lives of certain assets resulted in a net increase of recognized asset retirement obligations. During the year ended December 31, 2024, changes to the Company’s estimates of costs to plug and abandon certain assets and changes in the estimated lives of certain assets resulted in a net decrease of recognized asset retirement obligations. At December 31, 2025, all retirement obligations were classified as non-current based on the estimated lives of the Company’s oil and gas properties.
Note 7. Note Payable
On December 13, 2023, the Company entered into a Note Purchase Agreement for a maximum of $50,000,000. Amounts borrowed bear interest at the Secured Overnight Financing Rate (SOFR) plus 6.20%, and is due quarterly. The outstanding principal was $29,602,347 and $33,657,800 as of December 31, 2025 and 2024, respectively. Interest incurred under the Note Purchase Agreement for the years ended December 31, 2025 and 2024 was $3,338,844 and $4,155,905, respectively. At December 31, 2025 and 2024, the interest rate on outstanding notes was 10.50% and 11.05%, respectively.
In conjunction with the Note Purchase Agreement, the Company conveyed an override royalty interest of 1% in the oil and gas properties, and a fair value of $1,493,447 was determined based on discounted cash flows. The interest is presented as a reduction of the outstanding principal on the balance sheets and is amortized over the life of the Note Purchase Agreement. For the years ended December 31, 2025 and 2024, amortization of the conveyance was $373,106 and $374,128, respectively and is included in interest expense on the statements of operations.
Debt issuance costs incurred in connection with the Company’s borrowings are presented as a reduction of debt and amortized as interest expense using the straight-line method over the maturity of the related borrowings, which approximates the effective interest method. The unamortized debt issuance costs balance inclusive of the override royalty conveyance at December 31, 2025 and 2024 was $1,348,735 and $2,058,349, respectively, and total issuance costs amortized during the years ended December 31, 2025 and 2024 was $336,508 and $276,134, respectively, and is included in interest expense on the statements of operations.
F-82
EQV Resources LLC
Notes to Financial Statements
The maturity date of the notes payable is December 13, 2027. Prepayment of the outstanding principal is allowed, subject to certain terms of the Note Purchase Agreement. Additionally, an Excess Cash Sweep, (as defined in the Note Purchase Agreement) is required on a quarterly basis and is based on Cash Flows.
The Note Purchase Agreement is secured by substantially all assets of the Company, and contains certain covenants, including among others, restrictions on indebtedness, restrictions on liens, restrictions on investments, restrictions on acquisitions, and restrictions on the use of note proceeds. The financial covenants require the Company to maintain a Leverage Ratio not greater than 3.50 to 1.00, an Interest Coverage Ratio of greater than 2.50 to 1.00, and PDP Asset Coverage Ratio of at least 1.0 to 1.0.
Note 8. Significant Concentrations
For the year ended December 31, 2025, substantially all of the Company’s operations and business efforts were related to the oil and gas industry. This concentration may impact the Company’s business risk, either positively or negatively, in that commodity prices, customers and suppliers may be similarly affected by changes in economic, political or other conditions related to the industry. The Company sold production to two purchasers whose purchases comprised 57% and 19% of total net oil and gas revenues for the year ended December 31, 2025. The sales to these purchasers accounted for 59% and 16% of total accounts receivable as of December 31, 2025. For the year ended December 31, 2024, the company sold to two purchasers whose purchases comprised 51% and 25% of total net oil and gas revenues. The sales to these purchasers accounted for 58% and 22% of total accounts receivable as of December 31, 2024.
The Company does not believe that the loss of this purchaser would have an adverse effect on its ability to sell its crude oil and natural gas production due to the competitive nature of the oil and gas industry and availability of marketing alternatives.
The Company regularly maintains its cash in bank deposit accounts, which at times, may exceed federally insured limits. The Company has not experienced any losses with respect to the related risks to cash and cash equivalents and does not believe its exposure to such risk is more than nominal.
Note 9. Related Party Transactions
EQV Operating, LLC (EQV Operating) is considered to be a related party under ASC 850, Related Party Disclosures. During 2023, the Company entered into a Contract Operating Agreement (Agreement) with EQV Operating. Under the Agreement, EQV Operating agrees to perform certain specified management and operational services for the Company. The Company paid $2,000,000 and $2,000,000 to EQV Operating related to these services for the years ended December 31, 2025 and 2024, respectively.
Note 10. Commitments and Contingencies
Legal Matters
In the ordinary course of business, the Company may at times be subject to claims and legal actions. Management does not believe the impact of such matters will have a material adverse effect on the Company’s financial position or results of operation. The Company had no legal matters requiring specific disclosure or recognition of a liability as of December 31, 2025 or 2024.
F-83
EQV Resources LLC
Notes to Financial Statements
Environmental
The Company is subject to extensive federal, state and local environmental laws and regulations which may materially affect its operations. These laws, which are constantly changing, regulate the discharge of materials into the environment and may require the Company to remove or mitigate the environmental effects of the disposal or release of petroleum or chemical substances at various sites.
Environmental expenditures are expensed or capitalized depending on their future economic benefit. Expenditures that related to an existing condition caused by past operations and that have no future economic benefits are expensed as incurred. Liabilities for expenditures of a noncapital nature are recorded when environmental assessment and/or remediation is probable, and the cost can be reasonably estimated.
No claim has been made, nor is the Company aware of any liability which the Company may have, as it relates to any environmental cleanup, restoration, or the violation of any rules or regulations relating thereto. The Company maintains comprehensive insurance coverage that it believes is adequate to mitigate the risk of any adverse financial effects associated with these risks.
Note 11. Subsequent Events
The Company has evaluated subsequent events through March 3, 2026, the date the financial statements were available to be issued, and concluded no other events, other than those disclosed in these financial statements, had occurred that would require recognition or disclosure in these financial statements and noted.
Note 12. Supplemental Information of Oil and Natural Gas Producing Activities (unaudited)
The following reserve estimates present the Company’s estimate of the proved natural gas and oil reserves and net cash flow of the Company’s properties, in accordance with the guidelines established by the Securities and Exchange Commission. The Company emphasizes that reserve estimates are inherently imprecise and that estimates of new discoveries are more imprecise than those of producing natural gas and oil properties. Accordingly, the estimates are expected to change as future information becomes available. All the oil and natural gas reserves are located in Texas.
Capitalized oil and natural gas costs
Aggregate capitalized costs related to oil and natural gas production activities with applicable accumulated depreciation, depletion, and amortization are as follows:
| December 31, | December 31, | |||||||
| 2025 | 2024 | |||||||
| Proved properties | $ | 57,512,710 | $ | 56,459,550 | ||||
| Total Oil and Gas Properties | 57,512,710 | 56,459,550 | ||||||
| Less accumulated depletion | (10,921,512 | ) | (6,018,565 | ) | ||||
| Oil and Gas Properties, Net | 46,591,198 | 50,440,985 | ||||||
F-84
EQV Resources LLC
Notes to Financial Statements
Costs incurred in oil and natural gas activities
Costs incurred in oil and natural gas property acquisition, exploration and development activities are as follows:
| As of December 31, | ||||||||
| 2025 | 2024 | |||||||
| Development costs | - | 17,474 | ||||||
| Proved property acquisition cost | - | 904,282 | ||||||
| Total costs incurred | - | 921,756 | ||||||
Reserve quantity information
Proved oil and natural gas reserves are those quantities of oil and gas, which by analysis of geoscience and engineering data, can be estimated with reasonable certainty to be economically producible from a given date forward, from known reservoirs, and under existing economic conditions, operating methods, and government regulations. Proved developed reserves are proved reserves that can be expected to be recovered through existing wells with existing equipment and operating methods or in which the cost of the required equipment is relatively minor compared to the cost of a new well. Proved undeveloped reserves are proved reserves that are expected to be recovered from new wells on undrilled acreage, or from existing wells where a relatively major expenditure is required for recompletion. Below are the net quantities of net proved developed reserves of the Company’s properties:
| (in thousands) | Oil and Condensate | Natural Gas | NGLs | Total Equivalents | ||||||||||||
| Proved Developed and Undeveloped Reserves | (MBbl) | (MMcf) | (MBbl) | (MBOE) | ||||||||||||
| December 31, 2024 | 867 | 42,003 | 4,120 | 11,987 | ||||||||||||
| Revisions of previous estimates | 37 | 3,895 | (152 | ) | 534 | |||||||||||
| Extensions, discoveries and other additions | ||||||||||||||||
| Production | (91 | ) | (4,377 | ) | (369 | ) | (1,190 | ) | ||||||||
| Purchase of reserves | ||||||||||||||||
| Sale of reserves in place | ||||||||||||||||
| December 31, 2025 | 813 | 41,521 | 3,599 | 11,331 | ||||||||||||
| Proved Developed Reserves: | ||||||||||||||||
| December 31, 2024 | 867 | 42,003 | 4,120 | 11,987 | ||||||||||||
| December 31, 2025 | 813 | 41,521 | 3,599 | 11,331 | ||||||||||||
Notable changes in proved reserves for the years ended December 31, 2025 and 2024, respectively, included the following:
| ● | Revisions of Previous Estimates: In 2025, revisions of previous estimates resulted in a net increase of 534 MBoe. Of this reduction, 1,156 MMBoe was attributable to lower SEC pricing, counteracted by other revisions resulting in a decrease of 622 MBOE. |
| ● | Revisions of Previous Estimates: In 2024, revisions of previous estimates resulted in a net decrease of 820 MBoe. Of this reduction, 876 MMBoe was attributable to lower SEC pricing, counteracted by improvements in recovery resulting in an additional 56 MBOE. |
F-85
EQV Resources LLC
Notes to Financial Statements
Standardized measure of discounted future net cash flows relating to oil and natural gas reserves
The standardized measure of discounted future net cash flows relating to oil and natural gas reserves and associated changes in standard measure amounts were prepared in accordance with the provision of FASB ASC 932-235-55, Extractive Activities – Oil and Gas (“Topic 932”). Future cash inflows were computed by applying average prices of oil and natural gas for the last 12 months to estimated future production. Future production and development costs were computed by estimating the expenditures to be incurred in developing, producing, and plugging and abandoning the proved reserves at year-end, based on year-end costs and assuming continuation of existing economic conditions. Future net cash flows are discounted at the rate of 10% annually to derive the standardized measure of discounted cash flows. Actual future cash inflows may vary considerably, and the standardized measure does not necessarily represent the fair value of the acquired properties’ oil and natural gas reserves.
Standard measure amounts are:
| Year Ended December 31, | ||||||||
| (in thousands) | 2025 | 2024 | ||||||
| Future cash inflows | $ | 250,885 | $ | 196,799 | ||||
| Future production costs | (132,921 | ) | (97,833 | ) | ||||
| Future development costs | (24,791 | ) | (20,581 | ) | ||||
| Future net cash flows before income tax | $ | 93,223 | $ | 78,385 | ||||
| Future income tax expense | - | - | ||||||
| Future net cash flows | $ | 93,223 | $ | 78,385 | ||||
| 10% annual discount for estimated timing of cash flows | (37,027 | ) | (27,694 | ) | ||||
| Standardized measure of discounted future net cash flows | $ | 56,146 | $ | 50,692 | ||||
F-86
EQV Resources LLC
Notes to Financial Statements
Changes in the Standardized Measure of Discounted Future Net Cash Flows at 10% per annum are as follows:
| Year Ended December 31, | ||||||||
| (in thousands) | 2025 | 2024 | ||||||
| Sales of oil and gas, net of production costs | $ | (8,978 | ) | $ | (10,513 | ) | ||
| Net changes in prices and production costs | 15,505 | (15,751 | ) | |||||
| Changes in future development costs | - | - | ||||||
| Extensions, discoveries and other additions | - | - | ||||||
| Development costs incurred during the period | - | - | ||||||
| Revisions of previous quantity estimates | 3,595 | (4,189 | ) | |||||
| Purchases of reserves-in-place | - | - | ||||||
| Sale of reserves-in-place | - | - | ||||||
| Changes in production rates | (9,736 | ) | (1,340 | ) | ||||
| Accretion of discount | 5,069 | 7,499 | ||||||
| Net change in income taxes | - | - | ||||||
| Other changes | - | - | ||||||
| Net increase (decrease) | $ | 5,454 | $ | (24,294 | ) | |||
| Beginning of year | 50,692 | 74,986 | ||||||
| End of year | $ | 56,146 | $ | 50,692 | ||||
Estimates of economically recoverable natural gas and oil reserves and of future net revenues are based upon a number of variable factors and assumptions, all of which are to some degree subjective and may vary considerably from actual results. Therefore, actual production, revenues, development and operating expenditures may not occur as estimated. The reserve data are estimates only, are subject to many uncertainties, and are based on data gained from production histories and on assumptions as to geologic formations and other matters. Actual quantities of natural gas and oil may differ materially from the amounts estimated.
F-87
GRANT THORNTON LLP 500 N. Akard, Suite 1200 Dallas, TX 75201
| REPORT OF INDEPENDENT CERTIFIED PUBLIC ACCOUNTANTS |
D +1 214 561 2300
F +1 214 561 2370
Board of Directors
Presidio Production Company
Opinion
We have audited the Combined Statement of Revenues and Direct Operating Expenses attributable to certain mineral and royalty interests (collectively, the “Arkoma Acquired Properties,” as described in Note 1), for the year ended December 31, 2025, and the related notes to the combined statement.
In our opinion, the accompanying combined statement presents fairly, in all material respects, the revenues and direct operating expenses of the Arkoma Acquired Properties for the year ended December 31, 2025, in accordance with accounting principles generally accepted in the United States of America.
Basis for opinion
We conducted our audit of the combined statement in accordance with auditing standards generally accepted in the United States of America (US GAAS). Our responsibilities under those standards are further described in the Auditor’s Responsibilities for the Audit of the Combined Statement section of our report. We are required to be independent of the Arkoma Acquired Properties and to meet our other ethical responsibilities in accordance with the relevant ethical requirements relating to our audit. We believe that the audit evidence we have obtained is sufficient and appropriate to provide a basis for our audit opinion.
Emphasis of matter – basis of accounting
We draw attention to Note 1 to the Combined Statement of Revenues and Direct Operating Expenses, which describes that the accompanying Combined Statement of Revenues and Direct Operating Expenses was prepared for the purpose of a filing requirement of the United States Securities and Exchange Commission and is not intended to be a complete presentation of the Arkoma Acquired Properties’ revenues and expenses. As a result, the combined statement may not be suitable for another purpose. Our opinion is not modified with respect to this matter.
Responsibilities of management for the combined statement
Management is responsible for the preparation and fair presentation of the Combined Statement of Revenues and Direct Operating Expenses in accordance with accounting principles generally accepted in the United States of America, and for the design, implementation, and maintenance of internal control relevant to the preparation and fair presentation of the combined statement that are free from material misstatement, whether due to fraud or error.
| GT.COM | Grant Thornton LLP is a U.S. member firm of Grant Thornton International Ltd (GTIL). GTIL and each of its member firms are separate legal entities and are not a worldwide partnership. |
F-88
Auditor’s responsibilities for the audit of the combined statement
Our objectives are to obtain reasonable assurance about whether the Combined Statement of Revenues and Direct Operating Expenses as a whole are free from material misstatement, whether due to fraud or error, and to issue an auditor’s report that includes our opinion. Reasonable assurance is a high level of assurance but is not absolute assurance and therefore is not a guarantee that an audit conducted in accordance with US GAAS will always detect a material misstatement when it exists. The risk of not detecting a material misstatement resulting from fraud is higher than for one resulting from error, as fraud may involve collusion, forgery, intentional omissions, misrepresentations, or the override of internal control. Misstatements are considered material if there is a substantial likelihood that, individually or in the aggregate, they would influence the judgment made by a reasonable user based on the combined statement.
In performing an audit in accordance with US GAAS, we:
| ● | Exercise professional judgment and maintain professional skepticism throughout the audit. | |
| ● | Identify and assess the risks of material misstatement of the Combined Statement of Revenue and Direct Operating Expenses, whether due to fraud or error, and design and perform audit procedures responsive to those risks. Such procedures include examining, on a test basis, evidence regarding the amounts and disclosures in the Combined Statement of Revenue and Direct Operating Expenses. | |
| ● | Obtain an understanding of internal control relevant to the audit in order to design audit procedures that are appropriate in the circumstances, but not for the purpose of expressing an opinion on the effectiveness of the Arkoma Acquired Properties’ internal control. Accordingly, no such opinion is expressed. | |
| ● | Evaluate the appropriateness of accounting policies used and the reasonableness of significant accounting estimates made by management, as well as evaluate the overall presentation of the Combined Statement of Revenue and Direct Operating Expenses. |
We are required to communicate with those charged with governance regarding, among other matters, the planned scope and timing of the audit, significant audit findings, and certain internal control-related matters that we identified during the audit.
Dallas, Texas
September 17, 2026
F-89
ARKOMA ACQUIRED PROPERTIES
COMBINED STATEMENT OF REVENUES AND DIRECT OPERATING EXPENSES
| $ in thousands | Year Ended December 31, 2025 | |||
| Revenues: | ||||
| Oil sales | $ | 543 | ||
| Natural gas sales | 18,222 | |||
| Natural gas liquids sales | 9,663 | |||
| Total revenues | 28,428 | |||
| Direct operating expenses: | ||||
| Lease operating expenses | 3,342 | |||
| Production taxes | 1,662 | |||
| Gathering, compression and transportation | 5,126 | |||
| Total operating expenses | 10,130 | |||
| Excess of revenues over direct operating expenses | $ | 18,298 | ||
See accompanying Notes to the Combined Statement of Revenues and Direct Operating Expenses
F-90
ARKOMA ACQUIRED PROPERTIES
NOTES TO THE COMBINED STATEMENT OF REVENUES AND DIRECT OPERATING EXPENSES
1. Background Information and Basis of Presentation
On July 1, 2026, Presidio Production Company (NYSE: FTW) (“Presidio” or the “Company”) completed its acquisition of certain oil and gas properties, rights, and related assets located in the Arkoma Basin in the State of Oklahoma (the “Arkoma Acquisition”) from Canyon Creek Energy – Arkoma, LLC (“Canyon Creek”), Alchemist Energy LeaseCo, LP, Pivotal Arkoma Basin II, LLC, East Dennis Oil Company, LLC, Harvard Petroleum Company, LLC, and FBF Energy, LLC and together with the completion of the acquisition from Harbor Island, LLC which closed on July 21, 2026 (collectively, the “Seller Parties”), pursuant to seven separate Purchase and Sale Agreements, each dated as of May 7, 2026 (individually, the “PSA” or collectively, the “PSAs”). Total consideration paid consisted of approximately $53.1 million in cash and 1,962,240 shares of the Company’s Class A common stock, par value $0.0001 per share. The cash was funded by the closing of the previously announced $1.0 billion GS Warehouse and cash on hand.
The accompanying Combined Statement of Revenues and Direct Operating Expenses (the “Statement”) presents the direct undivided interests in oil, natural gas and natural gas liquids (“NGL”) revenues and direct operating expenses associated with the producing wells acquired from the Seller Parties (the “Arkoma Acquired Properties”). The Statement has been derived from the historical financial records of the Seller. The acquisition of the Arkoma Acquired Properties was completed contemporaneously with, and was cross-conditioned upon, the closing under the Canyon Creek PSA.
During the period presented, the Arkoma Acquired Properties were not accounted for or operated as a separate entity, subsidiary, segment or division by the Seller. The Statement was prepared for the purpose of providing historical information to comply with the rules and regulations of the Securities and Exchange Commission under Rule 3-05 of Regulation S-X and are not intended to be a complete presentation of the financial statements of the Assets. Accordingly, a complete set of financial statements required by the Securities and Exchange Commission’s Regulation S-X, including a balance sheet and statement of cash flows, prepared in accordance with accounting principles generally accepted in the United States of America (“U.S. GAAP”) is not available or practicable to prepare for the Arkoma Acquired Properties. The accompanying Statement varies from a complete income statement in accordance with U.S. GAAP in that it does not reflect certain expenses incurred in connection with the ownership and operation of the Arkoma Acquired Properties, including but not limited to depreciation, depletion and amortization, accretion of asset retirement obligations, general and administrative expenses, interest expense, and provision for income taxes. In addition, the Statement is not indicative of the results of operations for the Arkoma Acquired Properties on a go forward basis.
2. Summary of Significant Accounting Policies
Revenue Recognition
Revenue from the sale of oil, natural gas and NGLs is recognized in accordance with Financial Accounting Standards Board Accounting Standards Codification (“ASC”) Topic 606, Revenue from Contracts with Customers, at the point in time when control of the production transfers to the purchaser upon delivery of contract-specified volumes at a specified delivery point. Each unit of production—a barrel of oil, an Mcf or MMBtu of natural gas, or a barrel of NGLs—is separately identifiable and represents a distinct performance obligation to which the transaction price, based on the consideration specified in the contract, is allocated. Because the Company has a right to consideration from its customers in amounts that correspond directly to the value the customer receives from the performance completed, the Company recognizes revenue for sales at the time the oil, natural gas or NGLs are delivered at a fixed or determinable price, and there are no remaining performance obligations under its product sales contracts.
F-91
Gathering, compression, transportation, processing and treating costs incurred prior to the transfer of control of production to the purchaser represent costs of the Company’s operations and are presented separately as gathering, compression and transportation expense, and are not deducted in determining revenues. Fees for gathering, transportation, processing, treating and compression services performed by the purchaser or other parties after control of the production has transferred at the delivery point are considered a reduction of the transaction price and, accordingly, oil revenues are recorded net of such fees and applicable price differentials, and natural gas and NGL revenues are recorded net of such fees deducted by the midstream purchaser. Taxes assessed by governmental authorities on the production and sale of oil, natural gas and NGLs are presented separately as direct operating expenses and are not deducted in determining revenues. Revenues are presented net of royalty interests owned by outside parties.
Direct Operating Expenses
Direct operating expenses are recognized when incurred and include lease operating expenses and production, severance and ad valorem taxes directly associated with operating the Arkoma Acquired Properties. Transportation, gathering, processing, treating and compression fees are reflected as a reduction of revenues rather than as direct operating expenses.
Concentration of Risk
The revenues of the Arkoma Acquired Properties are derived principally from a small number of purchasers of oil, natural gas and NGLs. For the year ended December 31, 2025, one purchaser accounted for more than 10% of total revenues, representing approximately 94% of total revenues. All of the Arkoma Acquired Properties are located in the Arkoma Basin in Oklahoma, and the revenues and direct operating expenses presented are subject to risks arising from this geographic concentration, including regional price differentials and the availability of gathering, processing and transportation capacity. Management believes the loss of any single purchaser would not have a material adverse effect on the revenues of the Arkoma Acquired Properties, as alternative purchasers are available in the area.
3. Commitments and Contingencies
In the ordinary course of business, the Arkoma Acquired Properties may be subject to various commitments, claims and contingencies. Management is not aware of any commitments or contingencies that would have a material effect on the revenues and direct operating expenses of the Arkoma Acquired Properties for the period presented.
4. Subsequent Events
The Arkoma Acquisition closed on July 1, 2026, pursuant to the terms of the PSA. The Company evaluated subsequent events through September 17, 2026, the date the Statement was available to be issued, and has concluded that no other events need to be reported for this period, other than the closing of the Arkoma Acquisition described in Note 1.
F-92
ARKOMA ACQUIRED PROPERTIES
5. Supplemental Oil and Natural Gas Disclosures (Unaudited)
Oil, Natural Gas and NGL Reserve Quantities
The unaudited supplemental information on oil and natural gas exploration and production activities related to the Arkoma Acquired Properties has been prepared in accordance with ASC Topic 932, Extractive Activities—Oil and Gas, and the Securities and Exchange Commission’s final rule, Modernization of Oil and Gas Reporting, based on the 12-month unweighted first-day-of-the-month average prices as of December 31, 2025, with appropriate adjustments by property for location, quality, and gathering and marketing differentials. The applicable benchmark prices were $65.34 per barrel (NYMEX WTI Cushing) for oil and $3.39 per MMBtu (Henry Hub) for natural gas. NGL pricing was determined using ethane-rejection mode - that is, ethane is assumed to remain in and be sold with the natural gas stream rather than recovered as a liquid, consistent with current processing economics. Reported NGL volumes and prices therefore reflect only the heavier natural gas liquids. Consistent with the basis of presentation described in Note 1, these supplemental disclosures are limited to reserve quantities and the Standardized Measure. Certain other disclosures otherwise required by ASC Topic 932 — including general and administrative expenses, capitalized costs relating to oil and gas producing activities, costs incurred in oil and gas property acquisition, exploration and development activities, and results of operations for oil and gas producing activities — are not presented because the Arkoma Acquired Properties were not accounted for or operated as a separate entity, subsidiary, segment or division by the Seller, and the historical cost basis information necessary to prepare those disclosures is not available or practicable to prepare.
Proved reserves are estimated quantities of oil and natural gas which geological and engineering data demonstrate with reasonable certainty to be recoverable in future years from known reservoirs under existing economic, governmental regulations and operating conditions. Proved developed reserves are those which are expected to be recovered through existing wells with existing equipment and operating methods. The proved oil, natural gas and NGL reserves disclosed below have been independently prepared by Pinnacle Energy Services, LLC. No proved undeveloped reserves and no unproved properties were acquired in the Arkoma Acquisition, and accordingly no proved undeveloped reserve quantities or unproved property disclosures are presented herein.
Below are the net quantities of estimated total proved, proved developed and proved undeveloped reserves of the Arkoma Acquired Properties, all of which are located within the United States:
Oil (MBbls) | NGL (MBbls) | Natural Gas (MMcf) | Total (MBoe) | |||||||||||||
| Proved developed and undeveloped reserves: | ||||||||||||||||
| As of December 31, 2024 | 55 | 5,952 | 83,415 | 19,910 | ||||||||||||
| Revisions of previous estimates | 7 | 313 | 2,965 | 814 | ||||||||||||
| Extensions, discoveries and other additions | — | — | — | — | ||||||||||||
| Purchases of reserves in place | — | — | — | — | ||||||||||||
| Sales of reserves in place | — | — | — | — | ||||||||||||
| Production | (8 | ) | (445 | ) | (6,185 | ) | (1,484 | ) | ||||||||
| As of December 31, 2025 | 54 | 5,820 | 80,195 | 19,240 | ||||||||||||
| Proved developed reserves: | ||||||||||||||||
| As of December 31, 2024 | 55 | 5,952 | 83,415 | 19,910 | ||||||||||||
| As of December 31, 2025 | 54 | 5,820 | 80,195 | 19,240 | ||||||||||||
| Proved undeveloped reserves: | ||||||||||||||||
| As of December 31, 2024 | — | — | — | — | ||||||||||||
| As of December 31, 2025 | — | — | — | — | ||||||||||||
F-93
Notable changes in proved reserves for the year ended December 31, 2025 included the following:
| ● | Extensions and Discoveries: The Arkoma Acquired Properties had no extensions or discoveries in 2025. |
| ● | Revisions of Previous Estimates: The Arkoma Acquired Properties saw upward revisions of previous estimates based on increased pricing in 2025 resulting in approximately a net increase of 814 MBoe which was offset by the natural decline curve of the wells. |
Standardized Measure of Discounted Future Net Cash Flows
The standardized measure of discounted future net cash flows related to proved reserves (“Standardized Measure”) is a disclosure requirement under ASC 932-235. The Standardized Measure does not purport to be, nor should it be interpreted to present, the fair value of the proved reserves of the Arkoma Acquired Properties. Estimated future net cash flows presented are reduced by estimated future production costs and future development and abandonment costs based on existing costs, assuming continuation of existing economic conditions. The estimated future net cash flows are then discounted at a rate of 10%. Tax rate is based on franchise tax, therefore overall immaterial. No deduction has been made for general and administrative expenses, interest expense, or depreciation, depletion and amortization.
The Standardized Measure of the Arkoma Acquired Properties is presented below ($ in thousands):
| $ in thousands | December 31, 2025 | |||
| Future cash inflows from production | $ | 298,439 | ||
| Future production costs | (60,054 | ) | ||
| Future development and abandonment costs | (1,689 | ) | ||
| Future net cash flows before income taxes | 236,696 | |||
| Future income tax expenses | — | |||
| Undiscounted future net cash flows | 236,696 | |||
| 10% annual discount for estimated timing of cash flows | (132,325 | ) | ||
| Standardized Measure of discounted future net cash flows | $ | 104,371 | ||
Changes in the Standardized Measure of the Arkoma Acquired Properties are as follows ($ in thousands):
| $ in thousands | Year Ended December 31, 2025 | |||
| Standardized Measure — beginning of year | $ | 69,799 | ||
| Sales of oil and gas, net of production costs | (18,298 | ) | ||
| Net changes in prices and production costs | 45,137 | |||
| Changes in future development costs | (67 | ) | ||
| Extensions, discoveries and other additions | — | |||
| Development costs incurred during the period | — | |||
| Revisions of previous quantity estimates | 4,767 | |||
| Purchases of reserves in place | — | |||
| Sales of reserves in place | — | |||
| Accretion of discount | 6,980 | |||
| Net change in income taxes | — | |||
| Changes in timing and other | (3,947 | ) | ||
| Net change for the year | 34,572 | |||
| Standardized Measure — end of year | $ | 104,371 | ||
Prices Used in the Standardized Measure
The following table presents the SEC prices, as adjusted for location and quality differentials and contractual arrangements, used in the computation of future cash inflows:
| December 31, 2025 | ||||
| Oil (per Bbl) | $ | 63.21 | ||
| Natural gas (per Mcf) | $ | 1.73 | ||
| Natural gas liquids (per Bbl) | $ | 25.71 | ||
F-94
ARKOMA ACQUIRED PROPERTIES
COMBINED STATEMENT OF REVENUES AND DIRECT OPERATING EXPENSES (UNAUDITED)
| $ in thousands | Six Months Ended June 30, 2026 | |||
| Revenues: | ||||
| Oil sales | $ | 276 | ||
| Natural gas sales | 8,406 | |||
| Natural gas liquids sales | 4,584 | |||
| Total revenues | 13,266 | |||
| Direct operating expenses: | ||||
| Lease operating expenses | 1,630 | |||
| Production taxes | 796 | |||
| Gathering, compression and transportation | 2,323 | |||
| Total operating expenses | 4,749 | |||
| Excess of revenues over direct operating expenses | $ | 8,517 | ||
See accompanying Notes to the Combined Statement of Revenues and Direct Operating Expenses
F-95
ARKOMA ACQUIRED PROPERTIES
NOTES TO THE STATEMENT OF REVENUES AND DIRECT OPERATING EXPENSES (UNAUDITED)
1. Background Information and Basis of Presentation
On July 1, 2026, Presidio Production Company (NYSE: FTW) (“Presidio” or the “Company”) completed its acquisition of certain oil and gas properties, rights, and related assets located in the Arkoma Basin in the State of Oklahoma (the “Arkoma Acquisition”) from Canyon Creek Energy – Arkoma, LLC (“Canyon Creek”), Alchemist Energy LeaseCo, LP, Pivotal Arkoma Basin II, LLC, East Dennis Oil Company, LLC, Harvard Petroleum Company, LLC, and FBF Energy, LLC and together with the completion of the acquisition from Harbor Island, LLC which closed on July 21, 2026 (collectively, the “Seller Parties”), pursuant to seven separate Purchase and Sale Agreements, each dated as of May 7, 2026 (individually, the “PSA” or collectively, the “PSAs”). Total consideration paid consisted of approximately $53.1 million in cash and 1,962,240 shares of the Company’s Class A common stock, par value $0.0001 per share. The cash was funded by the closing of the previously announced $1.0 billion GS Warehouse and cash on hand.
The accompanying unaudited combined Statement presents the direct undivided interests in oil, natural gas and natural gas liquids (“NGL”) revenues and direct operating expenses associated with the producing wells acquired from the Seller Parties (the “Arkoma Acquired Properties”) for the six months ended June 30, 2026. The Statement has been derived from the historical financial records of the Seller. The acquisition of the Arkoma Acquired Properties was completed contemporaneously with, and was cross-conditioned upon, the closing under the Canyon Creek PSA. In the opinion of management, the Statement includes all adjustments, consisting of normal recurring adjustments, necessary for a fair statement of the combined revenues and direct operating expenses of the Arkoma Acquired Properties for the interim period presented.
During the period presented, the Arkoma Acquired Properties were not accounted for or operated as a separate entity, subsidiary, segment or division by the Seller. The Statement was prepared for the purpose of providing historical information to comply with the rules and regulations of the Securities and Exchange Commission under Rule 3-05 of Regulation S-X and are not intended to be a complete presentation of the financial statements of the Assets. Accordingly, a complete set of financial statements required, if available, by the Securities and Exchange Commission’s Regulation S-X, including a balance sheet and statement of cash flows, prepared in accordance with accounting principles generally accepted in the United States of America (“U.S. GAAP”) is not available or practicable to prepare for the Arkoma Acquired Properties. The accompanying Statement varies from a complete income statement in accordance with U.S. GAAP in that it does not reflect certain expenses incurred in connection with the ownership and operation of the Arkoma Acquired Properties, including but not limited to depreciation, depletion and amortization, accretion of asset retirement obligations, general and administrative expenses, interest expense, and provision for income taxes. In addition, the Statement is not indicative of the results of operations for the Arkoma Acquired Properties on a go forward basis.
2. Summary of Significant Accounting Policies
Revenue Recognition
Revenue from the sale of oil, natural gas and NGLs is recognized in accordance with Financial Accounting Standards Board Accounting Standards Codification (“ASC”) Topic 606, Revenue from Contracts with Customers, at the point in time when control of the production transfers to the purchaser upon delivery of contract-specified volumes at a specified delivery point. Each unit of production—a barrel of oil, an Mcf or MMBtu of natural gas, or a barrel of NGLs—is separately identifiable and represents a distinct performance obligation to which the transaction price, based on the consideration specified in the contract, is allocated. Because the Company has a right to consideration from its customers in amounts that correspond directly to the value the customer receives from the performance completed, the Company recognizes revenue for sales at the time the oil, natural gas or NGLs are delivered at a fixed or determinable price, and there are no remaining performance obligations under its product sales contracts.
F-96
Gathering, compression, transportation, processing and treating costs incurred prior to the transfer of control of production to the purchaser represent costs of the Company’s operations and are presented separately as gathering, compression and transportation expense, and are not deducted in determining revenues. Fees for gathering, transportation, processing, treating and compression services performed by the purchaser or other parties after control of the production has transferred at the delivery point are considered a reduction of the transaction price and, accordingly, oil revenues are recorded net of such fees and applicable price differentials, and natural gas and NGL revenues are recorded net of such fees deducted by the midstream purchaser. Taxes assessed by governmental authorities on the production and sale of oil, natural gas and NGLs are presented separately as direct operating expenses and are not deducted in determining revenues. Revenues are presented net of royalty interests owned by outside parties.
Direct Operating Expenses
Direct operating expenses are recognized when incurred and include lease operating expenses and production, severance and ad valorem taxes directly associated with operating the Arkoma Acquired Properties. Transportation, gathering, processing, treating and compression fees are reflected as a reduction of revenues rather than as direct operating expenses.
Concentration of Risk
The revenues of the Arkoma Acquired Properties are derived principally from a small number of purchasers of oil, natural gas and NGLs. For the six months ended June 30, 2026, one purchaser accounted for more than 10% of total revenues, representing approximately 92% of total revenues. All of the Arkoma Acquired Properties are located in the Arkoma Basin in Oklahoma, and the revenues and direct operating expenses presented are subject to risks arising from this geographic concentration, including regional price differentials and the availability of gathering, processing and transportation capacity. Management believes the loss of any single purchaser would not have a material adverse effect on the revenues of the Arkoma Acquired Properties, as alternative purchasers are available in the area.
3. Commitments and Contingencies
In the ordinary course of business, the Arkoma Acquired Properties may be subject to various commitments, claims and contingencies. Management is not aware of any commitments or contingencies that would have a material effect on the revenues and direct operating expenses of the Arkoma Acquired Properties for the period presented.
4. Subsequent Events
The Arkoma Acquisition closed on July 1, 2026, pursuant to the terms of the PSAs. The Company evaluated subsequent events through September 17, 2026, the date the Statement was available to be issued, and has concluded that no other events need to be reported for this period.
F-97
PART II
INFORMATION NOT REQUIRED IN PROSPECTUS
Item 13. Other Expenses of Issuance and Distribution
The following table sets forth the estimated expenses to be borne by the registrant in connection with the issuance and distribution of the securities being registered hereby.
| Amount to be paid | ||||
| SEC registration fee | $ | 3,181.37 | ||
| Accounting fees and expenses | * | |||
| Legal fees and expenses | * | |||
| Printing and miscellaneous expenses | * | |||
| Total | $ | * | ||
| * | These fees are calculated based on the securities offered and the number of issuances and accordingly cannot be determined at this time. |
Item 14. Indemnification of Directors and Officers
The Certificate of Incorporation contains provisions that limit the liability of the Presidio directors for monetary damages to the fullest extent permitted by Delaware law. Consequently, Presidio’s directors will not be personally liable to Presidio or its stockholders for monetary damages for any breach of fiduciary duties as directors, except liability for:
| ● | any breach of the director’s duty of loyalty to Presidio or its stockholders; |
| ● | any act or omission not in good faith or that involves intentional misconduct or a knowing violation of law; |
| ● | unlawful payments of dividends or unlawful stock repurchases or redemptions as provided in Section 174 of the DGCL; or |
| ● | any transaction from which the director derived an improper personal benefit. |
The Certificate of Incorporation and our Bylaws provide that Presidio is required to indemnify our directors and officers, in each case to the fullest extent permitted by Delaware law. The Certificate of Incorporation also provides that Presidio is obligated to advance expenses incurred by a director or officer in advance of the final disposition of any action or proceeding, and permit Presidio to secure insurance on behalf of any officer, director, employee or other agent for any liability arising out of his or her actions in that capacity regardless of whether Presidio would otherwise be permitted to indemnify him or her under Delaware law. Presidio has entered into agreements to indemnify its directors, executive officers and other employees. With specified exceptions, these agreements provide for indemnification for related expenses including, among other things, attorneys’ fees, judgments, fines and settlement amounts incurred by any of these individuals in any action or proceeding. Presidio will also maintain directors’ and officers’ liability insurance.
Item 15. Recent Sales of Unregistered Securities
During the past three years, we have issued the following securities that were not registered under the Securities Act, in reliance upon the exemption provided in Section 4(a)(2) thereof.
Arkoma Acquisition
In connection with the Arkoma Acquisition, on July 1, 2026, we issued an aggregate 1,930,156 shares of Presidio Class A Common Stock, and on July 20, 2026, we issued 32,084 shares of Presidio Class A Common Stock, in each case, to the Seller Parties as partial consideration for the acquisition of certain oil and gas properties in Oklahoma pursuant to the Purchase and Sale Agreements, dated May 7, 2026.
Founder Shares and Private Placement Units
In connection with EQV’s initial public offering, the Sponsor purchased Class B ordinary shares of EQV (the “Founder Shares”) for an aggregate purchase price of $25,000 and 400,000 private placement units at a purchase price of $10.00 per unit for an aggregate purchase price of $4,000,000. In connection with the Business Combination, such securities converted into shares of Presidio Class A Common Stock and Private Placement Warrants on March 4, 2026.
II-1
PIPE Financing
In connection with the Business Combination, we entered into subscription agreements with certain investors pursuant to which, on March 4, 2026, we issued an aggregate of 8,750,000 shares of Presidio Class A Common Stock at $10.00 per share for aggregate gross proceeds of $87,500,000. In addition, 565,217 shares of Presidio Class A Common Stock were issued in connection with the Class B Contribution.
Series A Preferred Financing
In connection with the Business Combination, on March 4, 2026, we issued 125,000 shares of Series A Preferred Stock at a stated value of $1,000 per share and warrants to purchase 937,500 shares of Presidio Class A Common Stock at an exercise price of $0.01 per share to the Series A Preferred Investors.
Series B Preferred Financing
In connection with the Business Combination, on March 4, 2026, we issued 27,173 shares of Series B Preferred Stock at a stated value of $1,000 per share to the Series B Preferred Investor.
Item 16. Exhibits and Financial Statements Schedules
| (a) | Exhibits. |
II-2
II-3
| + | Management contract or compensatory plan or arrangement. |
| # | Schedules and exhibits to these Exhibits omitted pursuant to Regulation S-K Item 601(a)(5). The registrant agrees to furnish supplementally a copy of any omitted schedule or exhibit to the SEC upon request. |
| * | Filed herewith. |
| ** | Previously filed. |
Item 17. Undertakings
| 1. | The undersigned registrant hereby undertakes: |
| (a) | To file, during any period in which offers or sales are being made, a post-effective amendment to this registration statement: |
| (i) | To include any prospectus required by section 10(a)(3) of the Securities Act of 1933; |
| (ii) | To reflect in the prospectus any facts or events arising after the effective date of this registration statement (or the most recent post-effective amendment thereof) which, individually or in the aggregate, represent a fundamental change in the information set forth in this registration statement. Notwithstanding the foregoing, any increase or decrease in volume of securities offered (if the total dollar value of securities offered would not exceed that which was registered) and any deviation from the low or high end of the estimated maximum offering range may be reflected in the form of prospectus filed with the Commission pursuant to Rule 424(b) if, in the aggregate, the changes in volume and price represent no more than a 20% change in the maximum aggregate offering price set forth in the “Calculation of Filing Fee Table” table in the effective registration statement; and |
| (iii) | To include any material information with respect to the plan of distribution not previously disclosed in this registration statement or any material change to such information in this registration statement. |
II-4
| (b) | That, for the purpose of determining any liability under the Securities Act of 1933, each such post-effective amendment shall be deemed to be a new registration statement relating to the securities offered therein, and the offering of such securities at that time shall be deemed to be the initial bona fide offering thereof. |
| (c) | To remove from registration by means of a post-effective amendment any of the securities being registered which remain unsold at the termination of the offering. |
| (d) | That, for the purpose of determining liability under the Securities Act of 1933 to any purchaser, if the registrant is subject to Rule 430C each prospectus filed pursuant to Rule 424(b) as part of a registration statement relating to an offering, other than registration statements relying on Rule 430B or other than prospectuses filed in reliance on Rule 430A, shall be deemed to be part of and included in the registration statement as of the date it is first used after effectiveness. Provided, however, that no statement made in a registration statement or prospectus that is part of the registration statement or made in a document incorporated or deemed incorporated by reference into the registration statement or prospectus that is part of the registration statement will, as to a purchaser with a time of contract of sale prior to such first use, supersede or modify any statement that was made in the registration statement or prospectus that was part of the registration statement or made in any such document immediately prior to such date of first use. |
| (e) | That, for the purpose of determining liability of the registrant under the Securities Act of 1933 to any purchaser in the initial distribution of the securities, the undersigned registrant undertakes that in a primary offering of securities of the undersigned registrant pursuant to this registration statement, regardless of the underwriting method used to sell the securities to the purchaser, if the securities are offered or sold to such purchaser by means of any of the following communications, the undersigned registrant will be a seller to the purchaser and will be considered to offer or sell such securities to such purchaser: |
| (i) | Any preliminary prospectus or prospectus of the undersigned registrant relating to the offering required to be filed pursuant to Rule 424; |
| (ii) | Any free writing prospectus relating to the offering prepared by or on behalf of the undersigned registrant or used or referred to by the undersigned registrant; |
| (iii) | The portion of any other free writing prospectus relating to the offering containing material information about the undersigned registrant or its securities provided by or on behalf of the undersigned registrant; and |
| (iv) | Any other communication that is an offer in the offering made by the undersigned registrant to the purchaser. |
| 2. | Insofar as indemnification for liabilities arising under the Securities Act of 1933 may be permitted to directors, officers and controlling persons of the registrant pursuant to the foregoing provisions, or otherwise, the registrant has been advised that in the opinion of the SEC such indemnification is against public policy as expressed in the Securities Act of 1933 and is, therefore, unenforceable. In the event that a claim for indemnification against such liabilities (other than the payment by the registrant of expenses incurred or paid by a director, officer or controlling person of the registrant in the successful defense of any action, suit or proceeding) is asserted by such director, officer or controlling person in connection with the securities being registered, the registrant will, unless in the opinion of its counsel the matter has been settled by controlling precedent, submit to a court of appropriate jurisdiction the question whether such indemnification by them is against public policy as expressed in the Securities Act of 1933 and will be governed by the final adjudication of such issue. |
II-5
SIGNATURES
Pursuant to the requirements of the Securities Act of 1933, the registrant has duly caused this Post-Effective Amendment No. 1 to registration statement to be signed on its behalf by the undersigned, thereunto duly authorized, in Fort Worth, Texas on the 21st day of September, 2026.
| PRESIDIO PRODUCTION COMPANY | ||
| By: | /s/ William A. Ulrich | |
| Name: | William A. Ulrich | |
| Title: | Chairman and Co- Chief Executive Officer | |
| By: | /s/ Christopher L. Hammack | |
| Name: | Christopher L. Hammack | |
| Title: | Co- Chief Executive Officer | |
Pursuant to the requirements of the Securities Act of 1933, this registration statement has been signed below by the following persons in the capacities and on the dates indicated.
| Signature | Title | Date | ||
| /s/ William A. Ulrich | Chairman, Co- Chief Executive Officer and Director | September 21, 2026 | ||
| William A. Ulrich | (Principal Executive Officer) | |||
| /s/ Christopher L. Hammack | Co- Chief Executive Officer and Director | September 21, 2026 | ||
| Christopher L. Hammack | (Principal Executive Officer) | |||
| * | Chief Financial Officer | September 21, 2026 | ||
| John Brawley | (Principal Financial Officer) | |||
| * | Chief Accounting Officer | September 21, 2026 | ||
| Gregg Lamb | (Principal Accounting Officer) | |||
| * | Director | September 21, 2026 | ||
| Daniel C. Herz | ||||
| * | Director | September 21, 2026 | ||
| Jerry Schretter | ||||
| * | Director | September 21, 2026 | ||
| Jeffrey S. Serota | ||||
| * | Director | September 21, 2026 | ||
| Jerry Silvey | ||||
| * | Director | September 21, 2026 | ||
| Tyson Taylor | ||||
| * | Director | September 21, 2026 | ||
| James E. Vallee | ||||
| * | Director | September 21, 2026 | ||
| Ray N. Walker, Jr. |
| * By: | /s/ William A. Ulrich | |
| William A. Ulrich | ||
| Attorney-in-Fact |
II-6